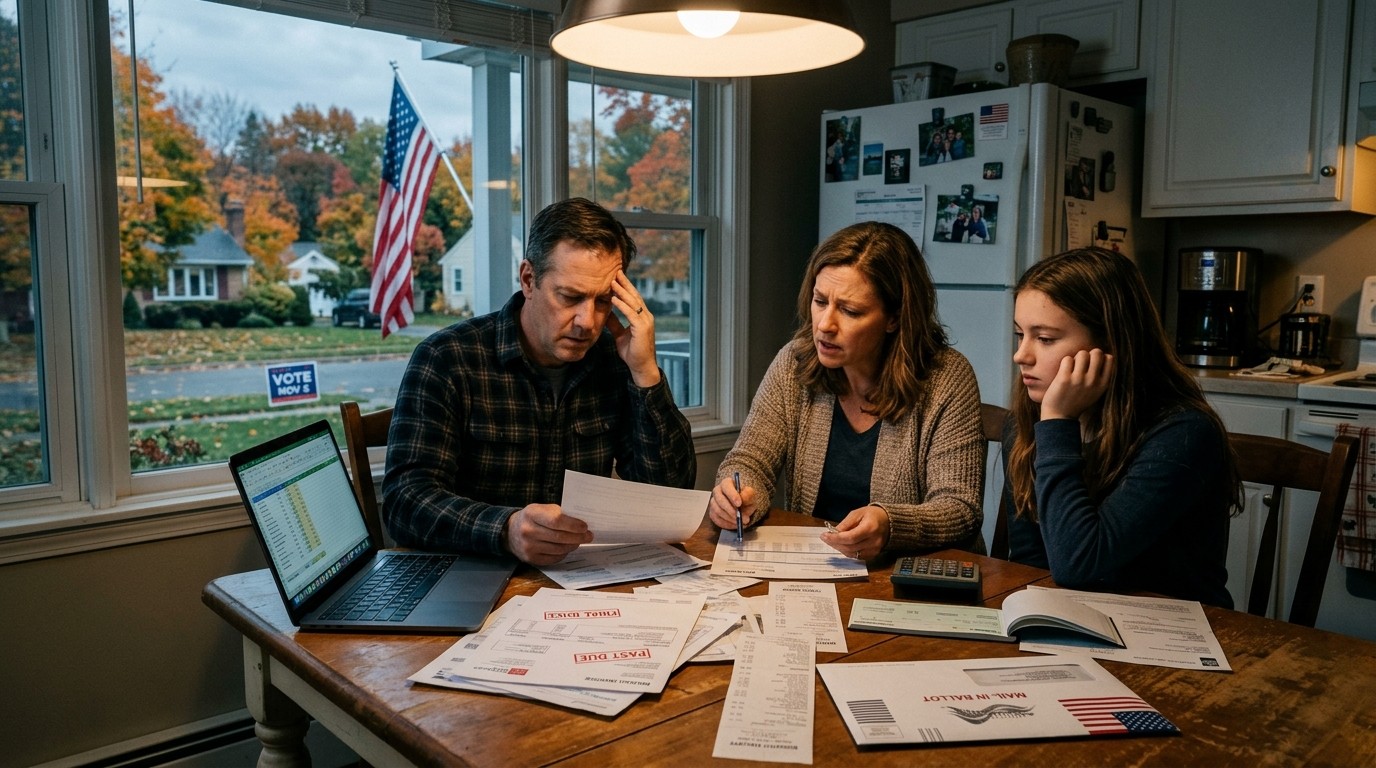

Have you checked the price of eggs or the balance on your mortgage statement lately and felt that quiet sense of unease settle in? I know I have. With the 2026 midterm elections just days away on November 3, that everyday pressure around cost of living has moved front and center in conversations across kitchen tables and campaign stops. Recent surveys of registered voters paint a clear picture: most Americans hold a pessimistic view of the economy right now, and affordability sits at the absolute core of what will influence their choices at the ballot box.
Why Pocketbook Pressures Define These Midterms
Affordability is not just one issue among many. Policy observers note it has become the central concern, far ahead of other topics. Rising prices for groceries, gas, housing, healthcare and childcare hit households in different ways, yet the overall feeling remains the same for a large share of people. In my view, this election serves as a real-time test of economic sentiment more than any other factor. When daily expenses feel heavier, voters tend to look closely at who they believe can ease that load.
The data backs this up. Two-thirds of adults report high concern about housing costs alone. That worry spans party lines, though the intensity varies. Democrats and those leaning that way express stronger concern than Republicans, yet the issue cuts across the board. High home prices and elevated borrowing costs have left many prospective buyers on the sidelines. At the same time, nearly half of renter households devote more than 30 percent of their income to rent and utilities, with millions spending over half. These numbers are not abstract. They represent real families making hard choices every month.
Housing Affordability Challenges Facing Buyers and Renters
Housing stands out as one of the most persistent pressure points. The median price of an existing home sits well above pre-pandemic levels even after only modest recent gains. That jump of more than 50 percent since 2019 has made ownership feel out of reach for a noticeable portion of younger and middle-income buyers. Borrowing costs compound the problem. When monthly payments climb because of interest rates, the path to a first home lengthens for many.
Renters face their own version of the squeeze. Nearly half of renter households spend over 30 percent of income on housing costs, a threshold long used to measure burden. Millions go further, allocating more than half their earnings to rent and utilities. I have spoken with people who describe cutting back on other essentials just to keep a roof overhead. That kind of trade-off shapes how they view candidates promising solutions.
Lawmakers did pass bipartisan legislation aimed at encouraging more construction, reducing regulatory barriers, expanding financing options and limiting large institutional purchases of single-family homes. Experts caution that short-term effects will likely remain modest. Longer term, the measure could support changes already underway at state and local levels that make building smaller homes for first-time buyers easier and less costly. Still, progress on housing supply takes time, and voters tend to respond to the pressure they feel today rather than projections years ahead.
The short-run effects will be modest at best, but in the longer term the act may accelerate the change occurring at the state and local levels to make it easier and less costly to build new houses, especially smaller houses for first-time homebuyers.
Improving housing affordability has drawn support across party lines, which is rare these days. Whether that consensus produces faster results remains an open question voters will weigh on election day.
Tax Policy Changes and Their Uneven Reach
Tax policy has featured prominently in campaign messaging. Recent legislation made permanent earlier tax changes while introducing new deductions for tip income, overtime earnings, seniors and auto loan interest. It also raised the federal deduction limit for state and local taxes for those who itemize. Officials have described the package as delivering relief directly to millions of low- and middle-income Americans.
Early projections suggested average tax refunds would rise by a thousand dollars or more in 2026. Actual figures showed a more modest increase for many filers. The average refund climbed, yet the benefit landed differently depending on each household’s unique situation. Some families saw meaningful help. Others noticed little change once all factors were considered.
Whether a larger refund from earlier this year will still influence votes in November is hard to predict. So many other issues compete for attention, from energy prices to broader affordability concerns. Tax policy often takes a back seat when daily costs dominate conversations. Surveys indicate most Americans care about taxes, yet fewer than one in ten rank it as the single most important election issue. In my experience watching these cycles, pocketbook pressures that feel immediate tend to outweigh longer-term policy details.
Still, the temporary nature of some provisions creates another layer. Certain senior deductions are scheduled to expire unless lawmakers act again. That timeline could matter for voters focused on retirement security.
Healthcare Costs and Premium Pressures
Anyone watching their health insurance premiums climb knows this issue hits hard. Many voters worry about their ability to afford coverage and care. Enhanced premium tax credits that once made marketplace plans more affordable for millions expired at the end of 2025. The result has been sharper rises in monthly premiums and an increase in the number of uninsured Americans.
Medicaid changes also entered the picture, including work requirements and more frequent eligibility checks for certain adults. With more than 60 million people enrolled in Medicaid and roughly 19 million in marketplace plans, the scale is significant. Policy experts note these patterns stem from explicit choices made in 2025. It would not be surprising if some voters look for shifts in Congress as a response.
Candidates on one side have found themselves defending votes related to these changes. On the other side, the focus remains on restoring affordability measures. Either way, the personal experience of higher premiums or coverage gaps tends to shape opinions more powerfully than abstract debate. I have found that healthcare costs often become a quiet but decisive factor for families already stretched thin.
Social Security Solvency on the Horizon
Senators elected this November will still hold office when a key funding deadline approaches. Projections show the retirement trust fund may face depletion around 2032. At that point only a portion of scheduled benefits would be payable unless Congress acts sooner. The next group of leaders will confront decisions about raising taxes, adjusting benefits or some combination of both.
Surveys consistently show voters prefer candidates who commit to protecting Social Security. On the campaign trail some have favored raising or eliminating the payroll tax cap that currently limits taxable earnings. Others have highlighted new deductions that reduce taxes on benefit income for seniors, even though those measures remain temporary.
The math is straightforward and unforgiving. Insolvency will force unpopular choices within the next six years. Some tax increases may become part of the solution. For voters who rely on these benefits or expect to soon, the issue carries real weight even if the crisis date still sits several years out. Protecting the program ranks high among concerns for older adults and those approaching retirement.
Interest Rates and the Affordability Crunch
Interest rates themselves do not appear on any ballot. The Federal Reserve sets monetary policy independently. Yet borrowing costs remain a top concern for many households, and the policies of the next Congress can influence inflation, which in turn affects rate decisions.
Recent inflation reports driven in part by higher energy costs have complicated the picture. The central bank raised rates to a new range last month, its first increase in several years. Markets currently assign a relatively low probability to another quarter-point hike in the immediate term. Historically the Fed has largely stuck to its course around elections when inflation pressures required action.
Looking ahead, inflation is expected to stay above the long-term target. Some analyses suggest continued unified control could present upside inflation risk if further tax cuts, tariffs or tighter immigration measures stimulate demand or constrain labor supply. Faster energy permitting and greater domestic production might offset some of those pressures. A divided government, by contrast, could reduce the odds of additional deficit-financed measures and ease inflationary forces on the margin.
Higher borrowing costs strain household budgets at the exact moment many already feel squeezed by other expenses. That combination keeps the affordability conversation alive even when rates are not a direct campaign plank.
Student Loan Burdens and Changing Rules
Student debt remains an affordability issue for millions. Roughly 9.3 million federal borrowers were in default as of mid-year. Others face higher payments under revised repayment options. Several million borrowers received a limited window to leave one income-driven plan that had offered the lowest monthly amounts. Timelines under the public service loan forgiveness program were also recalculated for some, extending the period before cancellation.
New annual borrowing caps took effect for graduate and professional students. Those limits are expected to make higher education more challenging for low- and middle-income students who rely on federal loans. If one party gains control of one or both chambers, priorities would likely include restoring earlier repayment options and adjusting the new caps. Continued control by the other side would mean further implementation of recent changes, including the elimination of certain repayment plans and payment pauses.
For borrowers already managing tight budgets, these shifts matter. Monthly payments that rise or forgiveness that arrives later can alter financial plans for years. That personal impact often translates into electoral preferences more clearly than broader policy arguments.
Family Caregiving Costs That Quietly Add Up
Providing care for an aging relative or loved one carries significant out-of-pocket expenses. One recent study found Americans in this role spend an average of more than eight thousand dollars a year of their own money. Careers and personal retirement savings often absorb the strain as well.
Polling in several states shows at least half of voters age 50 and older either currently serve as family caregivers or have done so in the past. Nearly three-quarters say they would be more likely to support a candidate who backs policies helping unpaid caregivers keep loved ones living independently at home. Rising health insurance premiums, copays and direct payments to providers only intensify the pressure on these households.
This issue rarely dominates headlines the way housing or inflation does, yet it touches a large share of the electorate. The combination of financial cost and emotional demand creates a distinctive form of affordability stress. Candidates who address it directly may find receptive audiences among voters who feel overlooked on this front.
How These Issues Intersect for Ordinary Households
None of these pressures exists in isolation. A family facing higher rent may also deal with climbing insurance premiums and student loan payments. Another household might balance mortgage costs against caregiving expenses for an elderly parent. The cumulative effect shapes overall economic sentiment more powerfully than any single line item.
I have noticed that people often describe a general sense of things feeling harder rather than pointing to one dramatic crisis. That diffuse frustration can prove decisive in midterm elections, when turnout patterns and candidate messaging interact with real household budgets. Candidates who acknowledge the full range of costs tend to connect more effectively than those focusing on a narrow slice.
Energy prices have added another layer this cycle. Higher costs stemming from geopolitical events feed into broader inflation readings and household fuel bills. Those increases arrive on top of the other pressures already discussed, reinforcing the feeling that everyday expenses remain elevated.
What Voters Appear to Prioritize Right Now
Survey after survey points to the same conclusion. Affordability ranks at the top. Housing costs generate particularly high concern. Healthcare access and premiums follow closely for many. Social Security protection matters strongly for older voters. Borrowing costs and student debt weigh on younger and middle-aged households. Caregiving expenses affect a substantial share of those over 50.
Tax policy generates interest but rarely emerges as the single decisive factor. Interest rate decisions remain outside direct electoral control, yet their consequences influence how voters evaluate the broader economic environment. The common thread remains the sense that daily life costs more and that policy choices either ease or intensify that reality.
- Housing prices and rents continue to strain budgets for both owners and renters
- Healthcare premium increases and coverage changes affect millions directly
- Social Security’s long-term funding gap will require action within this congressional window
- Student loan rules and repayment options create ongoing uncertainty for borrowers
- Family caregiving expenses quietly erode savings and career progress for many
Perhaps the most interesting aspect is how these issues cut across traditional demographic lines. Young renters and older homeowners both feel housing pressure, though in different forms. Working-age adults managing student debt and parents caring for aging relatives share a common experience of stretched resources. That breadth helps explain why affordability has pulled so far ahead of other topics.
Looking Ahead After Election Day
Whatever the outcome on November 3, the underlying pressures will not vanish overnight. Housing supply adjustments take years. Healthcare cost trends respond slowly to policy shifts. Social Security’s funding challenge remains on a fixed timeline. Interest rates will continue to reflect inflation data and labor market conditions. Student loan rules and caregiving support depend on the composition of the next Congress.
A divided government could limit major new deficit-financed initiatives and potentially ease some inflationary pressures at the margin. Unified control might open the door to further tax or regulatory changes with different inflation implications. Either path will still confront the same core affordability challenges that voters are highlighting today.
In my experience following these cycles, the post-election period often brings a temporary shift in focus before the practical realities of governing return attention to household budgets. The families currently weighing grocery bills against rent or insurance premiums will still face those decisions in December and beyond. How the next Congress responds will determine whether the current sense of pressure eases or intensifies.
The 2026 midterms offer a clear referendum on economic sentiment. Affordability has emerged as the dominant lens through which many voters view the choices before them. Housing, healthcare, taxes, retirement security, borrowing costs, student debt and caregiving expenses all contribute to that larger picture. Understanding these interconnected pressures provides the best guide to what is at stake when Americans cast their ballots this week.
Voters will ultimately decide based on their own circumstances and judgments. The data and expert assessments simply illuminate the landscape those decisions will shape. For households feeling the cumulative weight of higher costs, the election represents more than a political contest. It feels like a direct test of whether the system can deliver measurable relief on the issues that matter most in daily life.