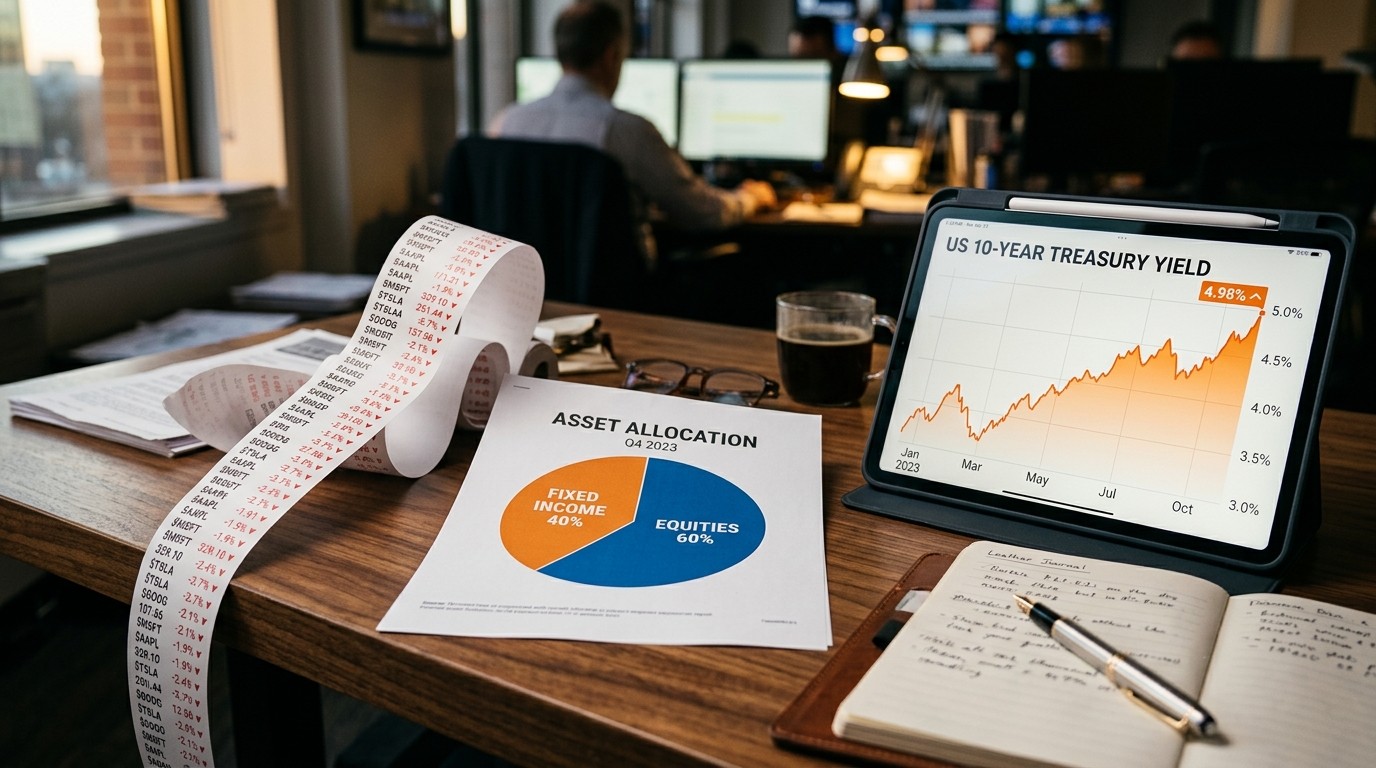

Have you ever opened your brokerage app on a supposedly “quiet” Wednesday and felt that little drop in your stomach? Stocks were down. Fine. You expected some of that. Then you checked the bond side and realized the so-called ballast was leaking too. That is the mood right now. Yields have pushed higher, prices have slipped, and the old 60/40 mix is taking hits on both sleeves at once.
I keep hearing the same question from people who thought they had already survived the ugly chapter. Is this 2022 again? Should you rip up the balanced playbook? In my experience, panic is a terrible editor. The numbers look uncomfortable, yes. They are not identical to that earlier shock, and that distinction matters more than the headline noise.
Why The Balanced Mix Is Taking Hits On Both Sides
A balanced allocation is simple on paper. Roughly sixty percent in equities for growth. Forty percent in bonds for income and ballast. When both sides fall together, the story people tell themselves about diversification starts to wobble. On a recent session, a broad equity benchmark slipped while the 10-year Treasury yield climbed above 5.1 percent, a level not seen since 2007. Bond prices move the other way when yields rise. That is not a trick. That is the math.
A popular fund that tracks a 60/40 mix dropped about one percent that day. Not a catastrophe. Still enough to make long-term holders stare at the screen and wonder if the structure is broken. I’ve found that the structure is rarely the first thing that breaks. Patience is.
Long live the 60/40 portfolio. It took a beating a few years ago, then recovered as higher starting yields did the quiet work of rebuilding income.
That is the part a lot of commentary skips. Yields are not only a threat. They are also the raw material of future coupon payments. After years of near-zero rates, the bond sleeve finally pays you something real. That income can offset price wobbles if you give it time.
This Selloff Is Not A Carbon Copy Of 2022
Let’s be honest. 2022 left scar tissue. Policy rates jumped from near zero to a restrictive range in a little over a year. Equities struggled. Duration got punished. A typical balanced fund could lose something in the mid-teens in a single calendar year. People who believed bonds would always zig when stocks zagged felt betrayed.
Today’s setup is different in one crucial way: the starting line. Back then, yields were unusually low. A big move up in rates crushed prices because there was almost no income cushion. Now the 10-year around five percent is an incremental climb from an already higher base. Still painful if you own long bonds. Far less of a free fall than the last cycle.
Multi-asset credit specialists have been repeating a simple line. High yields plus weak risk assets was the double hit last time. The current move is smaller in scale even if the headlines sound familiar. I tend to agree. Familiar is not the same as identical.
Income Is Doing More Work Than It Used To
Here is the unglamorous truth. Income is the part of a bond that does not need a press conference. Coupons keep arriving while prices bounce around. When starting yields are higher, that stream becomes a real diversifier, not a rounding error.
Think of it this way. A low-yield bond is a glass with almost no water. Tip the glass and it empties fast. A higher-yield bond has more water in it. Tip it and you still lose some, but you are not staring at a dry glass. That is why managers keep saying income can act as a cushion. It is not poetry. It is cash flow.
Does that mean you should ignore mark-to-market losses? Of course not. If you need to sell tomorrow, price is everything. If you can hold through a cycle, the coupon starts to matter more than the last tick on the screen.
Duration Still Decides Who Gets Bruised
Duration is the sensitivity of a bond’s price to rate moves. Longer dated paper has more of it. When yields climb, those long bonds take the bigger mark. Short and intermediate issues usually absorb the shock with less drama.
Portfolio strategists have been pretty blunt. If you sit in long duration and rates keep rising, you can still see losses. On the short and intermediate part of the curve, you are relatively better protected from further hikes. That is not a promise of zero volatility. It is a reminder that you can choose how much rate risk you actually want.
I’ve found the five-to-six-year area is a practical sweet spot for many long-term holders. You pick up meaningful yield without living on the far end of the curve where every basis point feels like a shove. Some will disagree and want more duration as a hedge if growth cracks. Fair. Know why you own it.
| Sleeve | Rate Sensitivity | Role In A 60/40 |
| Short-term high quality | Lower | Stability and reinvestment flexibility |
| Intermediate core bonds | Moderate | Income with manageable price swings |
| Long-duration Treasurys | Higher | Hedge if growth slumps, more pain if yields rise |
| Lower-quality credit | Mixed | Extra yield, more equity-like behavior |
Credit Quality Is The Quiet Diversifier
Yield hunting is tempting when coupons look generous. Stretch too far down the quality ladder and you may buy a bond that moves with stocks when you need it least. Default risk is only half the story. Correlation is the other half.
Depending on your risk tolerance, a core of investment-grade paper still makes sense for most balanced investors. You want the bond sleeve to behave like bonds when equities wobble. High-yield and thinly traded credit can pay more. They also tend to sell off with risk assets. That is not diversification. That is a second equity bet wearing a coupon.
Perhaps the most interesting aspect is how little this point has changed. People forget it every cycle. Then they remember it the hard way.
A Practical Checklist Before You Touch The Mix
If you are staring at red numbers and itching to “do something,” slow down. Action feels productive. It is often just expensive motion. Walk through a short list instead of rewriting the entire plan on a volatile afternoon.
- Confirm your time horizon. Money needed in two years is not the same as money needed in twenty.
- Map duration. Know whether your bond funds sit short, intermediate, or long.
- Check credit mix. Investment grade versus lower quality changes how the sleeve behaves in a stock drop.
- Look at income, not only price. What yield are you actually collecting now?
- Decide if inflation protection belongs in the mix, especially near retirement.
None of that requires a dramatic overhaul. It requires knowing what you already own. You would be surprised how many people cannot name the duration of their largest bond fund. That is the first homework assignment.
Where Inflation-Linked Bonds Fit For Retirees
If you are at or near retirement, purchasing power is not an abstract debate. Treasury inflation-protected securities adjust principal with a consumer price index. Interest is paid on that adjusted principal. You can buy individual issues in modest increments through government channels, or you can use funds that hold a basket of them.
They still act like bonds. Long-dated issues will swing when rates move. Fund duration can differ a lot. One short inflation-protected fund might sit around two and a half years of duration. A broader fund can sit above six. That gap is not trivia. It is the difference between a mild wobble and a stomach-turning week.
Stick with intermediate-term inflation-linked paper if you want protection without turning the sleeve into a duration bet. For people trying to build a steady cash-flow stream, a ladder with staggered maturity dates can keep principal coming due on a schedule you can plan around. I like ladders for that reason. They are boring. Boring is underrated.
What Higher Yields Change About Rebalancing
Rebalancing used to feel like a mechanical chore. Sell a bit of the winner, buy the laggard, keep the 60/40 shape. When both sides fall, the chore gets emotional. You are buying assets that just hurt you. That is exactly when the rule earns its keep.
Higher yields change the math of that buy. You are not scooping up bonds that pay almost nothing. You are adding paper that throws off more income than it did in the easy-money years. That does not guarantee a quick rebound. It does mean the capital you put to work has a better carrying yield while you wait.
Some households will tilt a few points toward shorter bonds until the rate path looks clearer. Others will hold the line and let coupons do the compounding. Either choice can be rational. The irrational move is dumping the entire fixed-income sleeve because one week felt like 2022.
The Psychology Of Watching Both Sides Fall
There is a reason balanced portfolios feel personal. They are the compromise people make when they do not want to live like traders. When the compromise fails in public, it feels like the plan itself was a lie. It was not a lie. It was a tool with limits.
Stocks and high-quality bonds can fall together when inflation or policy surprises reset the discount rate. That happened before. It will happen again. Diversification is about reducing the chance that everything fails for the same reason over a long stretch. It is not a daily insurance policy against red ink.
I’ve sat with people who sold the bond sleeve after a bad quarter and then watched yields settle while they sat in cash earning less than they needed. That regret lasts longer than a one-percent down day. Keep that in mind before you treat a yield spike as a verdict on the whole idea of balance.
How To Think About The Next Move In Rates
Nobody has a clean crystal ball. If they did, they would not be writing checklists. The useful question is not “where will the 10-year be in December?” The useful question is “what breaks in my plan if yields grind higher from here, and what breaks if they fall?”
- If yields grind higher, long duration hurts first. Short and intermediate income keeps paying.
- If yields fall because growth slows, longer high-quality bonds can cushion equity weakness.
- If inflation stays sticky, nominal long bonds struggle and inflation-linked paper earns its keep.
- If credit spreads blow out, lower-quality holdings start acting like stocks.
Write those four paths down. Match them to what you actually hold. If every path hurts the same sleeve, you do not have balance. You have a concentrated rate or credit bet with a friendly label.
Funds Versus Individual Bonds When Yields Jump
Funds are convenient. They also show you a price every day. Individual bonds, held to maturity, let you focus on the coupon and the par value coming back, assuming no default. That mental difference is huge during a selloff.
I am not arguing that everyone should build a Treasury ladder by hand. Plenty of households should stay in diversified funds. I am arguing that you should know whether your vehicle forces you to care about daily marks. If the mark makes you impulsive, a ladder of high-quality issues with known maturity dates can be calmer to live with.
Funds still win on liquidity and simplicity. Just do not confuse simplicity with immunity. A fund with long duration will print ugly numbers when yields rip higher. That is the product doing what the product does.
Why The Rulebook Still Deserves A Seat
After the last hard year for balanced portfolios, a lot of obituaries were written. Then yields reset higher and the income engine started working again. The last three years reminded people that a 60/40 is not a museum piece. It is a living mix that depends on starting yields more than slogans.
Does that mean 60/40 is sacred? No. Some investors want 70/30. Some want more alternatives. Some need a bigger cash buffer near retirement. Fine. The point is not the exact ratio. The point is holding growth assets and ballast assets that do not always share the same drivers.
The starting point today is dramatically different from the last hiking cycle. Treat the current yield level as information, not as a rerun of an old movie.
That line is worth taping to the monitor. Movies have sequels. Markets have rhymes. Rhymes still leave room for a different ending.
Small Adjustments That Usually Beat Big Swings
If you feel you must adjust, prefer small knobs. Trim a slice of long duration rather than abandoning bonds. Upgrade credit quality rather than chasing the last extra half point of yield. Add a measured inflation-linked sleeve rather than turning the whole portfolio into a macro forecast.
Those tweaks keep you in the game. Big swings tend to lock in the pain and miss the repair. Markets are rude that way. They often start healing while you are still drafting the revenge trade.
A simple working frame:
  Know your duration
  Collect the coupon
  Keep credit honest
  Rebalance on purpose
  Leave room for inflation protection
It is not clever. It is usable. On weeks when both stocks and Treasurys get thumped, usable beats clever.
Who Should Worry More, And Who Can Sit Tight
Near-term spenders should worry more. If tuition or a home purchase sits on a short calendar, price risk is real. Shift that slice toward shorter high-quality paper or cash-like instruments and stop pretending a long bond fund is a savings account.
Long-horizon investors can sit tighter. They can harvest the higher income and accept ugly statements. They can even add a little when others are selling, provided the plan still matches their risk budget. That last clause matters. Heroic buying without a budget is just another form of guessing.
Retirees sit in the middle. They need income and they need some protection against a nasty inflation surprise. They do not need to win a duration contest. Intermediate quality bonds plus a thoughtful inflation-linked sleeve is usually enough architecture. Fancy is optional.
The Sentence Worth Remembering When The Screen Turns Red
A 60/40 portfolio is not a promise that Wednesday will be pleasant. It is a framework for owning productive assets without betting the whole household on a single story. Yields can surge. Stocks can slump on the same day. The mix can still be the right home for money that has years of work left to do.
If you take one thing from this stretch of market noise, take this. Check duration. Respect income. Stay picky on credit. Add inflation protection if your spending life depends on it. Then give the coupons time to do the quiet job they were hired to do.
That will not make the next down day fun. It might keep you from tearing up a plan that still has a lot of life left in it.