
Have you ever unwrapped a chocolate bar and assumed the whole thing was born a few miles from the shop? I used to think that way. Then you sit with the logistics of a global snack business and realize how many weeks a single ingredient can spend on the water before it ever meets sugar, milk, and a wrapping machine. That gap is exactly what a new plant in Shah Alam is trying to close.
Why A Local Crumb Plant Changes The Cadbury Equation
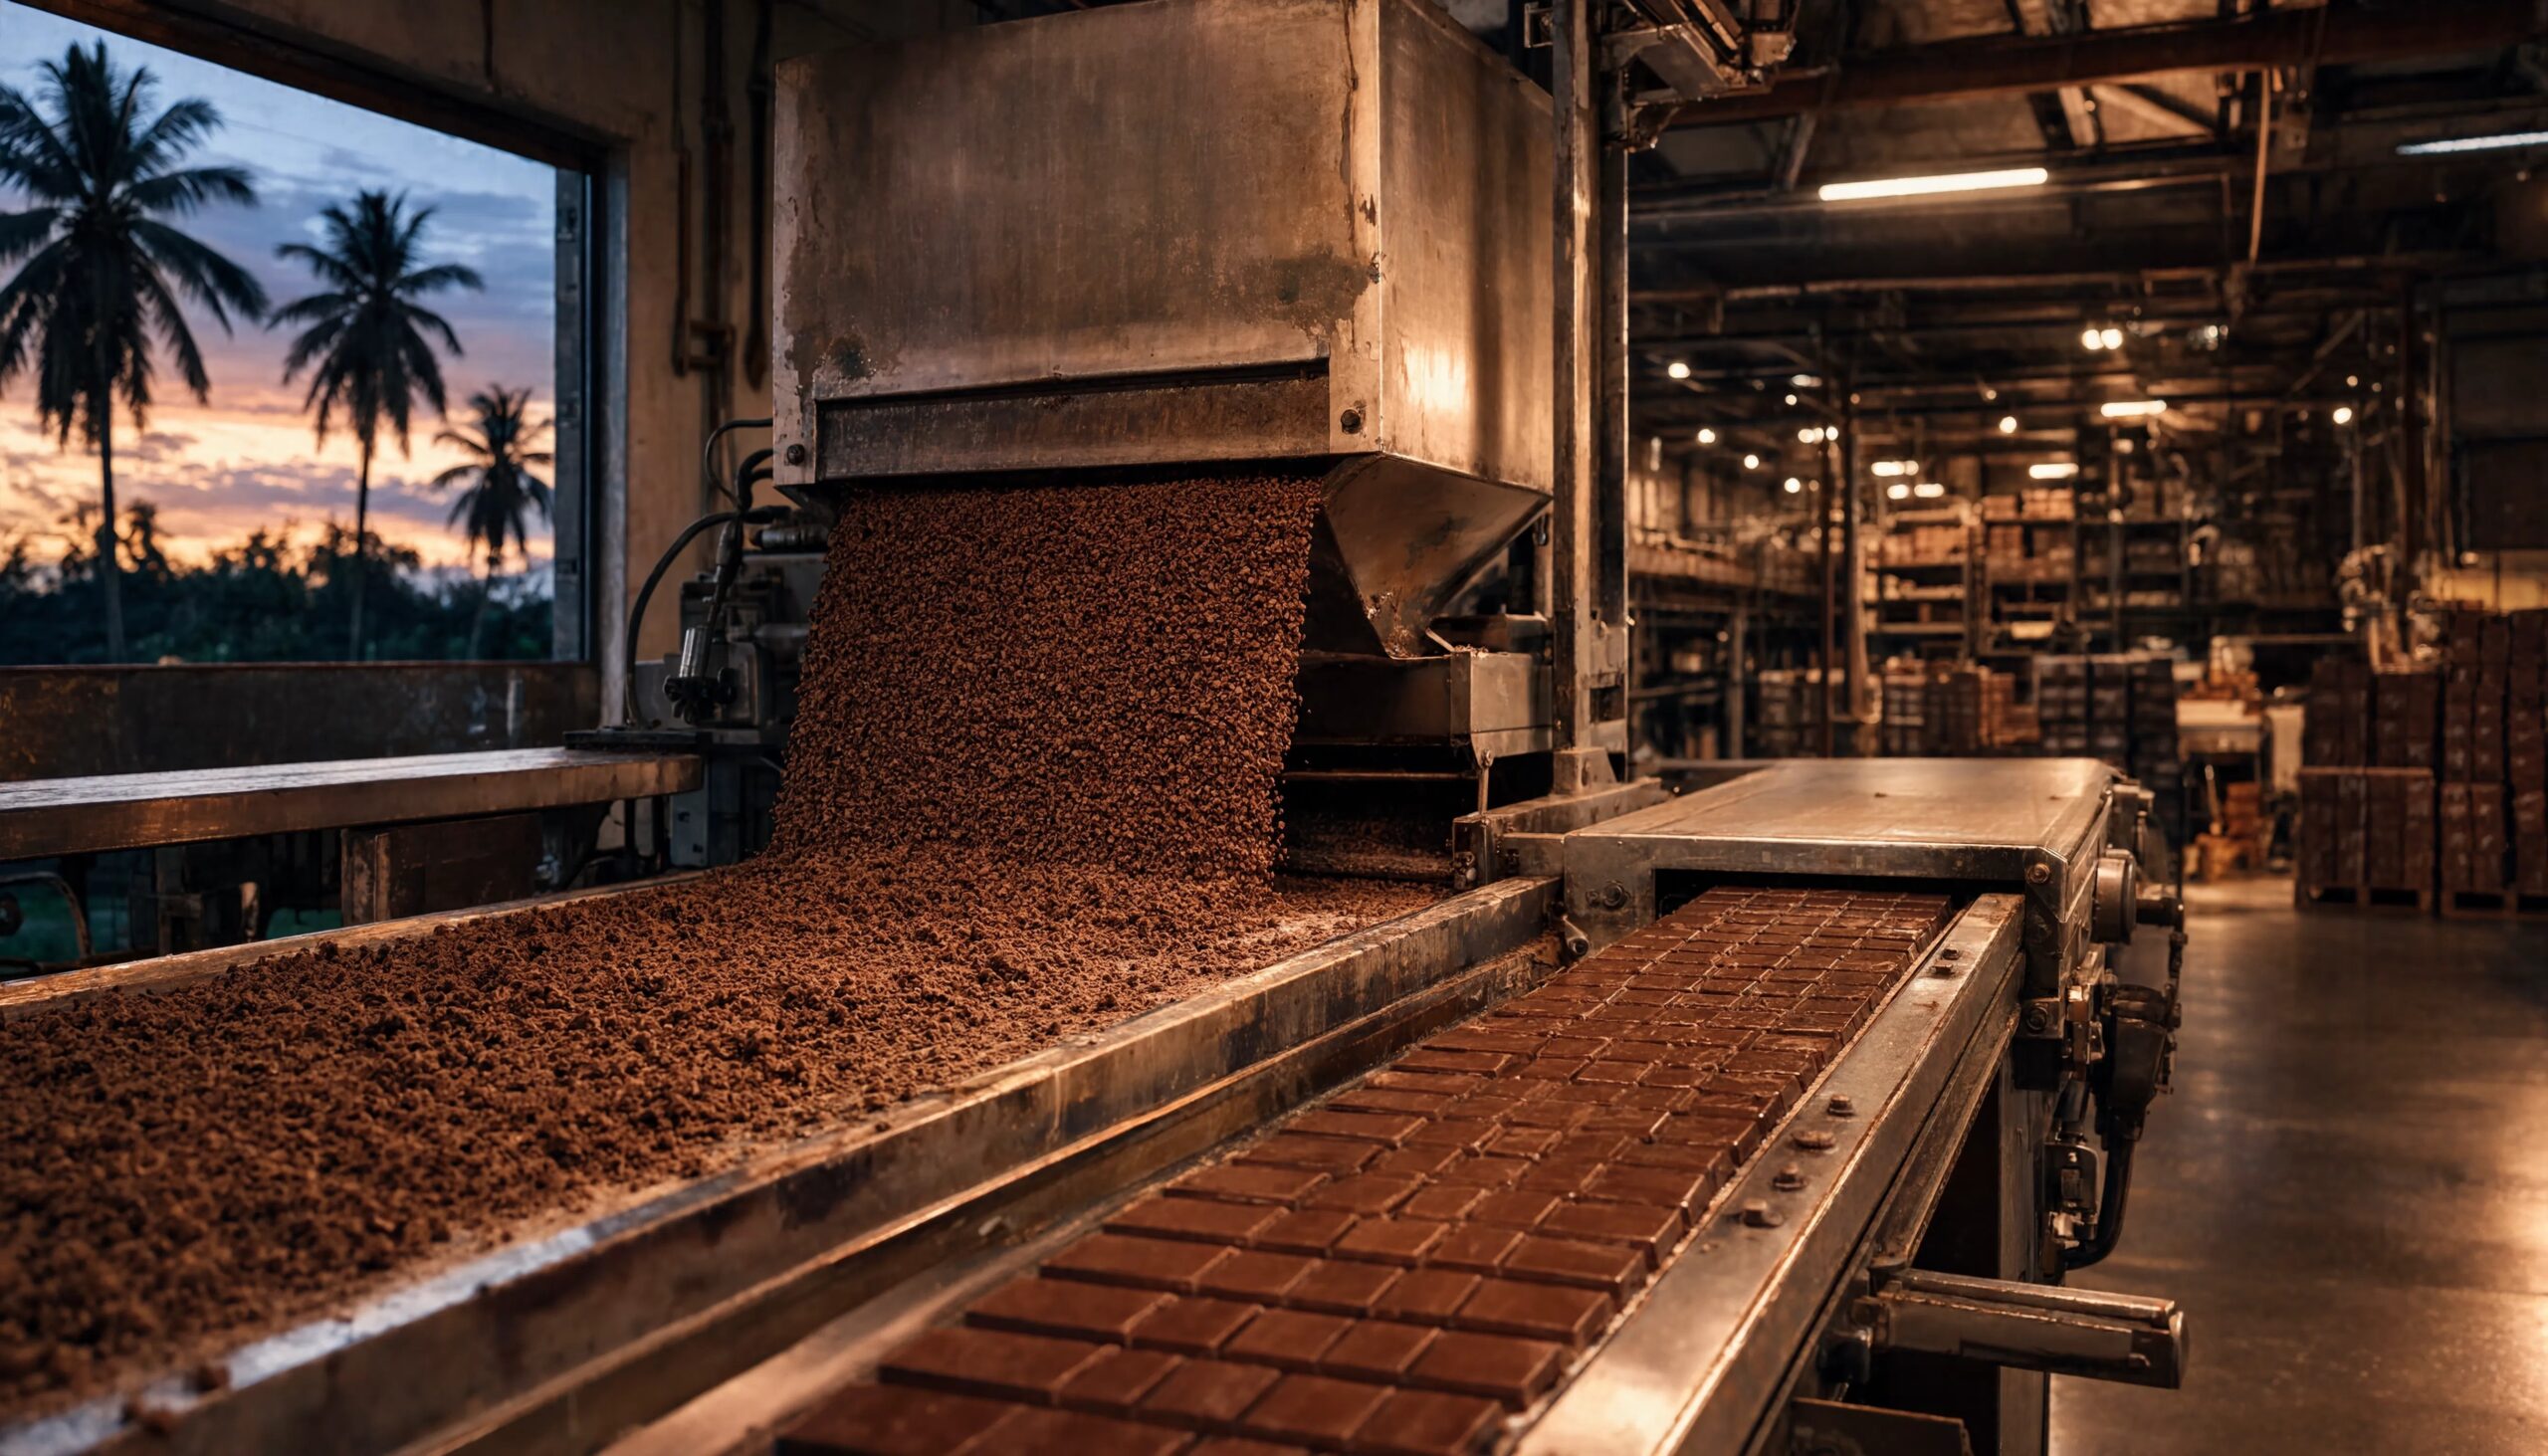
Mondelez International has opened a $22 million facility in Shah Alam, Malaysia, built to make chocolate crumb on site rather than pull it in from Australia and South Africa. Crumb is not a side note. It is the ingredient that helps give Cadbury products their familiar taste and bite. When that input travels half a world, every delay becomes a planning problem. Two months off the clock is not a vanity metric. It is breathing room.
Nitin Binnani, who leads customer service and logistics for the AMEA region, put it plainly. Producing crumb directly in Shah Alam removes at least two months from supply-chain lead time. I like that kind of sentence. No fluff. Just a number you can feel in inventory and in the cash tied up on ships.
Producing it directly in Shah Alam removes at least two months from our supply-chain lead time.
– Regional logistics leader at Mondelez International
Shah Alam is already the company’s sole Cadbury manufacturing hub for Southeast Asia. More than 130 varieties come out of that site. Around 100 million bars a year. When the crumb arrives late, the whole mix of SKUs starts to wobble. When it arrives from next door, planners can stop building extra buffer for ocean weather and port queues.
What Chocolate Crumb Actually Does On The Line
People talk about cocoa as if it were the whole story. It is not. Crumb sits in that middle layer between raw materials and finished chocolate. It helps lock in flavor and texture that regular consumers would never name, but they would notice if it vanished. I’ve found that the ingredients nobody photographs are usually the ones that decide whether a factory can run five days or three.
Importing crumb from Australia and South Africa meant long voyages, extra handling, and a cost stack that grew every time freight rates twitched. Local production does not erase cocoa risk. It does cut the distance between a key process step and the bars that leave Malaysia for regional shelves.
- Shorter transit for a taste-critical input
- Lower import and transport bills on that lane
- Faster reaction when demand spikes in nearby markets
- Less inventory sitting in containers instead of in production
None of this is glamorous. It is the unglamorous work that keeps a household brand from looking empty in a convenience store in Jakarta or Kuala Lumpur. In my experience, that is where most supply-chain stories actually live.
Southeast Asia Is No Longer Just A Destination Market
The company is not whispering about the region. It sees more room for snacking growth across Southeast Asia. That view sits on top of a network that already works both ways. Plants do not only feed the country they sit in. They feed other countries too.
The Cikarang site in Indonesia, for example, sends products to nearly 40 countries, including Australia and Japan. Thailand operates as an export-oriented hub for gum and candy. Malaysia now tightens the Cadbury chocolate loop with local crumb. You can almost draw the map with a pen. Input closer to output. Output closer to hungry cities.
Perhaps the most interesting aspect is how ordinary this sounds until you remember cocoa’s recent history. Prices ripped higher over two years on weather damage and weak harvests. Costs climbed for every chocolate maker that could not hide. Prices have eased since that peak, which gives operators a window. A window is useful only if you spend it on structure, not slogans.
Lead Time Is A Money Story Disguised As A Logistics Story
Two months sounds abstract until you convert it. Working capital sits in unfinished goods. Safety stock sits because planners do not trust the calendar. Retailers still want the same fill rate. If you shave weeks off an ingredient lane, you can hold less, miss less, and argue less with commercial teams about why a flavor is late.
I keep coming back to a simple question. Would you rather manage a plant that waits on two distant origins, or a plant that makes the critical input on the same industrial campus? The answer is not always local. Sometimes a specialist factory far away is still better. Here, the volume already exists in Shah Alam. The case for proximity is obvious.
| Factor | Imported crumb | Local crumb |
| Typical lead time | Long ocean plus handling | Cut by at least two months |
| Freight exposure | High | Much lower on this step |
| Planning buffer | Heavy | Tighter and more flexible |
| Fit with SEA volume | Indirect | Direct support for growth |
Tables flatten the drama, which is the point. A factory opening is not a movie. It is a set of trade-offs that either pay or do not. On paper, this one pays in time and in transport cost. Time is the piece retailers feel first.
Cocoa Calm Is Helpful, Not A Free Pass
After a brutal rally, cocoa has given manufacturers a little air. That does not mean the farm side is settled. Weather still swings. Disease still shows up. West African harvests still set the mood for half the industry. A crumb plant in Malaysia does not grow beans. It changes how beans and other inputs become a Cadbury-ready mass closer to the consumer.
That distinction matters. Investors sometimes treat every factory headline as a hedge against commodity pain. It is only a hedge against distance and delay. Commodity pain remains a separate file. Still, when input prices cool, capital projects look smarter. Boards like building when the raw material fire is not at the door.
I’ve watched companies freeze projects in the middle of a commodity spike and then regret the freeze when demand returns. Timing is never perfect. Opening now, with regional snacking still expanding, looks less like a vanity build and more like catching up with the volume the site already carries.
Why Malaysia Keeps Showing Up On Ingredient Maps
Malaysia is not new to food processing. Ports, industrial parks, and a long habit of export manufacturing make it a practical place to park mid-stream capacity. Mondelez is not even alone among U.S.-rooted groups adding chocolate-related capability there. Another large agribusiness player expanded specialty fats capacity in Port Klang earlier this year, including lines used in chocolate making.
When two different firms add related capacity in the same country in the same season, you pay attention. It usually means the region’s demand plus its export role finally outgrew the old import pattern. Or it means freight and risk finally got expensive enough to justify steel and concrete. Often it is both.
- Confirm the plant already has scale worth feeding.
- Measure the real lead time on the imported input, not the brochure time.
- Price local production against freight, duty, and buffer stock.
- Check whether nearby markets can absorb extra finished goods.
- Keep a backup origin so a single site does not become a single point of failure.
That last point is easy to skip. Localization can create a new concentration risk. The company is already sending crumb to Pakistan to help with supply interruptions tied to shipping channels. So the network is not only pulling inward. It is also pushing outward when another corridor breaks. That is a healthier picture than a plant that only serves itself.
A Network That Already Thinks In Corridors
Look at the pattern. Indonesia as a multi-country shipper. Thailand as a gum and candy export engine. Malaysia as the Cadbury chocolate engine for Southeast Asia, now with crumb on the same map. Pakistan as a destination for crumb when shipping lanes get messy. This is corridor thinking. Not one factory, one country, one story.
Corridor thinking is how large snack groups survive political weather, canal delays, and sudden retail spikes around festivals. You do not need every ingredient in every country. You need the bottleneck ingredients close to the bottleneck plants. Crumb was a bottleneck. They moved it.
The plants that win the next decade will be the ones that sit on corridors, not the ones that sit on slogans about being global.
That is my read, not a company line. Global is a nice word until a container misses a window and a promotion dies. Regional is a nicer word when the promotion is next week.
What Growth In Snacking Really Asks Of A Factory
Growth in Southeast Asia is not a single flavor of growth. Urban shoppers want convenience. Traditional trade still matters. E-commerce adds odd order sizes. Festive seasons still crush lines for a few weeks and then go quiet. A crumb plant does not solve assortment strategy. It does make it less painful to run 130-plus varieties without praying to a distant silo.
Variety is expensive. Every extra SKU wants its own changeover, its own forecast, its own wrapper. If the shared ingredient is late, variety becomes a tax. If the shared ingredient is local, variety becomes a commercial tool again. That is the quiet link between a $22 million building and the chocolate aisle.
Would I call this a transformation of the entire confectionery map? No. That would be overselling. It is a sharp, local fix on a high-volume platform. Those fixes compound. One fewer delay here, one cheaper lane there, and suddenly the region can take volume that used to wait on another hemisphere.
The Brand Heritage And The Industrial Reality
Cadbury still carries a lot of emotional weight. People attach childhood to it. Factories do not run on emotion. They run on crumb, cocoa mass, milk components, energy, labor, and trucks that show up. Holding both ideas at once is the job. Keep the taste familiar. Keep the line moving. Do not let romance about the brand hide a two-month wait.
Mondelez, based in Chicago, also owns names such as Oreo, Ritz, and Sour Patch Kids. The portfolio is a mix of ritual snacks and impulse snacks. Chocolate is the ritual piece in many markets. Ritual products punish stockouts more than impulse products do. You can miss a new chip flavor. Missing a familiar chocolate during a holiday is a different kind of bruise.
That is why I treat this plant as a reliability project first and a cost project second. Cost savings are real. Reliability is what protects the name on the wrapper.
How Investors Might Read A $22 Million Check
Twenty-two million dollars is not a moonshot inside a company of this size. It is a targeted bet. The right way to judge it is not the ribbon. It is whether lead time actually falls by those two months once the line is at rate, whether freight on that input drops as advertised, and whether Shah Alam can keep lifting volume without new bottlenecks appearing one step downstream.
Simple scorecard after year one:
  Lead time vs old import lane
  Cost per ton of crumb
  Service level on key Cadbury SKUs
  Export flexibility when other regions call
  Residual risk if the new site pauses
If those boxes stay green, the story was never about Malaysia as a slogan. It was about putting a process step where the bars already are. If they go red, then local is just a longer word for concentrated risk. I would watch the backup plan as closely as the opening photos.
Shipping Disruptions Make Local Inputs Look Less Optional
The mention of crumb moving to Pakistan because shipping channels were interrupted should not be a footnote. It is the plot. Ocean trade has spent recent years reminding everyone that routes are political and mechanical at the same time. A delayed canal, a crowded port, a sudden insurance spike, and your tidy plan becomes a scramble.
When you can make a critical input in-region, you gain a spare gear. You can still ship. You just do not have to ship as far for the first transformation. That spare gear is worth more than a press line about investment dollars.
Does every chocolate company need a crumb plant in every hub? Of course not. Duplicate assets are a tax. The test is volume, distance, and how nasty the old lane has become. Shah Alam clears that test on volume. The old lane cleared it on nastiness.
Consumers Will Not See The Plant. They Will Feel The Shelf
Shoppers do not tour Shah Alam. They notice whether the bar they want is there on a Thursday night. They notice price. They notice if a favorite format disappears for a month. Supply-chain wins show up as boredom, in the best sense. Nothing dramatic happens. The product is just there.
That boredom is hard to market. It is easy to underestimate. I would rather a company brag less and stock more. The crumb project is in that family of decisions. Quiet if it works. Loud if it fails.
- Fewer gaps on priority chocolate lines
- More room to support seasonal peaks
- Better odds of keeping regional prices from absorbing extra freight
- A cleaner story for retailers who hate surprises
Retailers live on surprises they did not ask for. A manufacturer that can promise a shorter internal clock becomes easier to plan with. That relationship is not romantic. It is operational. It still decides who gets the better display.
A Brief Word On Taste, Texture, And Trust
Moving crumb production is not supposed to change the eating experience. If it does, the project failed in a different way. The whole point of specifying crumb is consistency. Localizing the process should protect that consistency by reducing age and handling on the input, not by rewriting the recipe in secret.
Trust in a chocolate brand is strangely fragile. People will forgive a lot in other categories. They get picky about melt and snap. So the industrial story and the sensory story have to stay married. Shorter lead time should mean fresher process flow, not a different bar.
In my experience, the teams that treat sensory specs as non-negotiable are the same teams that get localization right. The teams that treat localization as a cost-only exercise eventually explain a flavor drift they did not budget for.
What This Signals For The Wider Snack Map
Zoom out. Large packaged-food groups have spent years talking about being closer to growth markets. Sometimes that meant a sales office. Sometimes it meant a warehouse. A crumb facility is a deeper commitment. It says the region is not a side market you supply when the main plants have leftover capacity. It is a production center with its own gravity.
Other categories will copy the pattern where the math works. Not everywhere. Not for every ingredient. Mid-stream inputs with nasty logistics and high sensory importance are first in line. Crumb fits. Some fats fit. Some dairy components fit. Raw beans often will not, because agronomy still lives where agronomy lives.
So the lesson is selective localization, not a fantasy of total self-sufficiency. Selective is adult. Total is a brochure.
Risks That Still Sit On The Table
I would be sloppy if I ended on a victory lap. Concentration risk is real. Energy costs in a new plant can surprise you. Talent for specialized confectionery processes is not infinite. If the site stumbles, you have moved the bottleneck instead of removing it. Commissioning always looks cleaner in a speech than on a night shift.
There is also the simple risk that demand growth is lumpier than the slide deck. Southeast Asia has a strong snacking case. It is not a straight line. Currency moves, household budgets, and retail competition can slow a beautiful capacity plan. A plant built for growth needs a plan for a flat year too.
Capacity is only an advantage if the calendar and the customer show up together.
Harsh? A bit. Also fair. Factories do not get to choose the year they live in after the ribbon is cut.
How I Would Explain This To A Friend Who Does Not Follow Stocks
Imagine your favorite bakery used to wait two months for a special mix that makes the brownies taste like themselves. The mix came from two far-off kitchens. Now they built a small room next to the ovens and make the mix there. Same brownies. Less waiting. Fewer excuses when the weekend rush hits. That is the whole article, minus the corporate nouns.
The nouns still matter if you follow the company. They tell you where capital is going and which region management believes will pull more than its share. Malaysia just received a clearer vote.
The Practical Takeaway
A Cadbury supply chain that used to lean on distant crumb origins now leans on Shah Alam. Lead time drops by at least two months on that step. Import and transport costs on the same step should follow. The plant sits inside a hub that already makes more than a hundred million bars a year and more than a hundred recipes. Nearby sites already export widely. Crumb can even travel to markets hit by shipping trouble.
That is a coherent design. Not a miracle. A design. I prefer designs to miracles. Miracles do not survive a bad harvest or a jammed port. Designs at least give you a second move.
If you work in operations, steal the question, not the press language. Which input on your line burns the most calendar for the least good reason? That is your crumb. Maybe you cannot build a $22 million room. Maybe you can change origin, change pack size, or change the safety-stock rule that exists only because nobody trusted the boat. The principle travels farther than chocolate.
And if you just like the bar itself, you do not need the principle. You need the shelf to stay full and the taste to stay familiar. On that score, shortening the path of a quiet ingredient is one of the more honest things a snack company can do. No fireworks. Just less ocean between the idea of Cadbury and the thing in your hand.