
Have you ever watched a currency rally and still heard the people who should be cheering ask for the opposite? That is the strange mood around the weak yen right now. I have covered exchange-rate swings for years, and this one feels different. Executives who usually smile when the yen slides are saying, almost in the same breath, that the move has gone too far for Japan as a whole.
The yen has firmed a little after a burst of optimism in Japanese equities and after markets started pricing a more careful fiscal path. Even so, it is still cheap by the standards of the last decade. The ten-year average sits far stronger than today’s print. That gap is exactly why boardrooms are restless.
Why Japanese Leaders Suddenly Want A Stronger Yen
On paper, a soft currency is a gift to exporters. Dollar invoices turn into fatter yen profits. Energy producers with most of their sales booked in greenbacks get a translation boost. Shipping groups that collect freight in dollars look healthier when they convert cash home. So why the complaints?
Because strategy needs a number they can trust. When the rate whipsaws, capital plans freeze. Plants, hiring, and long-term contracts all sit on hold. In my experience, that planning fog matters more than a single quarter of extra profit. You can book a currency gain once. You cannot run a factory on guesswork for three years.
The Manufacturer Who Would Bring Work Home
Consider a heavy-industry group with dozens of plants abroad and fewer at home. Its chairman put it bluntly. When the yen jumps around, the firm cannot set a clean strategy. He called that the biggest problem, not labor costs, not demand, not even geopolitics. Currency noise sits at the top of the list.
He went further. If the yen strengthened toward 150 against the dollar, he would look hard at moving manufacturing back to Japan from the United States. That is not a throwaway line. Relocating production is expensive, slow, and political. You only float that idea if the exchange rate has started to rewrite the cost map.
When the yen fluctuates, we cannot make a strategy.
– Heavy industry chairman speaking on the sidelines of an energy gathering
I find that remark more revealing than any spreadsheet. It tells you the weak yen is no longer just an earnings tailwind. It is a planning headache that can flip the location of real machines and real jobs.
An Energy Major That Still Prefers One Hundred
Then there is the oil company that books nearly all of its business outside Japan and in dollars. A weaker yen should be simple good news. Convert those dollars, and the home-currency line looks better. In the first half of the year, sales volumes slipped, yet a weaker yen helped cushion the drop. The firm itself noted that a move toward roughly 158 yen per dollar offset part of the volume hit.
And still the chief executive said 100 would be the appropriate level for the Japanese economy. That is a huge gap from the market. It is also a public admission that company-level gains and national-level health are not the same thing.
If we look at the Japanese economy as a whole, the current exchange rate is perhaps too weak.
– Energy major chief executive
Perhaps the most interesting aspect is how calmly he said it. No drama. Just a judgment that the currency has drifted past the point where the country benefits, even if his own conversion math still works.
Shipping Comfort In A Narrow Band
The world’s largest tanker owner and operator made a similar point in slightly softer language. Revenue arrives mainly in dollars, so a cheap yen helps. Comfort, he said, would sit around 150 to 155. What he does not want is a messy financial market born from a currency that looks broken.
That is the quiet fear under all these interviews. A disorderly yen can spill into funding markets, import bills, and household confidence. Corporate treasurers can hedge some of that. They cannot hedge a whole country feeling poorer when it shops for energy, food, and travel.
What The Numbers Actually Show
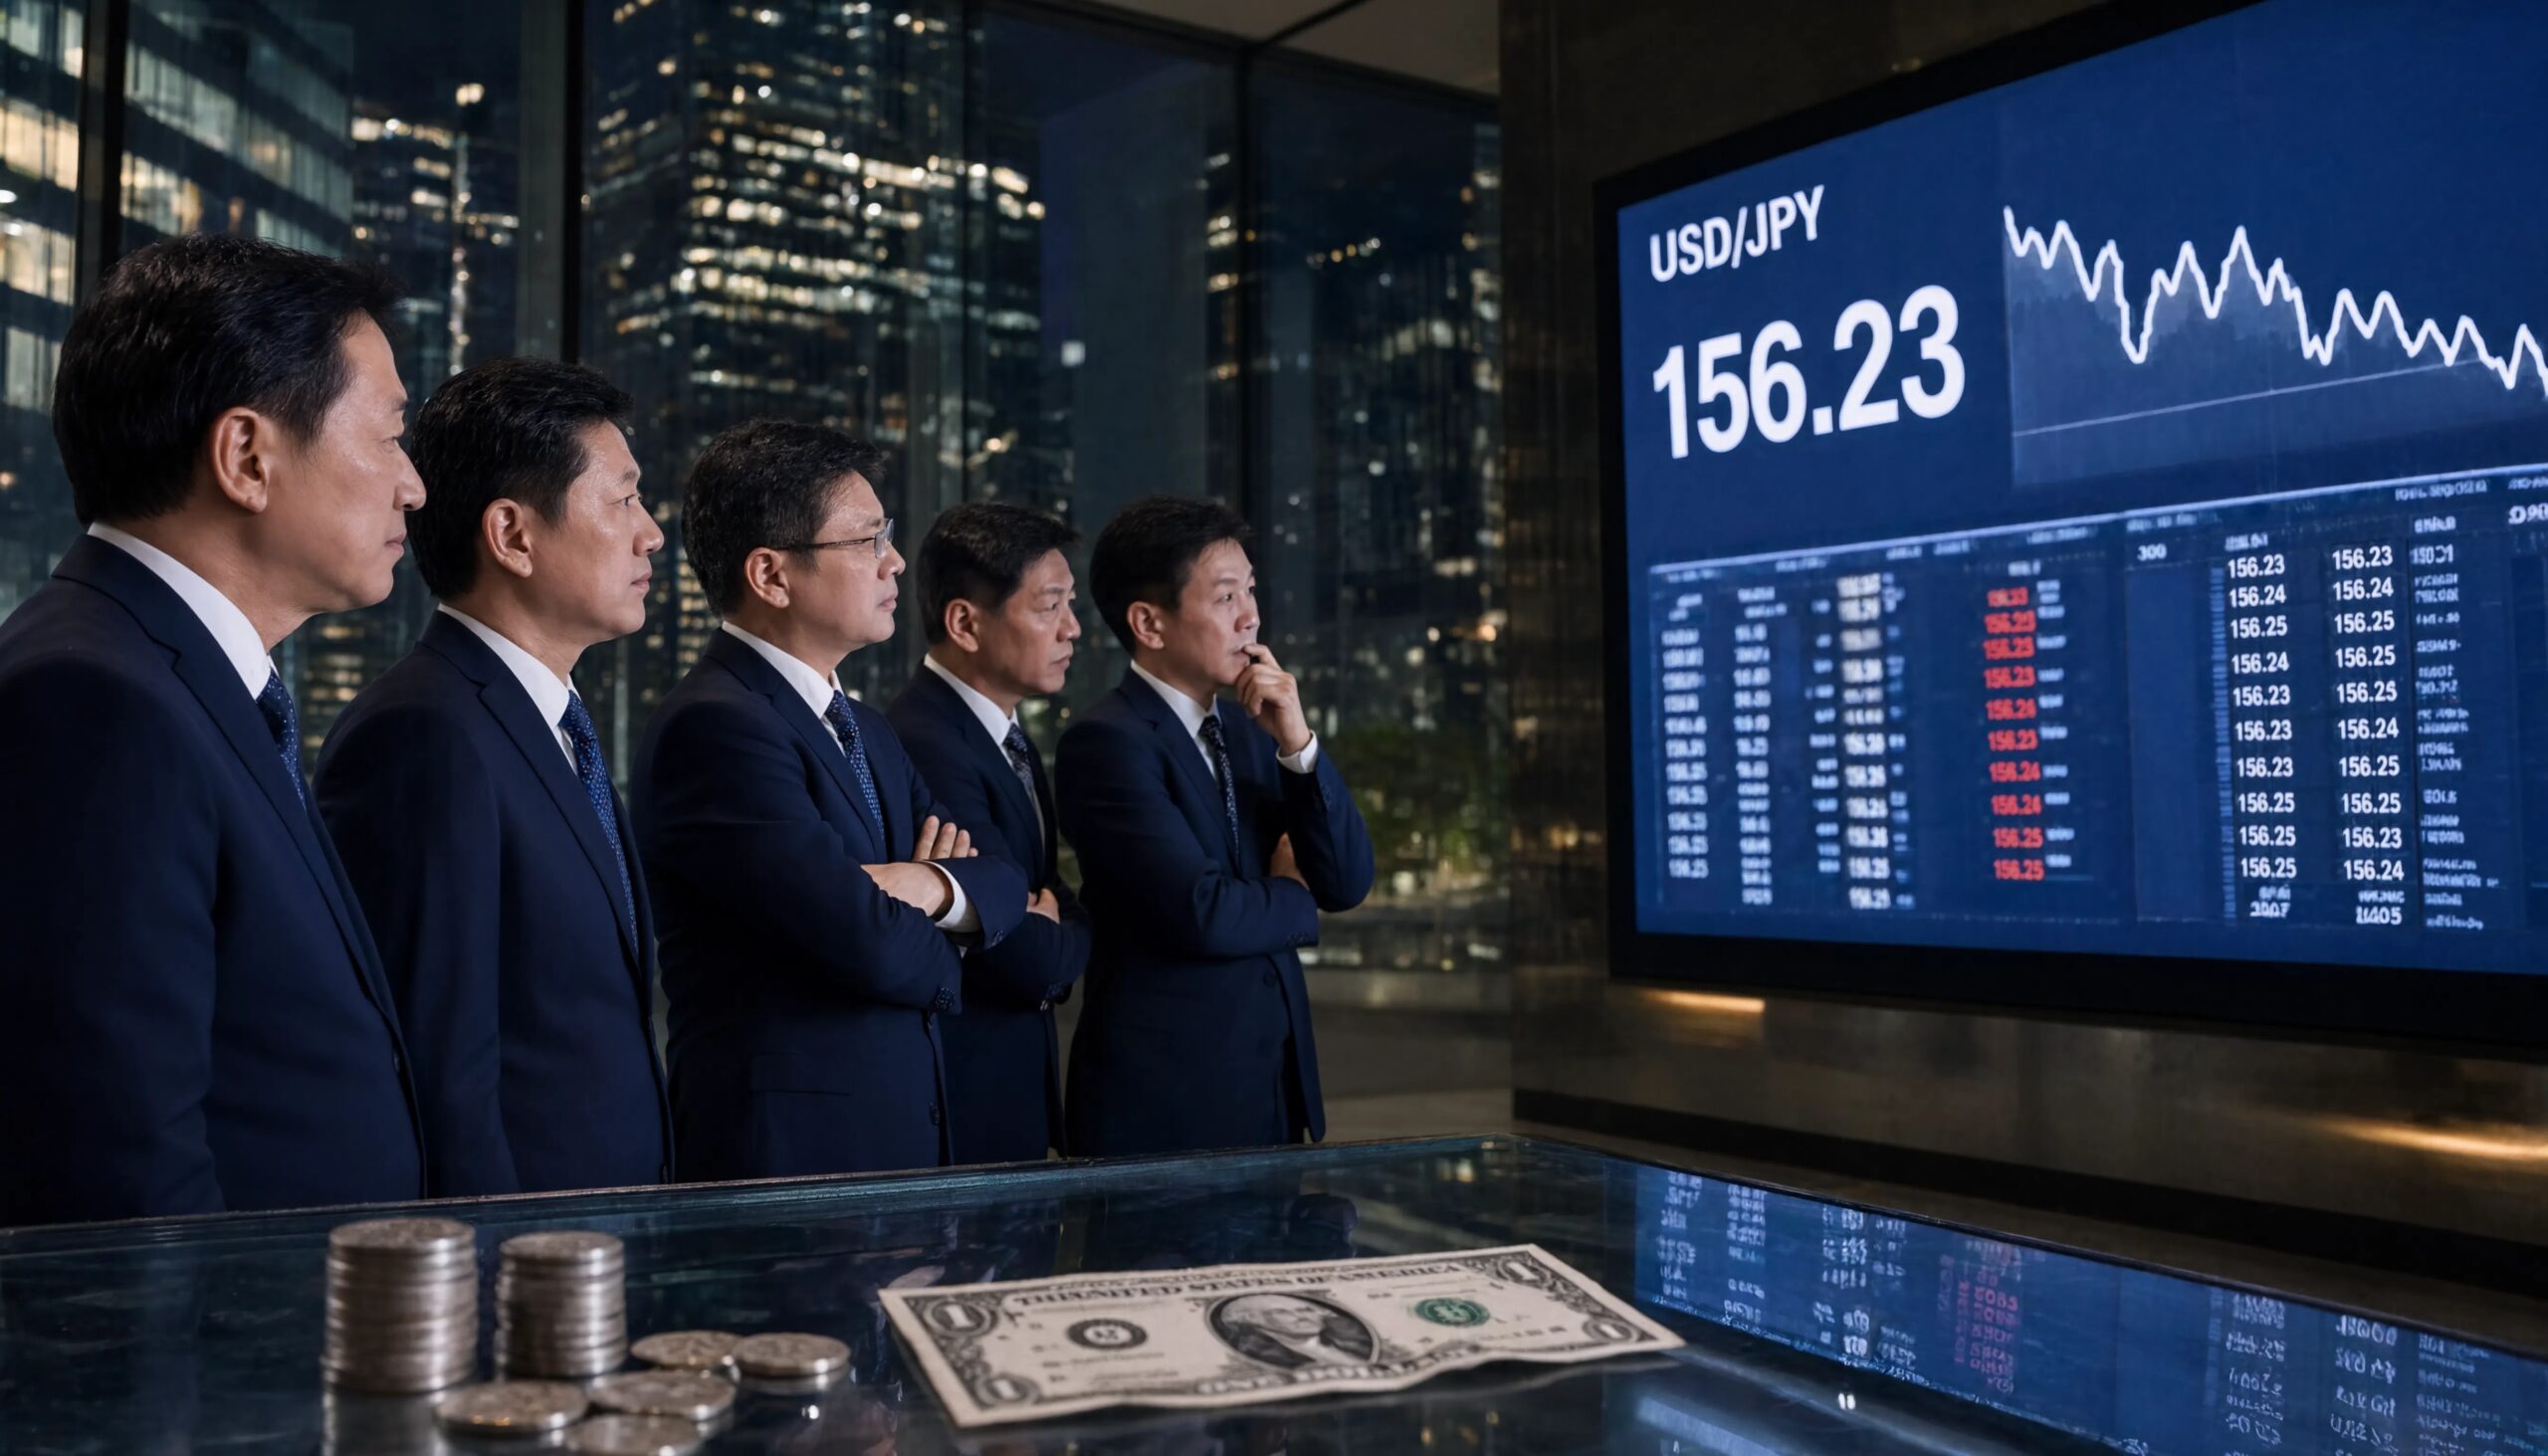
Let us put the chatter next to the tape. After a two-week bounce, the yen was still trading near 156. That is weaker than the long-run average near 123 over ten years. Companies themselves planned the second half of the year around an average of about 152.51, according to a quarterly business survey. Markets, in other words, have been living on the cheap side of what boards already baked in.
| Reference | Yen Per Dollar | What It Means |
| Ten-year average | About 123 | Historically much stronger yen |
| Corporate planning rate | About 152.51 | Assumed for the second half |
| Recent spot level | Around 156 | Still weak after a short rebound |
| Manufacturer trigger | Near 150 | Possible shift of plants back home |
| Energy chief “appropriate” | 100 | Far stronger than today’s market |
| Shipping comfort zone | 150 to 155 | Stability prized over extra weakness |
Look at that table twice. The “appropriate” level and the market level do not live on the same planet. That distance is why this story is not a simple exporters-versus-importers fight. It is a fight inside the same companies.
How A Cheap Currency Helps And Hurts At Once
A weak yen lifts reported profits for firms that earn abroad. It also raises the yen cost of oil, gas, food, and components. Households feel that at the pump and in the supermarket. Smaller manufacturers that buy parts overseas feel it in margins. Tourism inflows can rise, yes, but the same tourists spend in a country where locals are paying more for imported life.
- Dollar revenues convert into larger yen totals on the income statement.
- Imported energy and materials become more expensive in local currency.
- Wage talks get harder when workers watch prices climb faster than pay.
- Long-term plant decisions stall when no one trusts next year’s rate.
- Financial markets can turn jumpy if the move looks disorderly.
I’ve found that the last point is the one executives mention when they think cameras are off. They can live with a cheap yen. They hate a chaotic yen.
Rate Policy Sits In The Middle Of The Room
Investors have been leaning toward another quarter-point increase that would take the policy rate to 1.25 percent. The stakes are high. A hike plus hawkish language would tell markets that the tightening path is not a one-off. A hold would leave the yen looking orphaned again.
One market strategist put it without much poetry. The central bank is in a tight spot. Deliver the hike and sound serious about a quarterly cadence, and the currency can keep healing. Blink, and the old slide can resume. I tend to agree with the spirit of that call, even if I would not bet the house on any single meeting.
Why? Because currency markets price stories, not just dots on a path. The story right now mixes politics, fiscal caution after a leadership contest, equity strength, and a central bank that has spent years moving at a glacial pace. Change any one of those pieces and 156 can become 148 or 162 in a hurry.
What “Too Weak” Really Means For Strategy
When a chairman talks about pulling production home at 150, he is doing more than currency commentary. He is sketching a new industrial map. Overseas sites exist for customers, tariffs, skills, and supply-chain safety. A stronger yen can still justify those sites. A violently weak yen can make the home base look cheap again, at least on paper.
That does not mean factories pack up next month. Relocations take years. Permits, unions, suppliers, and customers all have a vote. Still, the signal matters. If boards start treating Japan as a cost-competitive manufacturing base again, capital budgets will tilt. Hiring will tilt. Regional economies that lost plants in earlier decades might get a second look.
Is that healthy? It depends what you want. A country that rebuilds domestic capacity can feel more secure. A country that chases every exchange-rate swing can waste money building and unbuilding the same lines. Balance is the unglamorous answer, and balance is exactly what these executives keep asking for.
The Household Side Nobody In A Suit Can Ignore
Corporate quotes grab headlines. Grocery receipts decide elections. A cheap yen makes imported life dearer. Energy is the loudest channel. Food is the quiet one that never leaves the conversation. Travel abroad becomes a luxury. Even domestic leisure can feel pinched if hotels chase foreign visitors with higher prices.
That is why an energy boss with dollar cash flows can still say 100 is “appropriate.” He is not running for office. He is admitting that the social license of a weak currency has limits. When households feel poorer, wage demands rise, and those wages feed back into costs for the same companies that loved the translation gain.
In my view, that loop is the real story. Currency is not a one-way gift. It is a transfer. Somebody pays.
How Boards Budget When The Rate Will Not Sit Still
Most large Japanese groups set an internal planning rate and then hedge around it. The midyear survey figure near 152.51 is that kind of number. If spot trades weaker than plan, finance teams book a pleasant surprise. If spot rips stronger, they eat a miss unless hedges were tight.
The trouble starts when the gap between plan and spot stays wide for quarters. Sales teams price deals off one assumption. Procurement teams buy parts off another. By the time the year closes, nobody is quite sure which number was “real.” That is how you get the complaint about strategy.
- Set a conservative internal rate that management can defend.
- Hedge a slice of expected dollar flows, not the entire dream pipeline.
- Revisit plant location only when the new rate looks durable, not fashionable.
- Talk to workers early if import inflation is about to hit wages.
- Keep a cash buffer for the week the market decides to overshoot.
None of that is glamorous. All of it is how grown-up companies survive a currency that refuses to behave.
Exporters Are Not A Single Tribe
People talk about “Japanese exporters” as if they share one spreadsheet. They do not. A carmaker with huge overseas plants lives a different life from a precision-parts shop that still stamps metal at home. A tanker owner lives a different life from a retailer that buys almost everything abroad.
That is why you now hear dollar-earners asking for strength. They already captured the easy translation win. What they want next is a country that can invest, hire, and buy energy without flinching. A currency that looks like a fire sale does not deliver that country.
I’ve sat in enough earnings calls to know the script. First five minutes: yen helped operating profit. Next twenty minutes: costs, wages, and the outlook. The second part is getting longer.
Politics, Fiscal Tone, And The Sudden Bid For The Yen
The recent bounce did not come from a single speech. Equities firmed. Markets started to price a more responsible fiscal stance after a leadership outcome. Currency traders, who had been leaning one way for months, had to cover. That mix can move a rate faster than any textbook model.
Will it last? Only if the follow-through is real. A stronger yen built on hope alone tends to fade. A stronger yen built on rate differentials, credible budgets, and cooler inflation can stick. Executives know the difference. That is why they talk about levels and also about stability in the same sentence.
A Plain-Language Guide To The Levels People Keep Citing
One hundred. One fifty. One fifty-five. One fifty-six. These are not magic. They are shorthand for different worlds.
Near 100, Japan looks expensive again to foreign buyers of goods and cheap to Japanese travelers. Near 150, some industrial groups start to rethink the map of plants. Near 155 to 158, dollar earners enjoy the conversion, and households quietly pay more for the imported slice of life. Above that, the conversation turns from “helpful” to “too far,” which is where we are.
Simple way to remember the debate:
  100  = “right for the country,” say some chiefs
  150  = possible homecoming for certain factories
  152  = what many boards already budgeted
  155  = comfort zone for a major shipper
  156+ = still weak after the latest bounce
Keep that scrap of paper in your head when the next print hits the screen. You will hear the same numbers again.
What Investors Should Watch Without Overreacting
Do not treat every executive quote as a trading signal. Do treat the pattern. When even the winners of a cheap currency ask for strength, the political and social limit is closer than the chart suggests. Policy makers hear those voices. So do wage negotiators.
Watch three things. First, the policy meeting and the tone around the pace of hikes. Second, whether fiscal talk stays cautious or slides back into stimulus-as-habit. Third, whether import prices keep leaking into core inflation. That trio will do more to set the yen than any single interview.
And if you own exporters, remember the two-speed reality. A firmer yen can clip translation gains while helping the domestic customer. A weaker yen can juice reported earnings while squeezing the same customer. There is no free lunch hiding in USD/JPY.
A Few Honest Opinions After Years Of Watching This Pair
I do not think 100 is coming back soon. That would require a shock in rate gaps or a crisis elsewhere. I do think the idea of “the weaker, the better” is exhausted. Too many boards have said so out loud.
I also think stability beats a heroic rebound. Companies can plan around 150. They struggle to plan around a fifty-handle range that changes every other month. If policymakers deliver a dull, stronger, less dramatic yen, that may be the win corporate Japan actually wants.
Is that exciting for traders? Not really. Exciting and useful are different jobs.
The Human Texture Behind The Quotes
These comments came from the edges of an energy conference, not from a scripted results call. That matters. People speak more freely in a corridor than they do on a webcast. When three different chairs and chiefs, in different industries, rhyme with each other, you should listen.
One wants plants at home if 150 arrives. One wants 100 for the nation even while his firm banks dollars. One wants a calm 150 to 155 and no circus in funding markets. Different wish lists. Same diagnosis. The currency has overshot the comfort of the real economy.
A weak currency can pad a quarter. A trusted currency builds a decade.
That line is mine, not theirs. I stand by it.
What Happens If The Yen Keeps Healing
If the bounce extends, expect mixed earnings revisions. Translation gains shrink. Import costs ease with a lag. Some manufacturers reopen the home-production file. Equity investors will argue in public about which effect wins. Both can be true at once for different sectors.
If the bounce fades, expect the same executives to repeat themselves with less patience. The “too weak” chorus gets louder when the chart goes the wrong way after a false dawn. That is usually when policy talk hardens.
Either path, the old story that Japanese business uniformly loves a cheap yen is finished. The new story is messier and, frankly, more adult.
Practical Takeaways If You Follow This Market For A Living
- Separate company-level dollar profits from economy-wide welfare. Leaders are already doing that.
- Treat 150 as a psychological line for industrial location talk, not a law of physics.
- Respect the planning rate near 152. Boards live there even when spot does not.
- Do not ignore households. Their import bill is the political constraint.
- Price the next policy meeting as a tone event, not only a 25-basis-point event.
None of these points require a crystal ball. They require reading what executives said and taking them at their word.
Closing Thoughts Without A Ribbon On Top
So here we are. A currency that helped a generation of exporters is now being scolded by some of those same exporters. The yen has bounced and remains historically cheap. Factories might come home if 150 sticks. An oil chief still dreams of 100. A shipper just wants the noise to stop.
Will policymakers deliver the calmer, somewhat stronger rate that boards keep describing? Maybe. The next meeting will tell us more than any corridor interview. Until then, the honest summary is simple. The weak yen still pays some income statements. It is no longer winning the argument about what Japan needs.
And if you were waiting for corporate Japan to celebrate every last tick of depreciation, you can stop waiting. That party ran out of ice.