

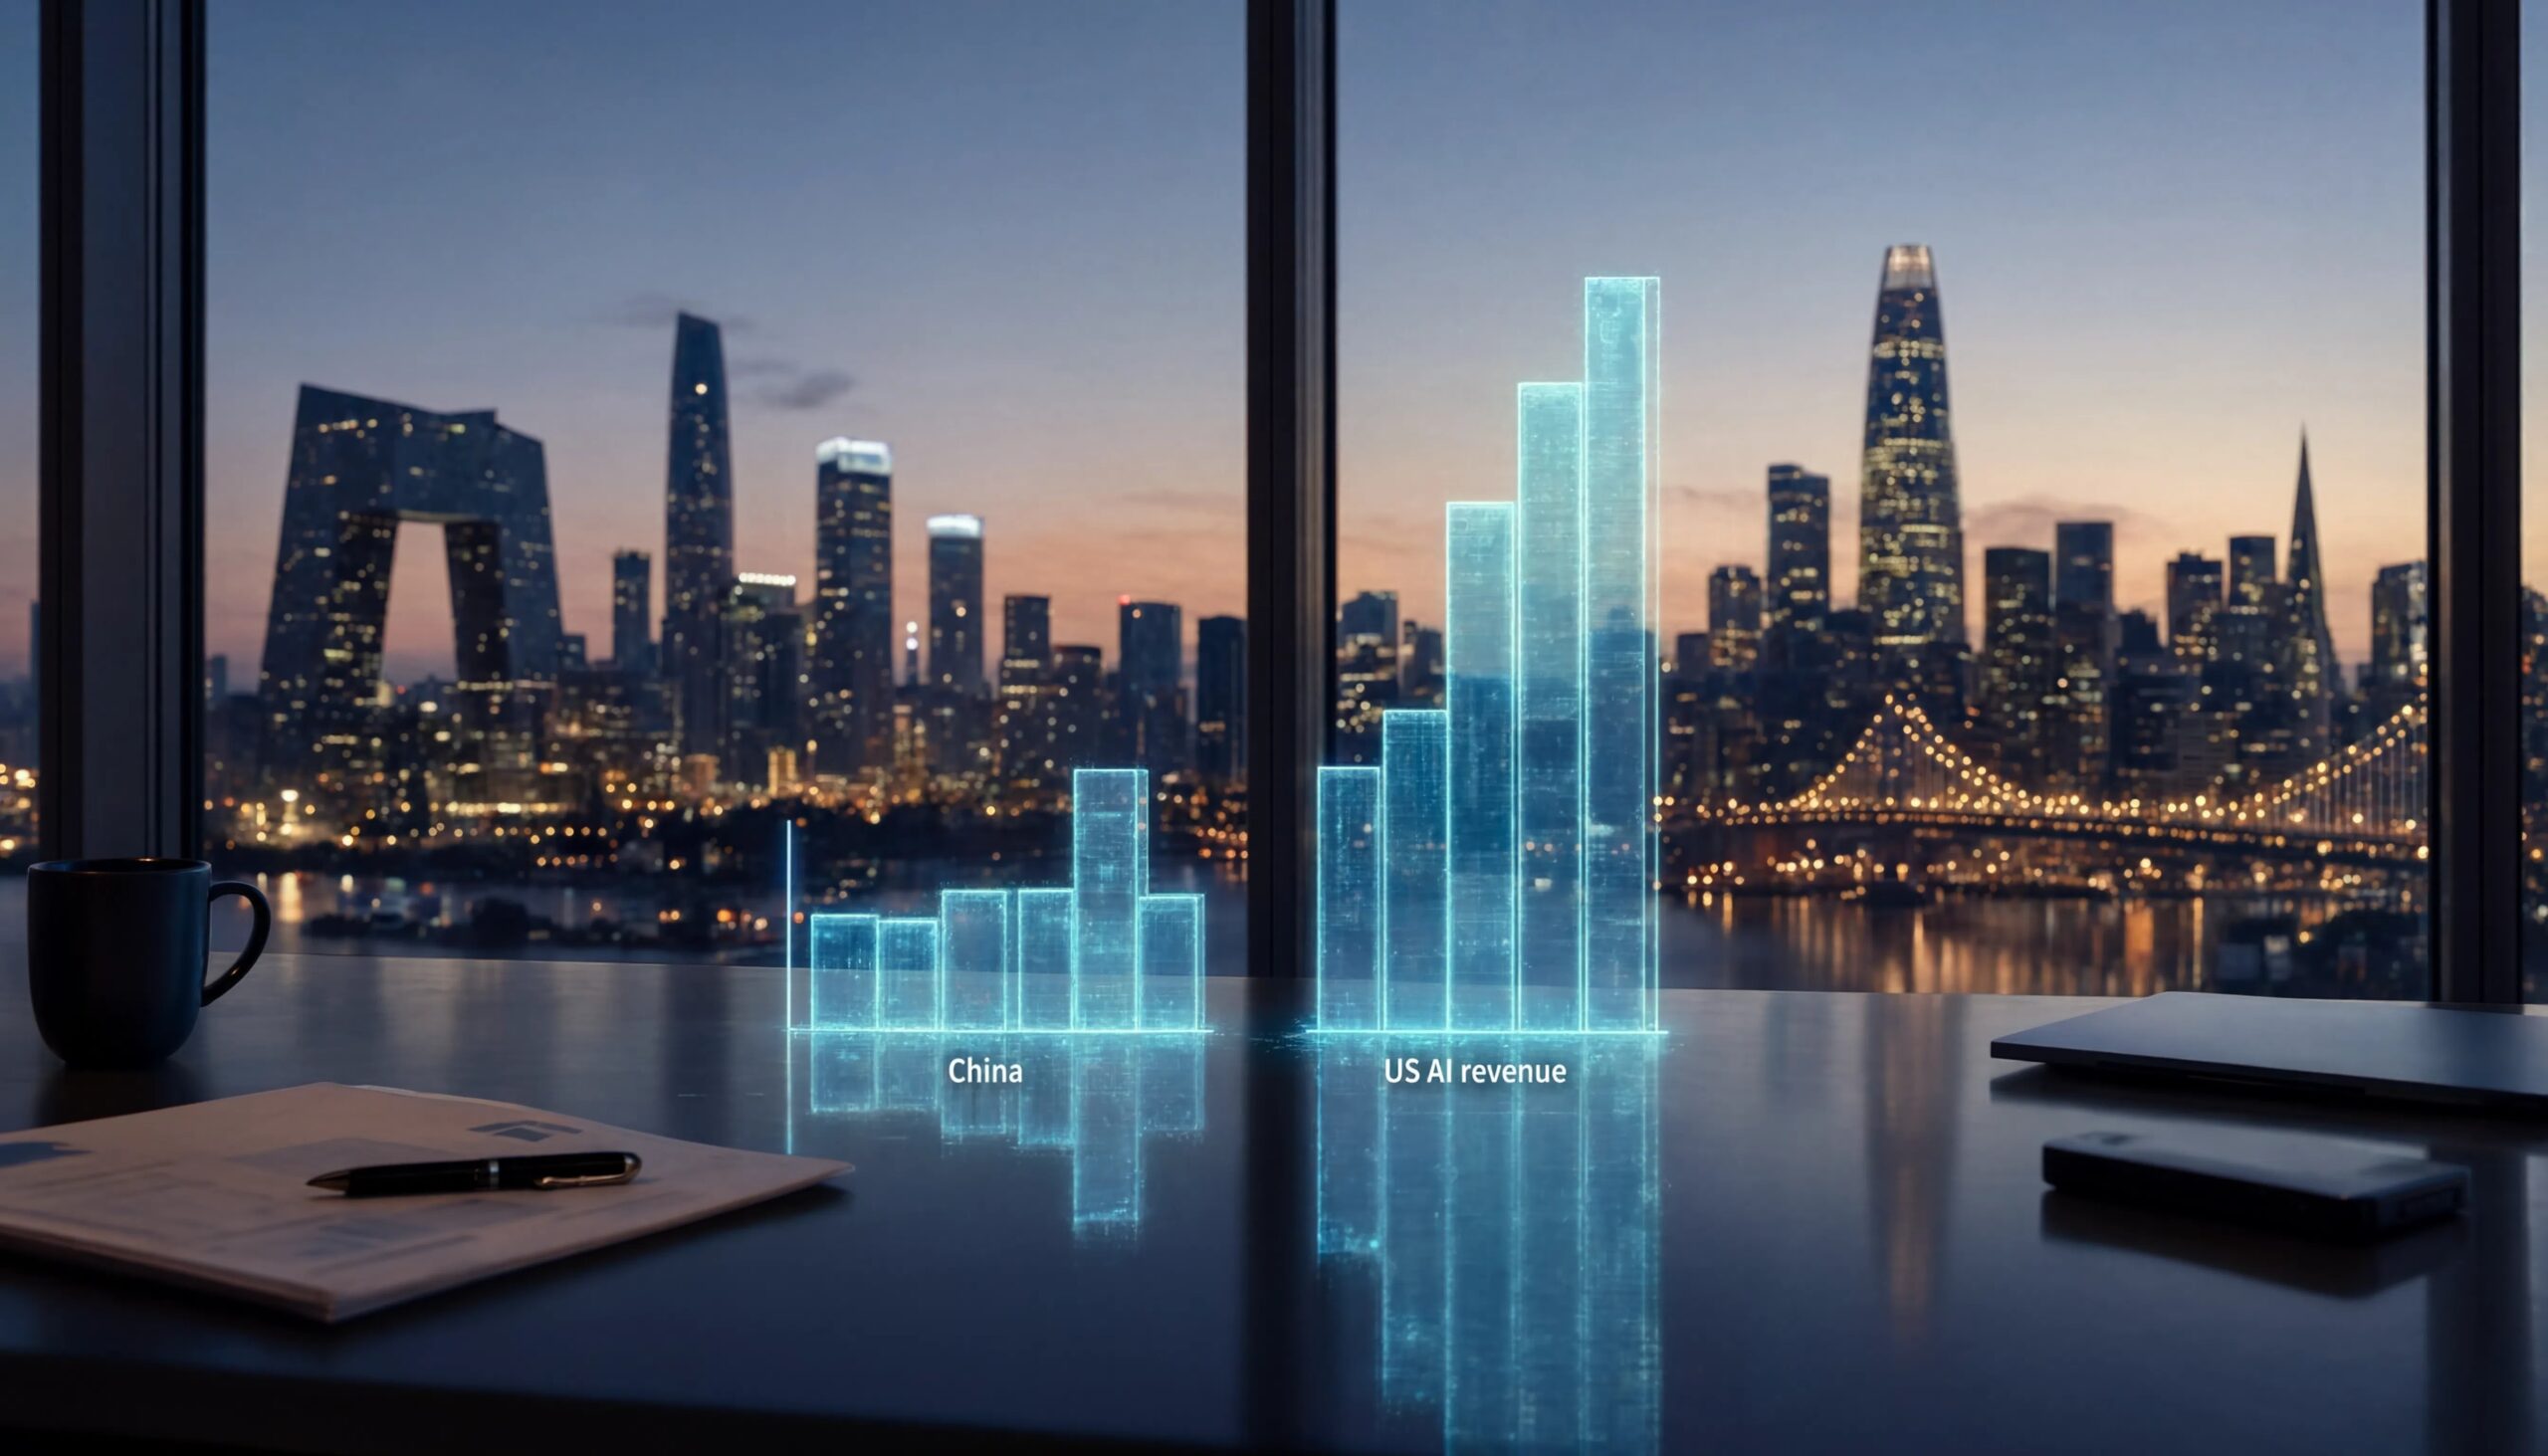

I keep hearing the same line in meetings: Chinese models are catching up so fast that revenue must be exploding too. Then someone slides a napkin estimate across the table and the room goes quiet. Combined, the big Chinese model shops appear to pull in only about a tenth of what two American leaders already book. That is not a rounding error. That is a different business.
Why Chinese AI Revenue Still Lags US Labs
Adoption can look electric while cash stays thin. That is the awkward split sitting under this market. Usage of domestic models jumped from a low base earlier this year. Screenshots travel. Benchmarks travel. Invoices travel much more slowly. I have found that people confuse traffic with take rate. They are not the same animal.
A U.S. research group recently tried to put numbers on that gap using annual recurring revenue, or ARR. The method is blunt: take a recent monthly run-rate and multiply by twelve. It flatters fast growers. It also makes comparisons possible when audited books are still scarce. On that yardstick, the whole Chinese model stack still sits near one-tenth of the combined haul reported for the two best-known American labs.
Valuations relative to revenue appear exorbitant for several private Chinese labs at present.
– Industry research note
Perhaps the most interesting part is not the headline ratio. It is how uneven the local pack looks once you stop treating “China AI” as one blob.
The ARR Scoreboard Nobody Wanted On A Slide
One widely cited private lab sat near half a billion dollars of ARR. Another came in around eight hundred million. A third was pegged near a billion. A listed name told investors its latest ARR was about one point eight billion, then raised the year-end target toward three billion. Two internet giants added more weight: one estimate put a short-video group near four billion and a cloud-and-commerce giant near two point four billion.
Add those pieces and you still do not approach the American pair. One U.S. lab was described near forty billion. The other, near sixty-five. Yes, those figures are also ARR-style snapshots, not cash sitting in a vault. Still, order of magnitude matters. Ten times is not a vibes problem. It is a unit-economics problem.
| Player cluster | Indicative ARR | Rough valuation multiple |
| Smaller Chinese labs | $0.5B–$1.0B | Very high vs peers |
| Listed or larger Chinese names | $1.8B–$4.0B | Mixed, still rich |
| Two leading U.S. labs | $40B and $65B | Lower than several Chinese peers |
I am not pretending these are audited line items. They are directional. Direction still counts when bankers start whispering about Hong Kong filings and U.S. listings.
Price Per Task Is Doing A Lot Of Quiet Work
American flagship models are mostly closed. You rent the brain. You pay for the token. Chinese models, by contrast, often ship weights that a well-equipped shop can run on its own iron. That is great for adoption. It is lousy for capturing the last dollar.
Comparison shops that track cost per task keep saying the same thing: leading U.S. models cost more per job. Sometimes a lot more. If your product is cheaper and easier to self-host, you win users and lose margin. I have watched this movie in cloud before. Open cores build ecosystems. Closed cores build invoices.
Does that mean Chinese labs chose poorly? Not necessarily. Open weights helped them punch through export controls, talent bottlenecks, and brand skepticism. The trade-off shows up later, when investors ask who actually owns the meter.
- Closed U.S. models keep a thicker slice of each completed task.
- Open Chinese models spread usage across third-party hosts and private clusters.
- Hardware owners capture value that model authors never see.
- Enterprises bargain harder when a substitute can be downloaded.
Labs know this. They are poking at revenue shares with wrappers, app stores, and API partners. Fine. Negotiating a cut after the ecosystem already learned to run the model without you is a tougher conversation than launching closed from day one.
Valuation Math That Makes Bankers Flinch
Here is where the story stops being a tech debate and becomes a market debate. Estimated revenue multiples for two private Chinese names were described around fifty times and more than one hundred sixty times. The American pair sat closer to the mid-thirties and the low twenties on the same rough framework.
In my experience, a sky-high multiple can be justified for a few quarters if the slope of revenue is nearly vertical and the product is scarce. Scarcity is the missing piece. When weights leak into every GPU closet, scarcity fades. Slope can still be steep. The multiple should not pretend the product is a gated utility.
One listed Chinese AI name popped more than five percent in morning trade after a messy week, then settled back toward levels last seen in spring. It had more than tripled during a summer squeeze before giving a chunk back. A rival that listed earlier has struggled to hold the first-day pop. That is not unique to this sector. It is a reminder that listed China tech still trades like a mood ring.
Listings On The Calendar, Cash Still On The Wish List
Rumors have one private Chinese lab filing confidentially in Hong Kong. Another is said to be preparing papers. Across the Pacific, one American lab is widely expected to list soon; the other has pushed talk of a public debut into next year. None of that changes the revenue stack overnight. It does change who gets to mark the paper.
When asked about a confidential filing, one lab said it does not comment on market rumors. Fair. Markets will comment anyway. Equity windows in China have a habit of slamming shut when global risk appetite sneezes. A financing gap is not a slogan. It is a constraint on how many training runs you can fund without diluting into a sour tape.
The financing gap means it will be far more difficult for Chinese frontier labs to scale sustainably. They will be heavily dependent upon a favorable climate in the equity market.
– Research partner comment
That line stuck with me. Hardware buildout has seen plenty of state-linked capital. Chip and server money is easier to dress up as industrial policy. Writing checks straight into a frontier lab that might never throw off cash is a different political animal. Analysts put more than sixty percent of equity investment in Chinese AI chips and servers with state-affiliated sources. Helpful for racks. Less helpful for model-shop working capital if public markets sulk.
Open Weights, Thin Wallets, And The Third-Party Problem
Think of the model as a recipe. If anyone with a kitchen can cook it, the chef needs a restaurant, a spice brand, or a ticketed show. Chinese labs are hunting all three. Some want a bigger cut from companies that wrap their models in chat apps and agent tools. Some want cloud credits bundled so the default path still hits their meter. Some want enterprise contracts that look closed even if the base weights are not.
Will it work? Maybe in patches. Enterprises like support, indemnity, and a throat to choke. Those are billable. Hobbyists and cost-cutting startups will keep running local copies. That split is healthy for national capability. It is messy for a venture deck that assumed software-like margins.
- Ship a capable open model and flood the zone with users.
- Watch hosts and integrators capture distribution.
- Return later asking for a revenue share.
- Discover that leverage peaked on launch day.
I do not say that to dunk on the strategy. It was rational under chip constraints and talent wars. I say it because investors sometimes price the first step and forget steps three and four exist.
What The Usage Boom Does — And Does Not — Fix
To be fair, the snapshot many analysts used came from summer prints. Usage has climbed since. One listed lab lifted its year-end ARR target from about two point four billion toward three billion. That is real acceleration. It is still not forty billion.
Growth from a small base always looks heroic on a percentage chart. Dollar charts are less kind. If American labs keep expanding enterprise seats at premium prices while Chinese labs add free and cheap seats, the ratio can stay ugly even as local products get better every month.
Is quality the issue? Not in the way casual commentators claim. On a lot of everyday tasks the gap has narrowed. Price and packaging are doing more work than raw eloquence. When a job costs a fraction as much, buyers flood in. When those buyers can also self-host, the developer’s top line does not flood in with them.
Why State Money Loves Silicon More Than Softmax
Industrial policy likes objects you can count. Racks. Wafers. Megawatts. A frontier lab is a payroll, a cluster reservation, and a research culture that might miss the next architecture bet. Governments will fund the shell. They hesitate on the ghost.
That does not mean labs are abandoned. It means the cheap capital sits one layer down the stack. If you make servers, you can point to localization goals. If you make a chatbot that enterprises refuse to pay American prices for, you look like a consumer internet company wearing a lab coat. Consumer internet multiples in that market have already been through the wringer.
Simple way to see the stack:
  Chips and servers — heavy state-linked equity
  Power and data centers — mixed industrial support
  Frontier labs — more dependent on private and public equity mood
  Apps on top — crowded, price-sensitive, hard to defend
If you are allocating capital, that map matters more than another demo video.
American Caution And A Quiet Chinese Pause
U.S. tech stocks wobbled after senior figures at major American AI firms warned about moving too fast. Safety talk, capex talk, bubble talk — pick your flavor. Chinese lab leaders have not rushed out matching sermons. Maybe they do not need to. Their constraint is less “are we building too much intelligence” and more “who pays for the next run.”
Different fear, same market. When Western multiples compress, risk appetite for rich China stories compresses with them. Correlation shows up late and all at once. I have seen that pattern enough times to stop calling it a coincidence.
How I Read The Investor Checklist From Here
Forget the mythology for a minute. A practical sheet looks like this.
- Is revenue coming from metered APIs or from brand halo and one-off projects?
- Can the lab claw back value from third parties already hosting the weights?
- What share of compute is prepaid versus rented on hope?
- Does the listing venue tolerate long winters, or only summer narratives?
- Are multiples priced for closed-model economics while the product is open?
If those answers stay fuzzy, a fifty-times or one-hundred-sixty-times story is not bold. It is lazy. Markets sometimes pay laziness for a quarter. They rarely refinance it.
None of this requires assuming Chinese research is weak. Capability and monetization have decoupled before — think browsers, think messaging, think plenty of open infrastructure. The country can still field excellent models and still struggle to mint American-style software profits. Those two sentences can be true on the same Tuesday.
A Few Scenarios, None Of Them Magical
Scenario one: enterprise wrappers work. Labs lock support contracts, raise prices on hosted endpoints, and live with a noisy open-source fringe. Multiples compress toward something adult, but revenue climbs fast enough that paper values hold.
Scenario two: self-hosting wins. The model becomes a commodity ingredient. Value piles up in chips, clouds, and vertical software. Labs look like research institutes with a merch table. Listings still happen. After-market performance does not.
Scenario three: a closed successor appears. A lab ships a model it will not fully release, prices it like the Americans, and prays the user base follows. Possible. Politically and commercially harder than fans admit.
I lean toward a blend of one and two. Messy. Uneven. A handful of names find a paid wedge. Most do not. That is a market, not a morality play.
What This Means If You Already Own The Story
If you hold the listed names, stop treating every download spike as earnings. Watch guided ARR against realized billings. Watch gross margin language, not just user counts. Watch whether management talks about take rates or only about “ecosystem.” Ecosystem is a lovely word. It does not pay the cluster bill.
If you are in private rounds, ask who sits above you in the preference stack when the Hong Kong window closes for six months. Ask how many months of training the last raise actually bought. Ask what happens if the American pair cut prices. Cheap U.S. inference would squeeze the one advantage many local models still advertise.
If you are on the sidelines, you do not need to pick a civilization. You need to pick a cash-conversion path. The last cycle taught a simple lesson: narrative premium dies when rates stay high and buyers get picky. This cycle added a twist. The product can be good and still refuse to throw off American cash.
The Uncomfortable Middle Ground
So where does that leave a reader who just wanted a clean scoreboard? Roughly here. Chinese models are in the wild. They are cheaper. They are widely copied. They are not, on present evidence, minting anything like the recurring revenue of the two American shops that dominate the conversation in New York and San Francisco.
Valuations in a few private cases look stretched against that revenue. State money is real on hardware and thinner on the labs themselves. Listings may arrive anyway because windows open when they open, not when unit economics graduate.
I keep coming back to a plain question. If the model is free to run, what exactly is the customer paying for? Until that answer is boring and specific — support, latency, compliance, bundled data, a closed successor — the revenue gap is not a mystery. It is the business model doing what open systems usually do.
That is not a eulogy. It is a filter. Use it the next time a slide claims the race is already over because a demo looked sharp. Demos are cheap. Recurring invoices are not. And right now, those invoices still cluster on one side of the Pacific.



