
Have you noticed how every conversation about artificial intelligence eventually slams into the same unglamorous wall? Not model size. Not power bills. People. The United States is pouring concrete and installing tools faster than it can find technicians who know how to keep a fab alive at three in the morning. I’ve been watching this gap widen for a while, and the latest numbers still catch me off guard: a shortfall that could reach 157,000 skilled semiconductor workers by 2030. That is not a rounding error. That is a bottleneck with a name badge missing.
Why The Chip Labor Shortage Suddenly Matters
America still designs many of the world’s most valuable chips. Manufacturing the advanced stuff, though, drifted to Asia for decades. Talent followed the tools. Now the country is trying to pull production home at a sprint, and the human pipeline did not get the memo. Only a sliver of new engineering graduates walk into semiconductor roles each year. Most employers in the sector say they struggle to fill those seats. You can feel the tightness in every groundbreaking speech.
This is not abstract policy talk. New logic plants are coming online in Arizona. A major Korean manufacturer is preparing advanced logic production in Texas later this year as part of a multi-tens-of-billions buildout expected to create thousands of jobs. Memory capacity is racing to catch an AI-driven crunch. Every one of those tools needs people who can run, repair, and improve them. I’ve found that executives sound almost identical when they describe the problem: everyone wants the same scarce profile at the same moment.
We just don’t see that there’s enough technical people in the pipeline.
– A senior semiconductor operations leader in Texas
That sentence is blunt on purpose. Concern is no longer whispered in closed-door briefings. It is the operating assumption.
The Math Behind 157,000 Missing Workers
Industry research circulating this year puts the United States on a path toward a six-figure gap by the end of the decade if training and hiring stay on their current slope. Engineering roles are the loudest pain point. Technicians sit right behind them. Supply-chain specialists, equipment engineers, and process experts get pulled into the same scramble. When 73 percent of chip employers report serious trouble filling engineering jobs, you do not need a fancy model to see the constraint.
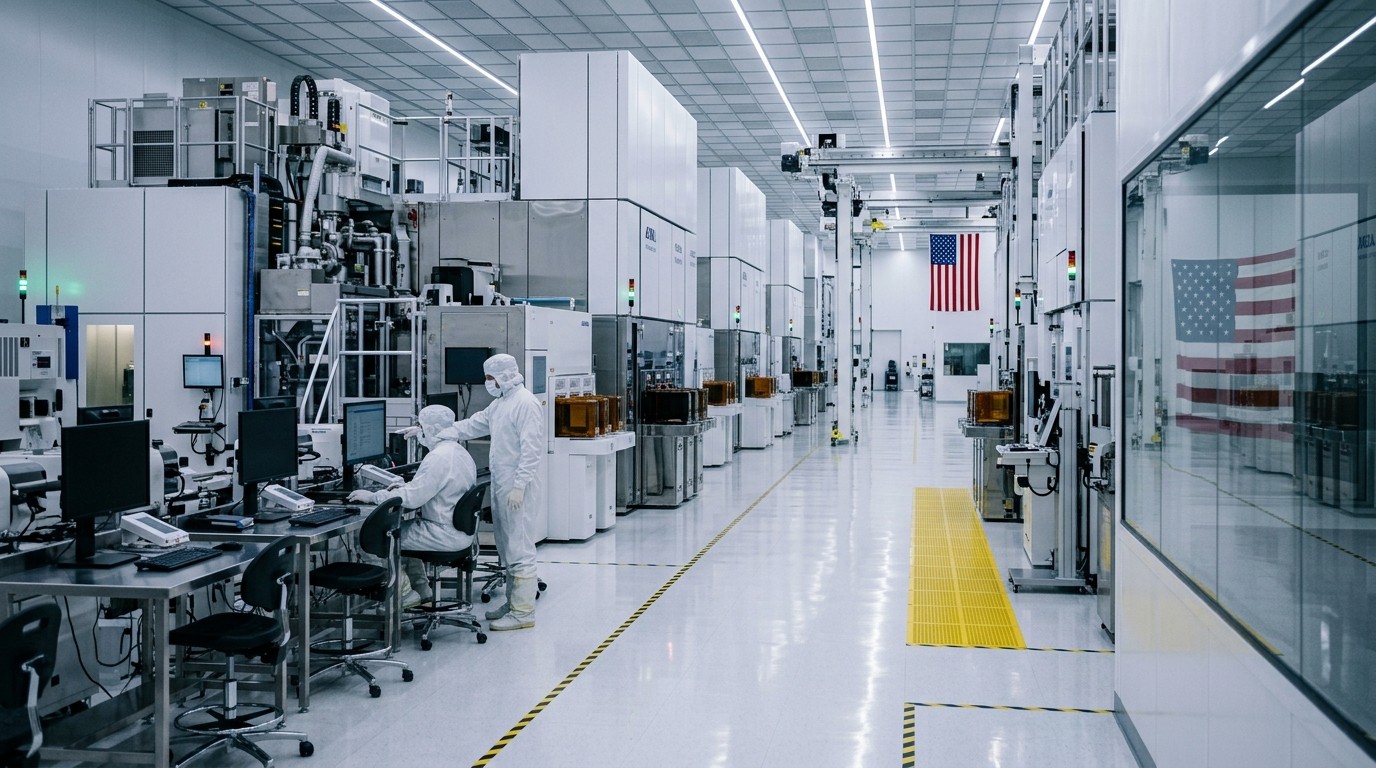
Think about what a modern factory actually consumes. Not just wafers. Shifts. Overlap. Cross-training. A tool set that costs more than some office towers cannot sit idle because one person called in sick and nobody else is qualified. Scale that across multiple new sites opening in a tight window and the arithmetic gets ugly fast.
Perhaps the most interesting aspect is how little of this is about “not enough college kids.” Plenty of students still chase engineering. They just do not choose semiconductors. Software looked shinier for years. Now software hiring itself looks shaky in places, which might finally push more talent toward hardware. Might. Pipelines do not flip overnight.
Asia Still Owns The Deepest Talent Bench
Walk the hiring map and the contrast is obvious. Universities in Taiwan and South Korea treat semiconductor work as a serious professional track, not a niche elective. Companies interview on campus and close offers in a single intense day. An Idaho-based memory maker has run those expedited sprees in South Korea, talking to students and locking permanent roles at Asian plants before the sun goes down. That is not a gimmick. That is how a mature ecosystem behaves.
Pay and status travel with that ecosystem. In parts of South Korea, chip jobs carry social weight that sounds almost old-fashioned to American ears. Long shifts are common. When large groups of workers at major memory firms threatened walkouts, retention packages swelled into territory that would make a U.S. recruiter blink: bonuses that, in extreme cases, climbed toward the mid six figures. Compare that with typical domestic ranges often cited between roughly $127,000 and $187,000, with senior seats clearing $238,000. Those U.S. numbers are not low. They also are not always winning the global auction.
In my experience, money is only half the story. Prestige, speed of promotion, and the feeling that the whole country is watching the industry matter too. The United States is trying to rebuild that cultural gravity from a standing start.
New Fabs, Same Hiring Race
Arizona is no longer a rumor. Advanced logic is leaving those buildings. Texas is next in line for another wave of leading-edge production. Idaho and New York are on the memory calendar. Indiana is getting a packaging site tied to a Korean memory giant. Ohio remains a long construction story with a hungry future headcount. Stack those projects and you get a nationwide bidding war for a thin slice of specialists.
Leaders on the ground talk about hiring engineers, technicians, and supply-chain staff in the same breath. They also talk about time. Tools arrive. Buildings get certified. Then the clock starts on yield. Yield is a people problem dressed up as a process problem. If you have ever watched a ramp, you know the first months are a negotiation between equipment and human judgment.
- Logic plants in the Southwest need experienced process talent now, not in 2029.
- Memory sites in the interior need operators who have seen high-volume DRAM reality.
- Packaging lines still compete for the same inspection and yield skill set.
- Equipment vendors need field engineers who can live near more than one customer campus.
Everybody wants the same thing. That phrase keeps coming back because it is true. It is also why temporary transfers from Asia have become standard opening moves. Korean staff fly in to start tools Americans have not lived with yet. U.S. employees fly the other direction for months of hands-on training. A European lithography leader even stood up a domestic training center to shorten that loop. None of this is cheap. All of it is faster than waiting for a brand-new graduate to grow into a night-shift owner.
Memory Plants Feel The Pinch First
Logic gets the glamorous headlines. Memory is where the shortage of people collides with a shortage of bits. AI servers eat high-bandwidth memory like it is free candy. Graphics companies and accelerator designers have been scrambling for supply. That pressure shows up as new campuses in South Korea, new U.S. shells in Idaho and New York, and a packaging play in Indiana. Two memory giants will soon fish in the same small American pond.
One executive put it simply at a Midwestern groundbreaking: securing high-quality local employees within a few years is the critical issue. Not the steel. Not the incentives. The people. There has even been talk of leasing space inside another company’s U.S. facility so memory can be made on American soil sooner. Whether that deal lands or not, the intent is obvious. Capacity is moving. Headcount has to move with it.
Commerce officials have publicly nudged Korean memory leaders to consider full front-end manufacturing in the United States, not just packaging. Plant managers on the American side shrug at the politics and point at the roster. Logic or memory, the staffing math does not get kinder.
Visas Will Not Save The Decade
Bringing experienced foreign talent on specialty visas sounds like the obvious patch. In practice it has become slower, pricier, and politically noisier. Companies still do it because they must. They also say, almost in unison, that the long game has to be domestic. You cannot run a strategic industry on a revolving door of temporary assignments and lottery-season anxiety.
That is why the training story matters more than any single plant photo. If the United States cannot mint its own process engineers and equipment techs, every new ribbon-cutting is a promise the labor market may not keep.
Universities Are Finally Building Real Chip Tracks
A handful of schools decided not to wait. One large Midwestern university launched dedicated semiconductor degrees in 2022 and now runs thousands of students through chip-related courses each semester. Its nanotechnology center puts those students on tools that look uncomfortably close to what they will see on a neighboring factory floor. Job fairs there get overbooked. That is a good problem. It is still a local problem until the model spreads.
A major Arizona university converted an old industrial cleanroom into a teaching fab and landed a nine-figure equipment-maker partnership for a new center. A leading foundry runs a technician program on that campus and sweetens completion with a guaranteed interview. Recruiters from that company hit about a dozen schools last year and plan to convert a large intern class into full roles across several Arizona plants that together need thousands of people.
I’ve walked enough campuses to know the difference between a renamed elective and a real pipeline. The second one smells like photoresist and sounds like vacuum pumps. Students who have touched a tool interview differently. Hiring managers notice.
If you want young people specifically prepared in semiconductors, this is the one place you can come right now for people who have actually majored in and achieved a degree in that.
– A university leader in Indiana
Companies Are Writing Checks Into Classrooms
Chipmakers are not waiting for public systems to catch up on their own. One logic player started Arizona apprenticeships in 2024, parked tens of millions in scholarships across dozens of Ohio schools near a future fab, and rolled out a broader education path that starts in K-12. Another manufacturer began a workforce program in 2023 with multi-million donations to flagship universities in Texas and Illinois, plus a high-school lab gift in the town that will host its new plants. Intern classes already top a hundred people a year at that site alone.
Federal money helps at the two-year college layer. Since the major domestic manufacturing law passed in 2022, more than 80 community colleges have launched or expanded semiconductor programs, aided in part by a dedicated workforce fund. That is the unsexy middle of the market: maintenance techs, operators, inspectors. Fabs collapse without them.
- Donate tools and curriculum so students touch real equipment before graduation.
- Guarantee interviews or internships so the path feels less abstract.
- Start earlier than college, because identity forms in high school labs.
- Keep paying competitive wages as the ramp steepens, or the pipeline leaks to other industries.
A university president near one of the new memory projects put the stakes without poetry. Move faster than before or lose. The country cannot afford that line on its record. Harsh? Sure. Also hard to argue with if you care about where advanced manufacturing actually happens.
Pay Will Have To Climb, And Culture Will Have To Shift
Here is the part recruiters whisper and presidents say out loud: as skills deepen, salaries have to follow. Scaling five sites at once is not a cost-plus spreadsheet exercise. It is a market. If software cooling sends more graduates toward hardware, great. If those graduates still see night shifts and bunny suits as a downgrade, the gap stays.
U.S. compensation is already solid for senior process roles. It looks less magnetic next to crisis-era Asian bonuses and a social status that treats chip work like a national project. I do not think America needs to copy twelve-hour martyrdom to compete. I do think it needs to talk about these jobs the way it talks about aerospace or energy: difficult, prestigious, and worth a life’s craft.
| Role Cluster | Why Demand Is Spiking | Typical Pressure Point |
| Process engineers | New nodes and yield ramps | Experience, not just degrees |
| Equipment technicians | Tool density in new fabs | Night coverage and cross-training |
| Memory specialists | AI-driven bit demand | Tiny U.S. talent pool |
| Supply-chain staff | Multi-site buildouts | Competition across all chipmakers |
What This Means For Students And Career Switchers
If you are a student staring at a shaky software market, this is one of the few industrial stories still hiring like it means it. The work is physical in a clean, ritualized way. It rewards patience more than slide decks. It also sits at the center of every AI pitch you have heard this year. Chips are not a side quest. They are the board.
Community college routes matter as much as four-year diplomas. A technician who can keep a scanner online is not a consolation prize. That person is the reason a billion-dollar module makes wafers instead of excuses. Apprenticeships in Arizona and technician certificates in the desert Southwest are not footnotes. They are the on-ramp.
Career switchers from adjacent manufacturing can land if they accept retraining without ego. Automotive and aerospace folks already understand shift discipline and statistical process control. Translate that language into vacuum, plasma, and contamination control and you become interesting fast.
Investors Should Watch Headcount, Not Just Capex
Markets love a construction photo. Markets are slower to price a staffing miss. A plant that opens on time but ramps late is still a delayed earnings story. Watch internship conversion rates, local university partnerships, and how often companies mention temporary overseas crews. Those are leading indicators. Square footage is a lagging one.
Memory names face a double bind: they need bits and they need bodies. Logic foundries face a triple bind if they also want to be the landlord for someone else’s memory line. Equipment suppliers feel the squeeze in field service. None of this is secret. It is just easier to ignore than a missed process node.
I’ve found that the companies talking most honestly about training spend are usually the ones least likely to surprise you on the ramp. Bragging about a cleanroom is cheap. Funding a high-school lab in a factory town is a tell.
Policy Can Help, But It Cannot Staff A Shift
Incentives built the buildings. Workforce grants are trying to fill them. That split is healthy if both sides stay funded. It fails if capital outruns curriculum by five years. Immigration reform could ease the acute shortage. Domestic education has to close the structural one. Those are different clocks. Mixing them up is how countries get pretty factories and empty tool bays.
Local communities near new sites have leverage they do not always use. Housing, transit, and spouse employment decide whether a mid-career engineer actually relocates. A signing bonus cannot fix a school district a candidate does not trust. Unromantic details. Decisive ones.
A Realistic Path Through The Next Five Years
No single university will mint 157,000 people. The workable path looks like a braid: more dedicated degrees, more two-year programs, more apprenticeships, more temporary foreign experts, and yes, higher pay as ramps overlap. Accept that the first years of each new U.S. fab will lean on imported know-how. Measure success by how quickly that dependence fades.
A practical staffing mix for a new U.S. fab:
  Seed team from overseas sister plants
  Local technicians trained on similar tools
  University interns converted within 18 months
  Community-college operators for volume shifts
  Continuous upskilling as the node evolves
Does that sound messy? It is messy. Manufacturing always is. The fantasy version is a perfectly timed domestic graduate for every open req. The adult version is overlapping cohorts and a lot of overtime while the second cohort learns.
The Quiet Risk Nobody Wants To Put On A Slide
AI companies can debate whether models should slow down for safety. Hardware can force a slowdown for a duller reason: not enough hands on the tools. That would be an ironic brake. The same boom that justifies the fabs could stall because the fabs cannot staff the night shift. I do not think that is the base case. I do think it is the case you plan against if you are serious.
There is a brighter read. Software uncertainty is pushing students toward physical industries again. States that host new plants are finally treating chip certificates like economic development, not a hobby. Equipment firms want trained customers because downtime is their problem too. Align those incentives and the curve bends. Slowly. Then all at once, if we are lucky.
What I Keep Coming Back To
The United States knows how to invent chips. It is relearning how to make them at the leading edge in volume. Knowledge like that lives in people, not press releases. You can subsidize a cleanroom. You cannot subsidize intuition about a noisy process trace at 2 a.m. That intuition is built in high-volume Asian lines and, gradually, in a handful of American classrooms that finally look like factories.
So here is the plain version. The labor gap is real. The buildout is real. The training response is late but no longer imaginary. Pay will rise. Recruiting will stay global even as the strategy turns local. And the winners will be the firms that treat workforce the way they treat yield: as a daily metric, not a speech at a ribbon cutting.
If you work near one of these sites, the next few years will feel crowded and understaffed at the same time. If you are choosing a major, look past the buzzwords and ask who is touching actual tools. If you invest in the sector, count heads as carefully as you count wafers. The shortage is not a sidebar to the AI story. It is the part of the story that decides whether the rest of it ships on time.