

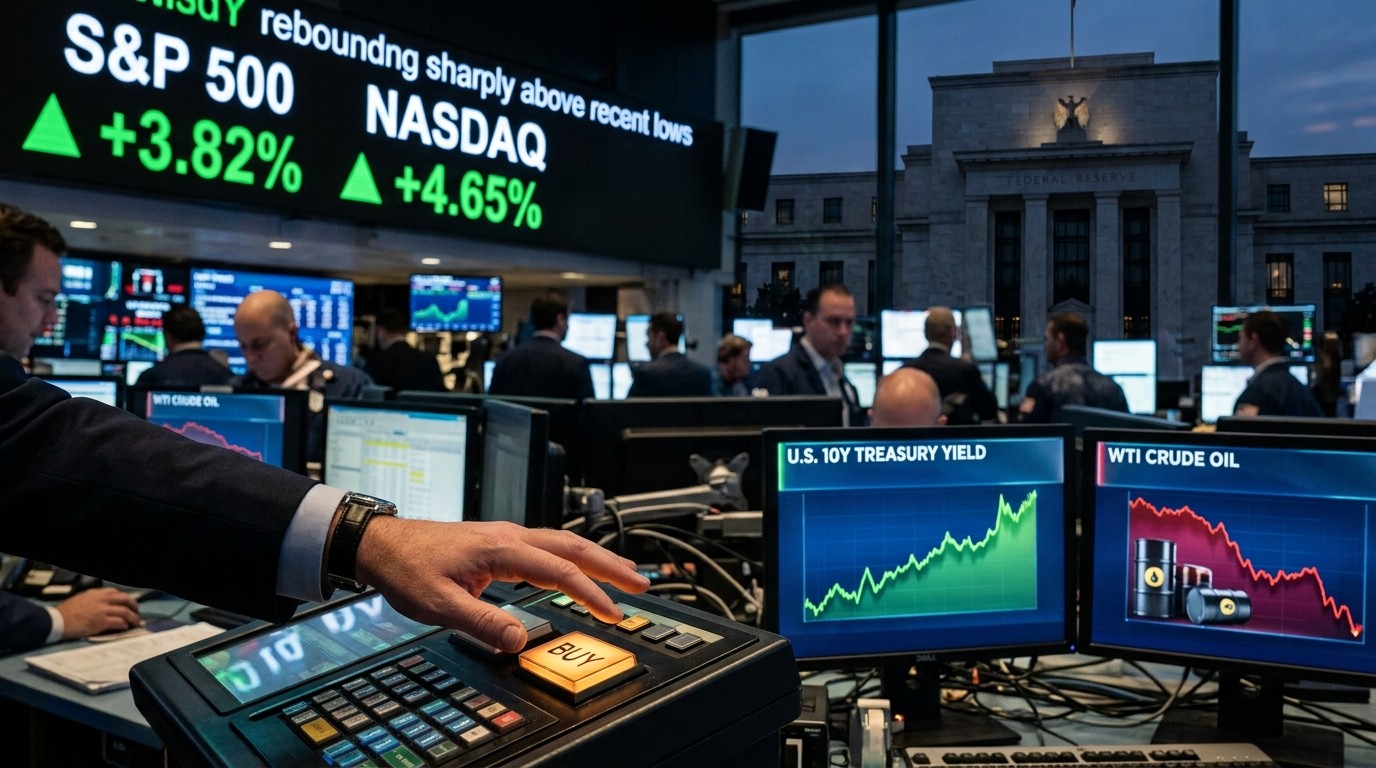
Stocks Rally After Fed Sell Off Why Buying The Dip Looks Risky

Stocks bounced hard after the Fed shock. That rebound looks tempting. Traders say the setup into month-end is still ugly, and the next two weeks may not reward dip buyers.
Financial market analysis from 17/09/2026. Market conditions may have changed since publication.
Have you ever watched a market bounce and felt that familiar itch to jump back in before the move gets away from you? That is exactly the mood after the latest rebound in U.S. equities. Stocks climbed after a bruising session tied to a quarter-point policy move and a blunt reminder that inflation has not left the building. The bounce looks clean on a five-day chart. It also looks, at least to me, a little too convenient.
Why The Rebound After The Policy Shock May Not Be A Gift
The tape recovered as Treasury yields eased and crude slipped. The Dow jumped hundreds of points after a much larger drop the day before. The S&P 500 and the Nasdaq Composite both posted solid percentage gains, with technology leading because lower yields tend to loosen the vise on long-duration growth names. Fine. Relief is real. Relief is also not the same thing as a durable bid.
I have sat through enough post-meeting snaps to know the first green morning can fool people. Traders get their breath back. Screens look less hostile. Someone tweets that the worst is over. Then month-end flows, fading demand, and a still-messy technical map start to do their quieter work. That is the part I keep coming back to.
What Actually Sparked The Sell-Off In The First Place
The trigger was not mysterious. Policy makers delivered a quarter-point increase and the chair spent real time on the risk that inflation could stay sticky. Markets hate two things at once: tighter money and a speech that refuses to offer a neat off-ramp. Equities sold. Yields jumped. Risk appetite shrank in a hurry.
Then came the snapback. Yields cooled a bit. Oil prices drifted lower. Growth stocks, which had been punished for being sensitive to discount rates, caught a bid. In my experience, that sequence is classic. It is also incomplete. A one-day repair job does not erase the reason the break happened.
The supply and demand setup into month-end remains unfavorable, the technical backdrop is still working against equities, and equities can still trade lower over the next two weeks.
– Desk strategy note circulating among institutional traders
That is not a forecast carved in stone. It is a map of pressure. When large desks talk about fading demand and rising supply, they are not being poetic. They are describing calendars, rebalancing windows, and the simple fact that some of the buyers who usually show up late in the month have already done their work.
September Has A Reputation For A Reason
Seasonality is not destiny. I say that every year, and every year someone treats an average as a guarantee. Still, the historical pattern is hard to ignore. Since the middle of the last century, the S&P 500 has tended to lose ground in September, with an average decline near seven-tenths of a percent. Weak months do not mean every September is a washout. They do mean the burden of proof sits with the bulls.
Why does the calendar matter here? Because this rebound is arriving inside a month that already leans toward distribution. Mutual fund windows, options expiries, and portfolio tidy-ups can add supply when headlines feel calmer. Calm headlines plus extra supply is how a bounce dies quietly instead of in a crash.
Perhaps the most interesting aspect is how quickly retail language flips. On Wednesday it was panic. On Thursday it was buy the dip. Markets do not owe anyone that kind of narrative neatness.
The Demand Story Is Getting Thinner
Desks that live in the flow have been blunt. Several important sources of demand are either fading or already deployed. That sentence should slow anyone who thinks a green open equals a new uptrend. If the usual buyers have spent their powder, the next seller does not need a crisis. A little uncertainty will do.
Think about it in plain terms. Corporate buybacks can pause around blackout periods. Systematic strategies that buy strength may already be closer to target. Fast money that covered shorts on the bounce is no longer a forced buyer. What is left? Discretionary accounts that still want a cleaner read on inflation, oil, and the next round of official comments.
- Month-end rebalancing can lean toward selling strength after a rebound.
- Some institutional demand for equities has already been used earlier in the month.
- Technical damage from the policy session has not fully healed.
- Lower yields helped tech, but that help can reverse if yields firm again.
I have found that people underestimate how mechanical this can get. You do not need a new scare headline if the tape is simply running out of natural buyers. Price can drift, then gap, then force late dip buyers to become the next source of supply.
Why Lower Yields And Softer Oil Are Not A Full Green Light
Yes, falling bond yields and cheaper crude helped Thursday. Growth stocks love a lower discount rate. The broader market loves any hint that energy will not keep stoking inflation prints. That combination is the closest thing the tape has to a comfort blanket right now.
Another trading group put it simply: they stay tactically cautious to neutral until oil and yields give a cleaner break lower. In other words, the bounce is allowed. The all-clear is not. I like that framing because it refuses the false choice between panic and euphoria.
The most likely path is that official comments and geopolitical noise eventually settle and stocks move higher. Timing remains uncertain, and positioning still leaves room for more downside if uncertainty hangs around.
That last clause is the one dip buyers skip. Positioning can amplify a second down leg even when the long-run case still points higher. If too many accounts are leaning the same way after a rebound, the market does not need a catastrophe. It needs a pause.
Tech Led The Bounce, And That Cuts Both Ways
Technology was the face of Thursday’s advance. No surprise there. When yields fall, the math on distant cash flows gets less ugly. Mega-cap growth becomes the easiest place to express a “maybe the worst is over” view. Liquidity is deep. Narratives are ready-made. The group can lift the whole index while a lot of other sectors still look tired.
Here is the catch. Leadership that depends on a yield fade is rented leadership. If the next inflation comment or energy spike pushes yields back up, the same names that rescued the tape can hand the losses back. I have watched that movie more than once. The first act is relief. The second act is a reminder that duration risk never really left.
So if you are tempted to chase the rebound in the usual growth suspects, ask a blunt question. Are you buying earnings momentum, or are you buying a one-day move in the bond market? Those are different trades.
A Practical Way To Read The Next Two Weeks
Forget the slogan. Buy the dip is not a strategy. It is a mood. A strategy would specify what must stay true for the bounce to hold. For this tape, I keep a short checklist that is less elegant than a slogan and more useful than hope.
- Watch whether Treasury yields keep easing or simply paused after a spike.
- Track crude for any rebound that could feed inflation anxiety again.
- Respect month-end flow risk instead of treating it as background noise.
- Look for breadth. A tech-only bounce is thinner than it looks on the headline indexes.
- Give official comments a chance to confirm or contradict the first-day interpretation.
None of that requires a heroic call. It just keeps you from treating a relief rally as a regime change. Markets can grind lower for two weeks and still finish the year higher. Those two weeks still matter if you bought the first green candle with size.
How Investors Mix Up Time Horizons After A Shock
This is where people get sloppy. A long-term investor can look at a policy-driven drop and say, reasonably, that quality companies will compound through a noisy September. A tactical trader looking at supply, technicals, and positioning can say the next ten sessions still lean heavy. Both can be right. The error is using a ten-year argument to justify a two-day entry.
I’ve found that the accounts who get hurt in these windows are rarely the ones who are “wrong about the economy.” They are the ones who size a bounce as if the calendar, the tape, and the last seller have all agreed to behave. They have not.
If your horizon is years, a choppy September is a footnote. If your horizon is the next statement cycle, it is the whole story. Be honest about which one you are actually trading.
What “Unfavorable Supply And Demand” Looks Like In Real Life
It does not look like a movie villain dumping a mountain of stock at the open. It looks like a series of small, boring decisions. A fund that bought weakness last week is now closer to its target weight. A dealer that absorbed options-related flow no longer needs to buy the same way. A corporate program hits a window where activity slows. Add those up and the bid that felt automatic on Thursday becomes optional on Monday.
Meanwhile, potential supply can rise for ordinary reasons. Tax-aware selling. Window dressing that prefers not to show names that just got hit. Systematic strategies that sell weakness after a failed bounce. None of this needs a new policy surprise. It only needs a market that is no longer short of stock.
| Market Signal | What The Bounce Suggested | What Still Looks Unresolved |
| Equities | Relief after a sharp drop | Technical damage and thin late-month demand |
| Bond yields | A welcome pullback that helped growth | Whether inflation comments push them higher again |
| Oil | Softer prices eased some inflation worry | Geopolitical risk that can reverse quickly |
| Positioning | Short covering supported the rebound | Room for another squeeze lower if uncertainty lasts |
Look at that grid long enough and the rebound starts to feel like a pause in an argument rather than the end of one. That is how I am treating it.
The Psychology Of The First Green Day
There is a reason the first rebound after a policy shock feels irresistible. Loss aversion is loud. People want to un-feel Wednesday. Buying Thursday is a way to rewrite the story before the week is even over. I get it. I have done lighter versions of the same thing and then watched the next session take the gift back.
A useful habit is to separate the emotional need to “do something” from the actual setup. If the setup is fading demand, ugly technicals, and a month that historically leaks, doing less is not cowardice. It is just refusing to pay up for comfort.
Ask yourself a slightly rude question. If this bounce had happened in a strong month with fresh demand behind it, would you size it the same way? If the answer is no, the calendar is doing more work in your head than you want to admit.
Inflation Risk Did Not Vanish Overnight
The chair’s warning was not a throwaway line. Persistent inflation is the variable that keeps policy tighter for longer and keeps the discount rate from settling. A one-day drop in yields does not settle that debate. It only says the market exhaled.
Energy is part of that story. Soft oil helps. Soft oil that reverses on a headline does the opposite. Anyone who has traded inflation scares knows how quickly a comfort variable can become the problem child again. That is why some desks refuse to flip bullish until both yields and crude give them more than a morning of cooperation.
In my view, that is the grown-up stance. Not gloomy for sport. Just unwilling to pretend a speech about sticky prices has been cancelled by a bounce in Nasdaq futures.
Technical Damage Takes Longer To Repair Than Headlines
Charts are not magic. They are a record of where people got hurt. After a 600-point type of drop in the Dow, a 300-point bounce can look heroic and still leave broken short-term structure. Failed support becomes resistance. Momentum measures stay bent. Dip buyers who ignore that are assuming memory resets at 9:30. It does not.
I prefer to see follow-through, not just a gap fill and a victory lap. Follow-through would look like broader participation, yields that stay behaved, and price that can hold gains when the first seller of size shows up. Until then, the technical backdrop is still an opponent, not a teammate.
A More Patient Playbook For Dip-Curious Investors
If you still want exposure, there are less romantic ways to do it than slamming the market-on-open button. Scale. Wait for the first failed bounce to define risk. Prefer balance-sheet quality over the names that only work when yields fall. Keep dry powder for the possibility that the next two weeks offer a better price than Thursday’s first surge.
That last point is the one people hate, because it requires accepting that you might miss a piece of the rebound. Fair. Missing a piece of a rebound is cheaper than owning the whole thing into a second down draft you were warned about in plain language.
Simple filter before buying strength after a policy shock:
  1. Is late-month demand still ahead, or already spent?
  2. Did yields and oil confirm the bounce, or just pause?
  3. Is breadth real, or is one group carrying the index?
  4. Can you explain your exit if uncertainty returns?
If you cannot answer those without waving your hands, you are not executing a plan. You are negotiating with discomfort.
What Would Actually Change The Cautious Stance
Caution should not become a personality. Markets do flip. The same desks that are careful now have already said what would make them more constructive: cleaner declines in oil and bond yields, calmer official language, and a sense that geopolitical noise is not about to throw another shock into inflation math.
That is a high but fair bar. It keeps the conversation tied to variables that actually move risk assets instead of to the emotional weather of a single session. If those variables improve, the case for buying weakness gets stronger. If they do not, Thursday’s rally is a reminder that markets can bounce and still not be cheap in the way dip buyers want them to be.
I keep coming back to timing. Even a constructive medium-term view can sit next to a messy two-week window. The investors who handle that tension well are the ones who stop treating every green open as a verdict.
The Bottom Line Without The Slogan
Stocks got relief. Yields helped. Oil helped. Technology did what it usually does when the discount rate eases for a day. None of that automatically makes this the moment to treat a policy-driven break as a clearance sale.
The less glamorous read is this. Demand into month-end looks thinner. The technical picture is still bruised. September already carries a weak seasonal reputation. Positioning can still punish anyone who assumes uncertainty is finished just because the first rebound arrived on schedule.
So no, I do not think the bounce is fake. I think it is incomplete. There is a difference, and it is the difference between respecting a rally and marrying it. If the next stretch offers lower yields, calmer energy, and a market that can hold gains without leaning on one corner of the tape, the story changes. Until then, chasing the first repair job looks less like discipline and more like a wish that Wednesday never happened.
Markets will keep offering dips. They always do. The job is not to buy every one of them. The job is to notice when the calendar, the flows, and the last official warning are still sitting on the other side of the trade.
Compound interest is the eighth wonder of the world. He who understands it, earns it; he who doesn't, pays it.


VA Loan Rates Today Sept 17 2026 And Best Lenders

Cancel Home Insurance? Steps To Take Before You Drop It
Related Articles

Vance Hails Major Progress in US Iran Talks Despite Tensions
VP Vance calls the latest US-Iran discussions a major step forward even with some heated moments. Iran agreeing to IAEA inspectors marks a big shift, but questions remain about the Strait of Hormuz and lasting peace in the region. What does this really mean for the future?
How David Ellison Accidentally Made Zaslav Rich
David Ellison wanted to build a media superpower by swallowing Warner Bros Discovery whole. Instead, he triggered a bidding war that doubled WBD's stock and just handed Netflix the keys to HBO and the Warner studio for $72B. The twist? Paramount might still launch a hostile bid... and make Zaslav even richer.
S&P 500 Surges: AI Stocks and Market Trends to Watch
S&P 500 futures rise with AI stocks leading the charge. Nvidia’s earnings spark optimism, but what’s next for markets? Dive into the trends shaping 2025…