
Have you ever heard of a metal so obscure that most people cannot even pronounce it, yet so vital that a few missed shipments can stall a jet-engine line? That is yttrium in a nutshell. I keep coming back to this story because it is not really about chemistry. It is about who holds the tap, who can turn it off, and how long everyone else can pretend they have a backup plan.
Why A Quiet Metal Suddenly Matters
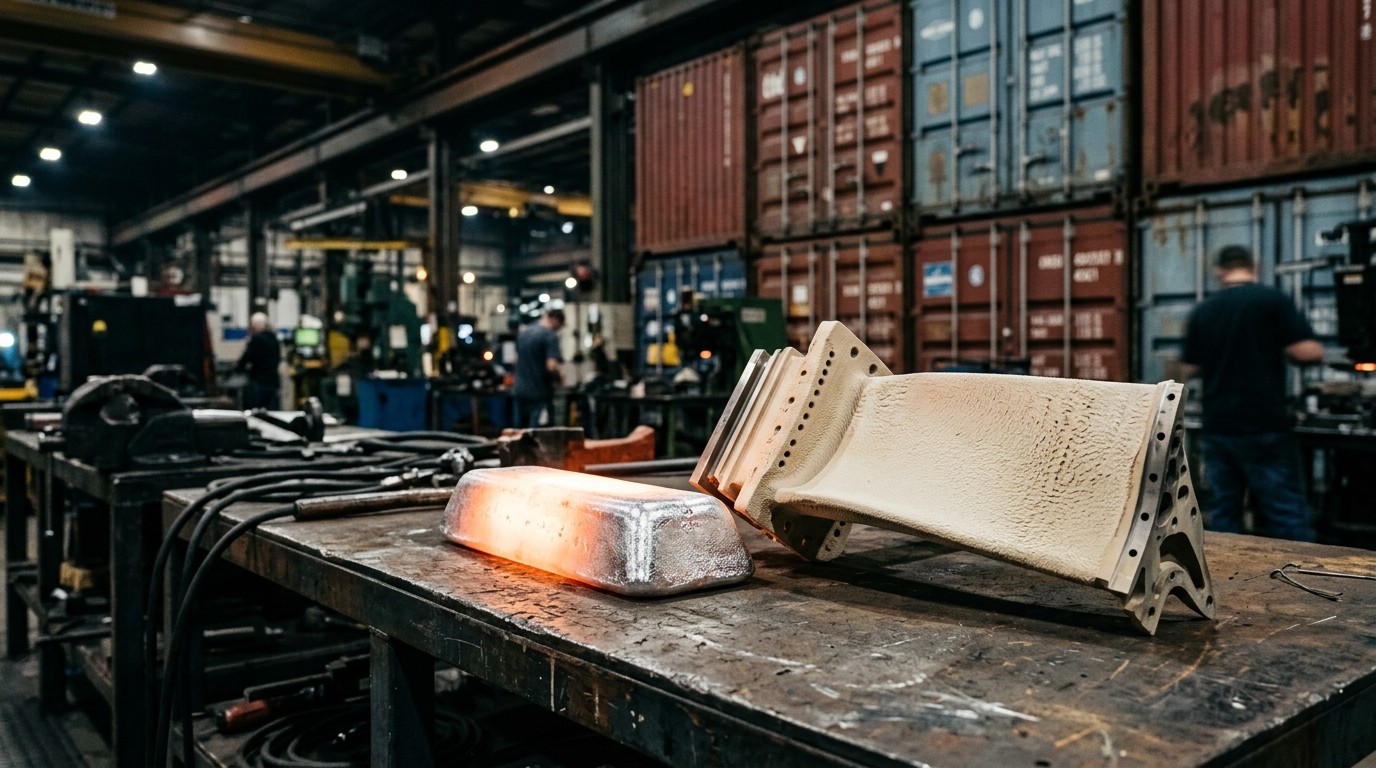
Yttrium looks ordinary. Silvery. Unflashy. You would walk past it in a warehouse and never guess it sits inside heat-resistant ceramic coatings for turbine blades, high-end optics, certain electronics, and a growing stack of industrial processes that hate surprise heat. When those coatings fail, engines do not politely wait. Plants do not shrug and keep running.
In my experience, markets ignore niche inputs until they stop arriving. Then everyone acts shocked. That is the pattern unfolding now. A dominant supplier tightened export rules on yttrium and several other rare earths. Deliveries to the United States paused for months. They came back in fits. A burst here. A trickle there. Not a reliable river. More like a faucet someone keeps twisting for effect.
Perhaps the most interesting aspect is timing. High-level talks were praised as productive. Shortly after, the flow of this particular oxide slowed again. By late winter, coating specialists were already talking about stoppages. That is not a theoretical risk. That is a shop floor problem with invoices attached.
What Export Controls Actually Feel Like On The Ground
Paperwork sounds boring until your kiln is idle. Export licensing, inspection delays, and sudden “reviews” do not show up as dramatic headlines every day. They show up as a missing drum of oxide and a production manager staring at a calendar.
Industry chatter later pointed to a larger March shipment after political pressure on behalf of a major buyer, then another interruption, then a smaller summer delivery. Uneven volumes like that are a message. They say: we can move product when we choose. We can also wait.
A quasi-monopolistic position in refining is not just a market share statistic. It is a bargaining chip that travels farther than any communiqué.
I have found that executives hate uncertainty more than high prices. You can hedge a price, at least in theory. You cannot easily hedge a permit that never arrives. That is why this squeeze travels from mines to machine shops so fast.
Not Only Yttrium: A Cluster Of Choke Points
Yttrium is the name in the spotlight this week, but it is not lonely. Similar tools have been used around gallium, germanium, terbium, and dysprosium. Tungsten has been pulled tighter as well. If you work in cutting tools, you already know what that last one does to catalogs and lead times.
One industrial distributor recently warned that the crunch is back in the tool aisle. Factories and job shops across North America feel it as higher prices for everyday consumables, not as an abstract geopolitics seminar. That is how resource pressure becomes inflation you can touch.
- Aerospace coatings that protect blades in extreme heat
- Power-turbine parts that cannot skip a maintenance cycle
- Optics and specialty electronics with thin substitution options
- Machine-shop tools that quietly raise the cost of making everything else
Look at that list again. None of those items is a luxury gadget. They sit under civilian aviation, grid reliability, and the unglamorous work of cutting metal. When those inputs wobble, the shock does not stay in one sector.
The Old Island Dispute Playbook, Updated
People who follow this file like to mention an earlier diplomatic fight over disputed islands more than a decade ago. Rare earth shipments became a pressure tool then, too. The current episode rhymes more than it copies. The product list is broader. The industries at risk are more tightly wound. The political temperature is higher.
Does that mean every shipment delay is a grand strategy memo? Not always. Customs queues happen. Quality checks happen. Still, when the same supplier sits on refining for graphite, gallium, and a cluster of rare earths, intent becomes harder to ignore. Other countries use the same trick where they dominate a mineral. Nickel and bauxite policy in Southeast Asia is the obvious parallel. Resource nationalism is not a one-capital phenomenon. It is a habit that spreads when it works.
Energy Versus Minerals: A Blunt Trade
Washington has been trying to redraw energy routes and pricing power. One strategist put the logic in language you would not print in a polite briefing: if you squeeze me on rare earths, I squeeze you on energy. Crude. Molecules. Flows that keep factories humming on the other side of the map.
That framing is ugly and, frankly, honest. It also has limits. Energy markets are deep, messy, and full of third parties. Rare earth refining is narrower. Building a new separation plant is not like opening a spare tanker route. It takes years, permits, environmental fights, skilled chemists, and a buyer who will sign a long offtake when prices look painful.
So both sides have a club. They are not the same weight. That imbalance is why analysts keep saying dominance in these materials could last through the end of the decade. I tend to agree, even if I wish I did not.
Why Alternative Supply Takes So Long
Mining is the easy slide in the presentation. Refining is the hard slide. Ore in the ground does not coat a turbine. Oxide that meets spec does. Western projects exist. Some will work. A few already produce. Capacity at commercial scale, with consistent purity, at a cost buyers will live with in a down cycle, is another story.
Communities push back on processing. Capital wants a guaranteed margin. Engineers want feedstock that does not change every quarter. Meanwhile the incumbent supplier already has the plants, the know-how, and the customer list. Catch-up is not a press release. It is a slog.
| Bottleneck | Why It Hurts | Time To Ease |
| Mining permits | Local opposition and long reviews | Multi-year |
| Separation plants | Specialized chemistry and waste handling | Longer than mining |
| Qualified coatings | Aerospace testing cannot be rushed | Cycle after cycle |
| Tooling metals | Price spikes hit small shops first | Immediate pain |
That table is not poetry. It is a reminder that “just mine it at home” is a slogan, not a schedule. I have sat through enough conference panels to know the difference.
Aerospace And Energy Feel The Heat First
Jet engines and power turbines live in brutal temperatures. Ceramic coatings buy them time. Yttrium compounds help those coatings stay put. If the oxide is late, you do not casually swap in a hobby-store substitute. Qualification exists for a reason. Nobody wants an experimental glaze at thirty thousand feet.
Energy operators face a quieter version of the same problem. Outage windows are planned months ahead. If a coating line slips, maintenance slips. If maintenance slips, you burn more fuel, derate a unit, or pay someone else to keep the lights on. The public sees a rate hike. The plant manager sees a missing chemical.
Semiconductor-adjacent uses add another layer. Volumes can be small. Specifications can be ruthless. A shortage does not need to be large in tonnage to be large in impact. That is the cruel math of critical inputs.
Prices, Hoarding, And The Shop-Floor Tax
When shipments stutter, two things happen almost on cue. Buyers over-order. Intermediaries raise offers. Suddenly a metal that lived in a footnote starts moving like a rumor. Tool distributors pass costs through. Machine shops pass them through again. By the time a finished part ships, the original squeeze is baked into the quote.
Is that “inflation” in the textbook sense? Partly. It is also rationing by price plus rationing by relationship. Preferred customers get the next lot. Everyone else waits. I have watched this movie in other metals. The ending is rarely tidy.
- First the license delay hits the importer.
- Then the coater idles a line and burns working capital.
- Then the engine or turbine program slips a few weeks.
- Then the tool catalog reprints with uglier numbers.
- Then policymakers notice, usually late.
That sequence is why this is not a niche commodities column. It is a production story wearing a geology costume.
What “Weaponized Shipments” Really Means
People love dramatic verbs. Weaponize. Choke. Squeeze. Sometimes the mechanism is quieter. Approve this application. Sit on that one. Allow a cargo after a phone call. Hold the next cargo until a different meeting. You do not need a total embargo to change behavior. You need unpredictability.
Uneven deliveries teach buyers faster than any speech. Reliability becomes the scarce good.
In my view, that lesson is the point. Once a customer believes supply can vanish after a summit photo, they start writing contingency memos. Some of those memos become budget lines. A few become mines. Most become higher inventory and higher prices. All of them change the relationship.
The West’s Awkward Homework
Stockpiles help, until they do not. Recycling helps, until volumes disappoint. Friendly-shore refining helps, until costs explode. Allies help, until they protect their own plants first. There is no single elegant fix. There is a pile of partial fixes that only work if someone pays for idle capacity in the quiet years.
That last bit is the part speeches skip. A refinery that exists only for emergencies still needs staff, power, and a reason to stay open when spot prices sag. Without that, you get another round of dependency dressed up as diversification.
Supply resilience, in practice:
  25% real alternative refining
  25% inventories that actually exist
  25% qualified substitutes
  25% political patience when costs rise
Ugly split. Closer to reality than a slogan about “independence by next fiscal year.”
Investors Keep Asking The Wrong First Question
The first question is usually “which miner pops?” Fair. Also incomplete. The tighter question is who can process, qualify, and deliver on a schedule an aerospace buyer will sign. Junior exploration stories are fun. Offtake contracts and separation know-how pay the bills.
Watch coating specialists, specialty chemical names, toolmakers, and the unloved midstream. Watch working-capital stress at small shops. Watch whether governments fund plants that lose money in normal years. That is the boring map. It is also the useful one.
Risk management here is not a fancy options overlay. It is dual sourcing that actually works, inventory that is not just a line on a slide, and the humility to admit some inputs have no quick twin.
A Longer Stretch Of Vulnerability
Research desks have started saying the quiet part: control over key minerals and refining can last at least through 2030. That does not mean prices only go up. It means leverage remains. A freeze can return. A thaw can be temporary. Planning as if the next decade will be “normal” looks careless.
Could diplomacy smooth the edges? Sure. Summits happen. Cargoes move after phone calls. Then a different dispute appears and the faucet twitches again. Hoping for permanent goodwill is not a strategy. It is a mood.
Meanwhile households will not talk about yttrium at dinner. They will talk about airfares, power bills, and why a replacement part takes nine weeks. That is how a silvery metal becomes a kitchen-table issue without ever being named.
Practical Signals Worth Tracking
If you follow this as an operator or an investor, skip the noise and watch a short list of tells. License backlogs. Spot premiums versus contract prices. Lead times at coating houses. Comments from tool distributors. Announced but unbuilt separation capacity. Those five beat a hundred think pieces.
- Shipment volumes that arrive in lumps instead of a steady monthly rhythm
- Sudden inventory builds at large aerospace or energy buyers
- Public warnings from industrial distributors about tool inflation
- New export categories added to existing rare-earth rules
- Projects that keep slipping their first-production date
None of those items requires a secret source. They sit in trade data, earnings calls, and plant gossip. Put them on one page. Update them. You will see the squeeze coming earlier than a headline will admit.
The Human Texture Behind The Spreadsheet
It is easy to treat this as a chessboard. Real people coat blades, schedule shifts, and call suppliers at midnight. When a drum does not land, someone cancels overtime or burns a weekend. That friction never makes a strategy memo, but it is the texture of a resource fight.
I keep thinking about the machine shop that does not lobby anyone. They just need inserts and a predictable quote. When tungsten and cousin metals jump, they eat margin or lose a bid. Multiply that by thousands of shops and you get a slow leak in industrial competitiveness. No sirens. Just a grind.
That is why I bristle when coverage stays at the level of flags and podiums. The fight is also in the tool crib.
Could Substitutes Save The Day?
Sometimes. Not on a deadline that matches a political cycle. Materials science is slow when safety cases are involved. A new coating chemistry can look brilliant in a lab and still take years to sit on a certified engine. Power turbines are not much faster. Consumer gadgets can pivot. Flight hardware does not.
Recycling of magnets and certain electronics will grow. Good. Necessary. Still a rounding error against primary demand if aviation and grid equipment keep expanding. Treat recycling as a helper, not a hero.
Resource Nationalism Cuts Both Ways
If one capital limits oxides, another can limit molecules. If one restricts processing technology, another can restrict equipment. Tit-for-tat feels satisfying in a briefing. It also raises the odds of shortages that nobody intended to create. Secondary effects show up in countries that never picked a side. They just needed a part.
I am not naïve about leverage. States use what they have. I am wary of the belief that a counter-squeeze is clean. Global production networks are tangled on purpose. Pull one cord and three others twitch.
Leveling a playing field is a reasonable goal. Flattening a supply chain by accident is an expensive hobby.
What A Sane Response Looks Like
Fund refining, not just ribbon-cuttings at pits. Pay for qualification so new sources can actually enter aerospace specs. Keep strategic inventories of oxides that matter, not a museum of whatever was cheap that year. Talk to job shops, not only prime contractors. And stop pretending a summit photo resets geology.
Companies can do the unglamorous work too. Dual-qualify coatings. Accept a higher carrying cost for critical drums. Share demand forecasts with midstream partners instead of surprising them. None of that trends well. All of it works better than a panicked buying binge after the next halt.
A Closing Thought You Will Not Like
Yttrium will not stay famous. Another metal will take the headline. The structure will remain. A handful of refining hubs. Long lead times. Political tempers. Factories that cannot pause for a theory. If you care about aerospace schedules, grid reliability, or the price of making things, this is not a one-week curiosity.
The shipments that arrive in lumps are the tell. They prove product still exists. They also prove permission is the scarce input. Until that changes, Western supply chains stay exposed, and every calm month is just the pause between twists of the same faucet.
I wish the answer were a neat checklist and a two-year buildout. It is not. It is patience, money, and the unfashionable habit of treating obscure oxides as strategic even when they are boring. Especially when they are boring.