

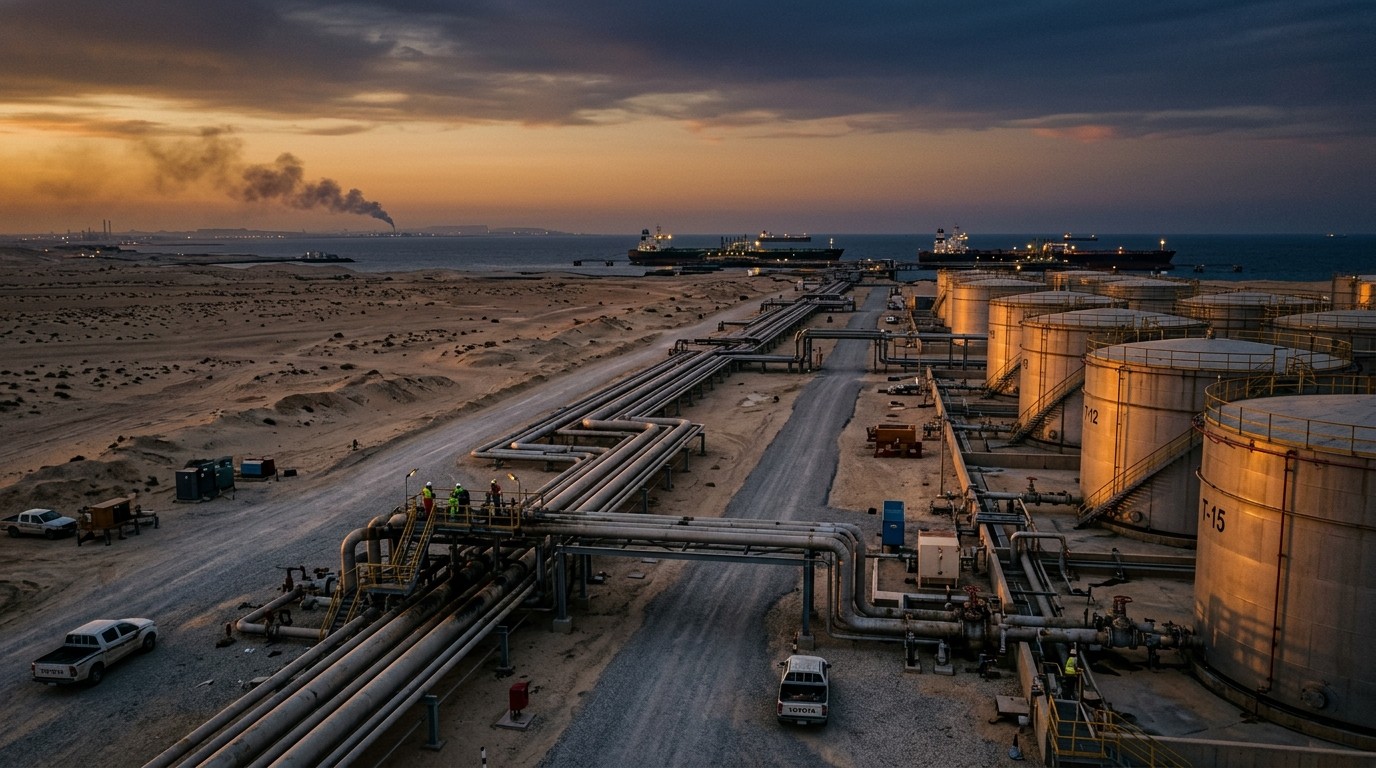

Have you ever watched a market drop on a day that, on paper, should have sent prices higher? That is the odd feeling hanging over oil prices today. Fresh strikes along the Saudi-Yemen border should have tightened nerves. Instead, Brent and WTI eased as traders decided extra Saudi barrels might still find a way to Asia. I have found that energy markets often price the story they want to believe first, then wait to see if the facts cooperate.
Why Oil Prices Slipped Despite Fresh Regional Strikes
The move was not huge. It was still telling. Brent crude futures slipped close to one percent and hovered near $103.83 a barrel. WTI futures were down a similar fraction near $101.01. Those are still elevated levels by the standards of quieter years. They are not the panic print some expected after another night of cross-border attacks.
What changed the tone was logistics, not peace. Reports that Saudi crude can still move toward Asian buyers through alternative routes, including paths linked to Oman, reduced the fear that a damaged pipeline equals a missing cargo. Markets hate uncertainty. They like a workaround even more.
That does not mean the danger vanished. It means the geopolitical risk premium was trimmed, not deleted. In my experience, that kind of trim is fragile. One blocked terminal, one delayed restoration, one rumor about the Strait of Hormuz, and the premium snaps back.
The Two Prices Everyone Watches First
People talk about “the oil price” as if it were one number. It is not. Brent is the international yardstick. WTI is the U.S. grade that still shapes American headlines, refinery margins, and political temperature. When both fall together, the message is global. When they diverge, the story usually sits in freight, inventories, or a regional bottleneck.
| Benchmark | Role | What Traders Read In It |
| Brent | Global seaborne crude | Shipping risk, Middle East flows, Asia demand |
| WTI | U.S. inland and Gulf crude | Domestic supply, refining, inventory swings |
| Saudi official selling prices | Producer signal | How Riyadh wants Asian and other buyers to behave |
On this session, both benchmarks eased in lockstep. That points to a shared narrative: less immediate shortage than feared, not a sudden collapse in demand. Demand did not magically improve overnight. Fear simply cooled a notch.
Saudi Barrels, Asian Buyers, And A Damaged Pipeline Story
Saudi Arabia remains the producer that can change the mood of a trading floor with a single operational update. After attacks hit a key east-west pipeline, the instinctive market reaction was simple. If crude cannot cross the kingdom the usual way, less of it reaches the water. Less on the water means tighter seaborne supply.
Then came the counter-story. Alternative routing. Shipments still moving. Asian refiners not left completely empty-handed. That is the kind of detail that lets a risk premium unwind without anyone claiming the conflict is over. It is messy. It is also how real commodity markets work.
Oil prices reflect not just available barrels but also the probability of those supplies being disrupted.
– Market strategist commentary circulating among traders
I keep coming back to that line because it is the cleanest way to explain Friday’s dip. The physical oil did not suddenly flood the world. The probability assigned to a worse disruption fell. Probability is what futures are built on.
Houthi Strikes And Why Traders Still Sleep Lightly
New exchanges of fire between Saudi forces and Yemen’s Iran-backed Houthis did not vanish from the tape. They just shared the headline with a logistics update. That split attention matters. A market can absorb bad news if it thinks the barrels still sail.
The wider backdrop is already tense. Energy infrastructure in the region has looked more exposed since earlier shocks involving Iran, Israel, and U.S. action earlier in the year. Traders do not need a textbook. They need a map. Pipelines, terminals, and the Strait of Hormuz sit on that map like tripwires.
- Border strikes raise the chance of another hit on export kit
- Pipeline repair speed decides how long the workaround must last
- Hormuz chatter can reprice freight and insurance in hours
- Asian term contracts watch official selling prices as much as headlines
None of those items disappeared because prices fell one percent. They just got a temporary discount. Perhaps the most interesting aspect is how quickly that discount can vanish. Energy is a rumor market wearing a spreadsheet’s clothes.
Risk Premium Versus Real Barrels
There is a habit in commentary of treating every tick as a verdict on the global economy. Sometimes the tick is just fear changing clothes. A partial unwind of the geopolitical premium is not the same thing as a bearish supply-demand shift. Inventories did not suddenly overflow. Refiners did not cancel runs. Ships did not multiply.
What moved was the market’s guess about how many Saudi barrels stay stranded. Improved export logistics lowered that guess. That is it. Hardly poetic. Still decisive.
I’ve found that readers often want a single villain or a single rescue. Oil rarely offers either. You get a stack of partial truths. A pipeline is impaired. A detour exists. A militia can still strike. Asia still needs feedstock. All of those can be true before breakfast.
What Near-Term Drivers Matter More Than Classic Demand Charts
In calmer seasons, analysts lean on inventories, refinery runs, and seasonal driving. Those still matter. They are just not the loudest voice this week. Geopolitics is doing the talking. Traditional balances are in the room, quietly taking notes.
- Watch whether Saudi flows to Asia stay visible and regular.
- Track any official word on east-west pipeline repair timelines.
- Listen for insurance and freight spikes around key waterways.
- Only then fold in weekly stock data and refinery maintenance.
That order of operations feels backward if you learned oil from textbooks written in quieter decades. It is not backward now. When infrastructure is the story, barrels on a spreadsheet are a lagging character.
Asia Is The Quiet Swing Vote
A lot of Western coverage treats the price as a New York or London mood. The physical bid often lives in Asia. If Saudi grades keep arriving, even by a longer or stranger path, refiners can plan. If arrivals slip, official selling prices, differentials, and freight all start arguing at once.
That is why the Oman-linked routing chatter landed. It was not a peace deal. It was a shipping paragraph. Shipping paragraphs move crude more often than speeches do.
In my experience, when Asian buyers stop complaining in private and start hedging in public, the screen notices. We are not fully in that panic lane today. We are one missed cargo away from visiting it.
Why A One Percent Drop Can Still Leave Prices Historically Firm
Do not confuse a down day with cheap oil. Triple-digit Brent is not a bargain print for airlines, truckers, or households that feel fuel in the grocery ticket. The session was a relief rally in reverse: less fear, not a new surplus.
That distinction matters for anyone translating the tape into real life. A factory manager does not celebrate because the risk premium shrank by a dollar. A commuter does not either. Traders do, because they live in changes, not levels.
The latest decline looks like a partial unwind of fear, not a fundamental rewrite of the oil balance.
That is the sentence I would tape to the monitor. If the conflict widens again, the same market that sold the rumor of extra supply can buy the fact of another outage. Fast.
Chokepoints, Terminals, And The Map That Still Runs The Tape
Ask a veteran trader what keeps them up and they will not start with a demand model. They will mention water. Narrow water. The Strait of Hormuz remains the sentence that can reprice an entire complex before lunch. Export terminals are the next sentence. Pipelines are the third.
Saudi Arabia’s east-west line matters because it is a relief valve as well as a pipe. If that valve stays impaired, every workaround has to work harder. Workarounds cost time, money, and political patience. Markets can live with cost. They hate surprise cost.
Simple stress stack traders keep in their heads:
  1. Can the barrels leave the field?
  2. Can they cross the country?
  3. Can they load?
  4. Can they pass the strait?
  5. Can they arrive on time in Asia?
Miss any one of those five and the premium returns. Hit all five for a few weeks and the premium bleeds. Today looked like a bleed, not a cure.
How This Session Fits A Longer Conflict Premium
Oil has been carrying extra tension for months, not hours. Attacks, counterattacks, and fears of a broader energy shock have been part of the furniture. That is why a modest dip can coexist with prices that still look rich. The floor is higher because the threat list is longer.
I do not buy the idea that one routing workaround resets that whole list. It takes a item off the emergency pile. The pile remains. Anyone selling the market as “fixed” after a single session is selling comfort, not analysis.
Still, comfort trades. And comfort traded on Friday.
What Households And Businesses Should Actually Watch
Most people do not need a futures ladder. They need a translation. Pump prices lag. Jet fuel lags in tickets. Diesel shows up in delivered goods. A one-day crude dip rarely shows up in a shopping cart by the weekend. A multi-week crude shock does.
- If crude stays heavy because routes keep working, fuel inflation can cool at the margin
- If another facility is hit, the lag works the other way
- Airlines and shippers feel freight and hedge costs before consumers do
- Emerging-market importers feel the bill faster than large strategic reserve holders
That is the unglamorous chain. It is also the one that decides whether a market story becomes a kitchen-table story.
The Case For Downside If Logistics Keep Improving
There is a coherent bearish path from here, and it does not require a demand crash. Keep Saudi barrels moving to Asia. Show progress on the east-west line. Avoid a Hormuz scare. Let some of the emergency premium leak out week after week. Prices can grind lower while still looking expensive versus a peaceful baseline.
That path is conditional. Markets love conditionals until the condition breaks.
The Case For A Fast Reversal If The Map Tightens Again
The bullish path is shorter to write because it is older. Another strike on export kit. A delay in repairs. A shipping warning. A spike in war-risk insurance. Any of those can put the premium back on in a session. Sometimes in an hour.
This is why so many desks say geopolitics will outrank classic balances in the near term. They are not being dramatic. They are reading the calendar.
A Practical Way To Read The Next Few Sessions
Ignore the temptation to treat every downtick as proof that “the worst is over.” Look for repetition. One workaround story is a headline. Two weeks of confirmed loadings are a trend. Repair updates with dates are better than vibes. Freight rates that refuse to spike are a tell. Official selling prices that stop chasing fear are another.
And if those signs fail? Then Friday was only a pause. Pauses are common in commodity shocks. Endings are rare.
Continued flows to Asia and visible pipeline progress could pressure prices. Fresh export trouble could restore the premium almost immediately.
That two-line framework is enough for most readers. You do not need a twenty-factor model to see the fork in the road.
Why This Story Feels Familiar And Still Dangerous
Energy crises rhyme. A facility is hit. Prices jump. A workaround appears. Prices fade. People relax. Then the next facility is hit. I have watched versions of that loop more than once. The familiarity is what makes it slippery. Familiarity breeds a casual tone the barrels do not share.
So yes, oil prices today fell. Yes, Saudi supply hopes outweighed the first wave of worry about new Houthi strikes. Yes, that can continue. It can also stop being true between this paragraph and the next inventory report.
If you only remember one thing, remember this. The market did not decide the Middle East is safe. It decided, for one session, that enough barrels might still arrive. That is a thinner cushion than it sounds.
Final Take: Watch The Route, Not Just The Quote
Screens are loud. Routes are quieter and more important right now. Brent near $104 and WTI near $101 after a modest drop tell you fear cooled. They do not tell you the pipes are healed, the border is calm, or Asia is guaranteed timely supply.
Keep the question simple when the next alert hits. Did the barrels still load? Did they still sail? Did they still clear the narrow water? If the answer stays yes, the premium can keep leaking. If the answer flips, oil prices today will look like a footnote to a sharper move.
That is not a forecast dressed as certainty. It is a map. In this market, the map is doing more work than the model.



