
Have you ever looked at a family house bought decades ago for a tiny sum and watched someone insist the paperwork still tells the whole story? That is the feeling I get whenever the conversation turns to America’s official gold books. The metal sits in vaults. The market has moved on. The statutory number has not. And once you start asking what would happen if that number were rewritten in a dramatic way, the thought experiment stops being a curiosity and starts looking like a window into how sovereign balance sheets actually work.
Why A Gold Revaluation Thought Experiment Keeps Coming Back
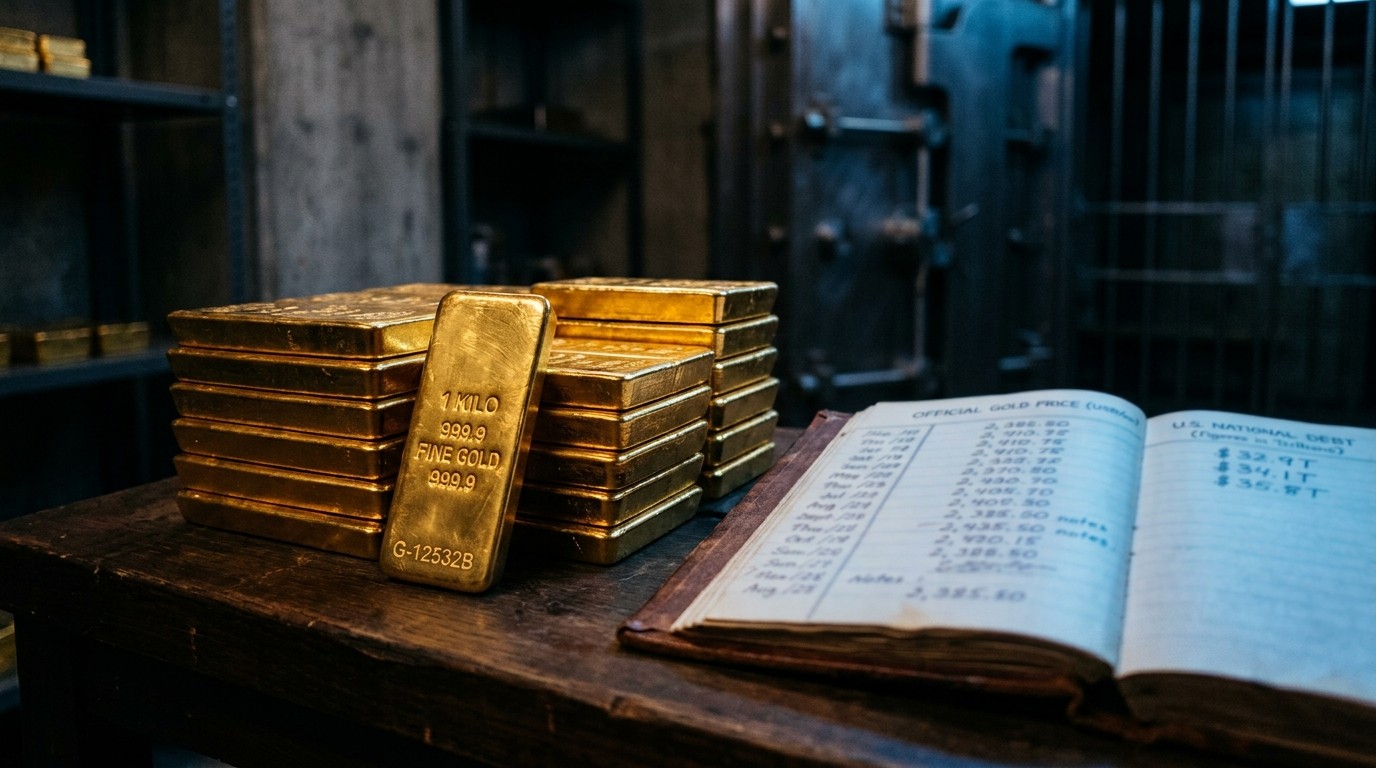
The United States holds a very large official gold stock, commonly cited around 261.5 million ounces. That is the largest declared national hoard on Earth. Yet the books still carry the metal at a statutory price of about $42.22 an ounce. At that figure the entire stock looks like a rounding error, roughly $11 billion. In the market, the same ounces are worth well over a trillion dollars. The gap is not a secret. It is a legal artifact that has survived for more than half a century.
I have found that people hear “revalue the gold” and immediately jump to two extremes. One camp treats it as alchemy. The other treats it as a free lunch that could wipe the national debt off a spreadsheet. Both miss the plumbing. Revaluation does not invent factories, power plants, or extra ounces. It changes the official unit of account attached to an existing asset and, under current institutional arrangements, it can change how much financing capacity Treasury might unlock through gold certificates.
That last point is the part that makes the fringe version so sticky. If you push the official price high enough, the accounting value of the stock can be made to match almost any headline fiscal number you want. At a few thousand dollars an ounce you get a large but still imaginable balance-sheet adjustment. At $100,000 you get tens of trillions. At roughly $155,000 you can make the gold stock look large enough, on paper, to sit next to a $40 trillion debt figure. The arithmetic is simple. The economics are not.
Changing the official price of gold does not create new wealth. It assigns a different number of dollars to the same metal.
The Statutory Price Versus The Market Price
The statutory price is the legal yardstick used for official accounting. The market price is what a willing buyer and seller agree on in London, New York, or any other liquid venue. Those two numbers have lived in different universes for a long time. That is why the apartment analogy works so well. Nobody walking past a Manhattan building bought generations ago would accept the original purchase price as a description of current value. Governments, for historical and legal reasons, have done exactly that with gold.
In my experience, the $42.22 figure is more interesting as a signal of inertia than as a valuation. It tells you that the political system never felt enough pressure to update the books. Central banks elsewhere have kept accumulating physical metal while official U.S. accounting stayed frozen. That contrast is part of why gold bulls like the idea of a formal mark closer to reality. It would be an admission that the metal still matters as a monetary asset, not just as a museum piece.
A modest revaluation is easy to sketch. At $5,000 an ounce, 261.5 million ounces become about $1.3 trillion. At $10,000 they become about $2.6 trillion. Suddenly an $11 billion line item looks like a serious reserve asset again. Treasury would not need to roll trucks out of a Kentucky vault. The bars can stay exactly where they are. The action is on the certificate side of the ledger.
How Gold Certificates Already Connect Treasury And The Fed
There is already a mechanism for Treasury to issue gold certificates against official gold and receive a credit at the central bank. That plumbing is not a rumor. It is old institutional furniture. The constraint is the statutory valuation itself. Certificates are limited by the official price Congress has left in place. Change the law, and the same pipes could carry a much larger number.
Think of it this way. The gold does not have to be sold into the market for the government to book a higher official value. The government can restate the asset, issue more certificates against the restated value, and see a larger balance in the Treasury General Account. That is the relatively sober version of the story. It is still hypothetical in scale. It is not hypothetical as a concept. Other governments have used revaluation gains on reserve assets for fiscal purposes. The details differ by country. The temptation is familiar.
Perhaps the most interesting aspect is how quiet the first step would look. No public auction of bars. No midnight convoy. Just a legal change, an accounting restatement, and a credit. The drama arrives later, when someone decides what to do with the new balance.
The Extreme Case: Matching Gold To The National Debt
Now the fringe version. Suppose policymakers do not stop at a price that looks “more realistic.” Suppose they pick a number designed to make the gold stock line up with the stock of government debt. At $100,000 an ounce the official value of 261.5 million ounces is about $26.15 trillion. Near $155,000 it crosses $40 trillion. Those are the kinds of figures that make budget conversations sit up straight.
On a spreadsheet, you can then imagine Treasury issuing a huge volume of certificates and receiving a huge credit. In theory that credit could be used to retire Treasuries. Bonds vanish from the liability side of the government’s published debt statistics. Interest expense on those securities disappears. The debt-to-GDP ratio looks transformed overnight. It is the kind of chart that would dominate a hearing. It is also the kind of chart that hides the other side of the swap.
The holders of those securities do not vanish. They get paid. What leaves the system as interest-bearing government paper can re-enter the system as cash and other monetary claims. You have not deleted an economic burden. You have changed the form in which that burden is carried. That distinction is everything.
| Official gold price | Approx. book value of 261.5 million oz | What the number mainly does |
| $42.22 | About $11 billion | Keeps gold almost invisible on the books |
| $5,000 | About $1.3 trillion | Makes reserves look material again |
| $10,000 | About $2.6 trillion | Creates large certificate capacity |
| $100,000 | About $26.15 trillion | Enters fiscal-scale territory |
| About $155,000 | About $40 trillion | Can be lined up with a huge debt stock |
Why The New Dollars Are Not New Factories
This is where a lot of commentary gets sloppy. People talk as if marking gold to $155,000 would make the country $40 trillion richer. It would not. The same workforce still goes to work. The same power grid still hums. The same farmland still grows food. The same 261.5 million ounces still sit in vaults. You have multiplied the dollar labels attached to those ounces.
If Treasury then spends the newly credited balance to buy back debt, liquidity can swell unless the central bank offsets it. We are not talking about a routine bill auction. We are talking about a monetary event with almost no modern American precedent if it were done at full scale and left unsterilized. I keep coming back to a blunt sentence: you cannot make tens of trillions of government obligations disappear without something else in the system changing shape.
- The gold stock stays the same physical quantity.
- The official dollar value of that stock can be rewritten by law.
- Certificates can turn the higher official value into Treasury cash at the Fed.
- Using that cash to retire bonds replaces securities with money-like claims.
- The real adjustment can show up in prices, rates, and the dollar.
Maybe the cleanest way to read a $155,000 official price is not “gold just became magic.” It is “it now takes a spectacular number of dollars to stand next to one ounce.” In that reading, the headline is as much about the currency as it is about the metal.
What Could Happen To The Dollar If The Capacity Were Used
Revaluation by itself does not dump $40 trillion into checking accounts. First you get a larger Treasury balance. The monetary event begins when that balance is deployed. If tens of trillions were used to retire debt and the central bank did not drain the resulting liquidity, you should expect some mix of a weaker dollar, higher inflation, higher nominal asset prices, and a shift in rate expectations. The mix would depend on sequencing, communication, and how aggressively policy offset the flow.
I’ve found that investors often skip that last clause. Offset matters. A full-scale operation with no offset is a different animal from a limited restatement that never leaves the government’s own accounts in a disruptive way. Structure is not a footnote. Structure is the story.
Even then, an official price is not a market order. Washington can choose an accounting value. It cannot force every dealer desk in the world to trade at that value tomorrow morning. Gold in New York and London would still be priced by supply, demand, and confidence. The signal, though, would be enormous. The issuer of the world’s primary reserve currency would have just said that gold is important enough to help restructure the sovereign balance sheet.
The government can pick an accounting price. The global market still gets a vote on the trading price.
How Other Reserve Managers Might Read The Signal
Put yourself in a foreign reserve manager’s chair for a minute. You hold dollars and government bonds because they are liquid and because the system has been built around them. Then the United States itself assigns gold a dramatically higher monetary role in its own fiscal cleanup. Do you want more of the asset Washington just treated as balance-sheet medicine, or more of the paper it just implied needed help?
That question would not stay theoretical. Central banks have already been adding gold for years while public debate in the United States treated the metal as a relic. A giant official revaluation would make that quiet accumulation look less like nostalgia and more like preparation. It could also look like an admission that gold never fully left the monetary system. We spent decades talking as if it had.
Would every country immediately dump reserves and scramble for bars? Probably not in a single weekend. Markets are messy. Politics is slower than a thought experiment. But the relative attractiveness of gold versus long-duration government paper would be reopened in every serious reserve meeting on Earth. That is not a small side effect. That is a regime conversation.
A More Modest Path Still Changes The Conversation
I am not sitting here predicting $100,000 gold as a base case. That figure is useful because it is extreme. It shows how powerful the certificate mechanism becomes when you refuse to stop at a “reasonable” official price. The current $42.22 valuation is extreme in the opposite direction. One number is theatrical. The other is fossilized.
A middle path is easier to defend in public. Mark the gold closer to a round number that still looks connected to market reality, unlock a trillion or two of capacity, and use the optics of a cleaner balance sheet without pretending you have invented a new country. Even that path would require Congress to change the law. It would also force a debate about whether gold is being treated as a monetary anchor again or merely as a one-time fiscal gadget.
Those are different stories. An anchor implies discipline later. A gadget implies the opposite: use the gain, keep spending, hope the currency absorbs the rest. Investors should care which story policymakers think they are telling, because markets will eventually decide which story they believe.
Interest Expense, Debt Statistics, And The Cost That Does Not Vanish
Retiring a mountain of Treasuries would cut future coupon payments on those particular securities. That is real in a narrow accounting sense. Debt headlines would look better. Politicians would have a simpler slide. Households watching cable news would hear that the burden shrank.
The underlying economic cost can migrate into inflation, a cheaper currency, and higher nominal prices for houses, stocks, and commodities. Savers holding cash would feel that migration first. Holders of hard assets might feel it as a bid. The distribution of pain and gain would not be even. It never is when the unit of account is the thing being stretched.
- Restate official gold at a new legal price.
- Issue additional certificates against the restated stock.
- Receive a larger Treasury balance at the central bank.
- Use some or all of that balance to retire marketable debt.
- Watch liquidity, inflation, and the dollar absorb whatever is not offset.
Step five is the one people skip when they fall in love with step four. I keep saying that because the skip is where the thought experiment turns from clever to careless.
What This Means If You Care About Gold As An Investment
Gold investors tend to hear any official revaluation talk as validation. Fair enough. A government that updates a fifty-year-old statutory price is conceding that the old number is absurd. A government that uses gold as a fiscal tool is conceding something larger: the metal still sits near the center of sovereign finance when paper claims get heavy.
That does not mean the market price must jump to the official price on day one. It does mean the psychological bid for official gold could strengthen, especially outside the United States. It also means dollar weakness, if it arrived as a result of monetizing the revaluation, could itself lift the nominal gold price. The causal chain is indirect. It still matters.
In my view, the healthier way to hold the idea is as a scenario, not a forecast. Ask what official price would be politically sellable. Ask whether any capacity would actually be used to retire debt or whether it would simply fund more spending. Ask how the central bank would respond. Those questions separate a serious reader from someone collecting viral numbers.
Political Optics Versus Market Plumbing
Optics will always be part of this. A Treasury secretary staring at hundreds of millions of ounces and a strained fiscal path is going to notice the $42.22 line eventually. Why keep one of the country’s most valuable financial assets at a price disconnected from reality for another generation? That question writes itself. The answer is never only about honesty in accounting. It is about what happens after the honesty.
If the restatement is small and mostly symbolic, markets may shrug after a day of headlines. If the restatement is large and then monetized, markets will not shrug. Reserve managers, bond holders, and currency traders will all try to map the same event onto their own mandates. Some will call it balance-sheet cleanup. Some will call it camouflaged inflation. Both descriptions can be partly true at once.
That dual reading is why I like the thought experiment even when I do not buy the most theatrical price targets. It forces you to look at gold, debt, and the dollar as one system instead of three separate sports channels.
A Few Practical Guardrails Before Anyone Gets Carried Away
First, inventory and audit debates will explode the minute a huge official price is floated. If the metal is going to carry a multi-trillion-dollar label, people will want more transparency about what is actually in the vaults. That is healthy. It is also politically messy.
Second, legal change is not a blog post. Congress would have to rewrite the statutory framework. That process would leak, get litigated in public, and give markets time to position. Surprise is overrated in sovereign finance. Anticipation is the usual state of play.
Third, do not confuse a higher official gold price with a gold standard. A gold standard implies convertibility and constraint. A revaluation-plus-certificates operation can be the opposite: an attempt to loosen a fiscal knot by stretching the unit of account. Words matter here. People will try to smuggle one meaning inside the other.
Simple way to keep the ideas separate:
  Revaluation = new official number on existing ounces
  Monetization = turning that number into spendable Treasury balances
  Offset = whether the central bank drains the extra liquidity
  Outcome = prices, rates, and the dollar after those choices
So What Price “Makes Sense”?
The interesting question is not whether $42.22 still makes sense. It does not. The interesting question is which official price a future Treasury team would dare to call honest. A number near the market would be easier to explain. A number far above the market would look like an attempt to manufacture fiscal room. A number designed to match the entire debt stock would look like theater with monetary consequences.
I’ve sat with this long enough to think the sane conversation is the one that admits two true things at the same time. Gold is under-booked. And under-booking is not the same as a hidden treasure chest that can cancel liabilities without residue. Residue is the point. Residue shows up in the currency.
If you remember only one line from this whole ramble, make it this: a spectacular official gold price may tell you less about a sudden love affair with yellow metal and more about how many dollars policymakers would need to stand next to the same ounce. That is a colder reading. It is also a more useful one.
The debt number can be made to look smaller. The quantity of dollars and dollar-like claims can be made to look larger. Those dollars may then buy less. There is no magic trick hiding under Fort Knox that lets a country skip that arithmetic. There is only a choice about which ledger the cost appears on, and how loudly the rest of the world hears the choice being made.