
Have you ever watched a commodity story sit still for months, then suddenly look cheap the moment a serious research desk puts a number on it? That is the feeling around this uranium name right now. A large Wall Street bank just started coverage with a bullish rating and a price target that implies more than fifty percent upside from last week’s close. The stock popped a few points on the note. The project itself is still years from first pounds. And that gap, between paper optimism and dirt-moving reality, is exactly where the argument gets interesting.
The Case Behind The Uranium Stock Rally Call
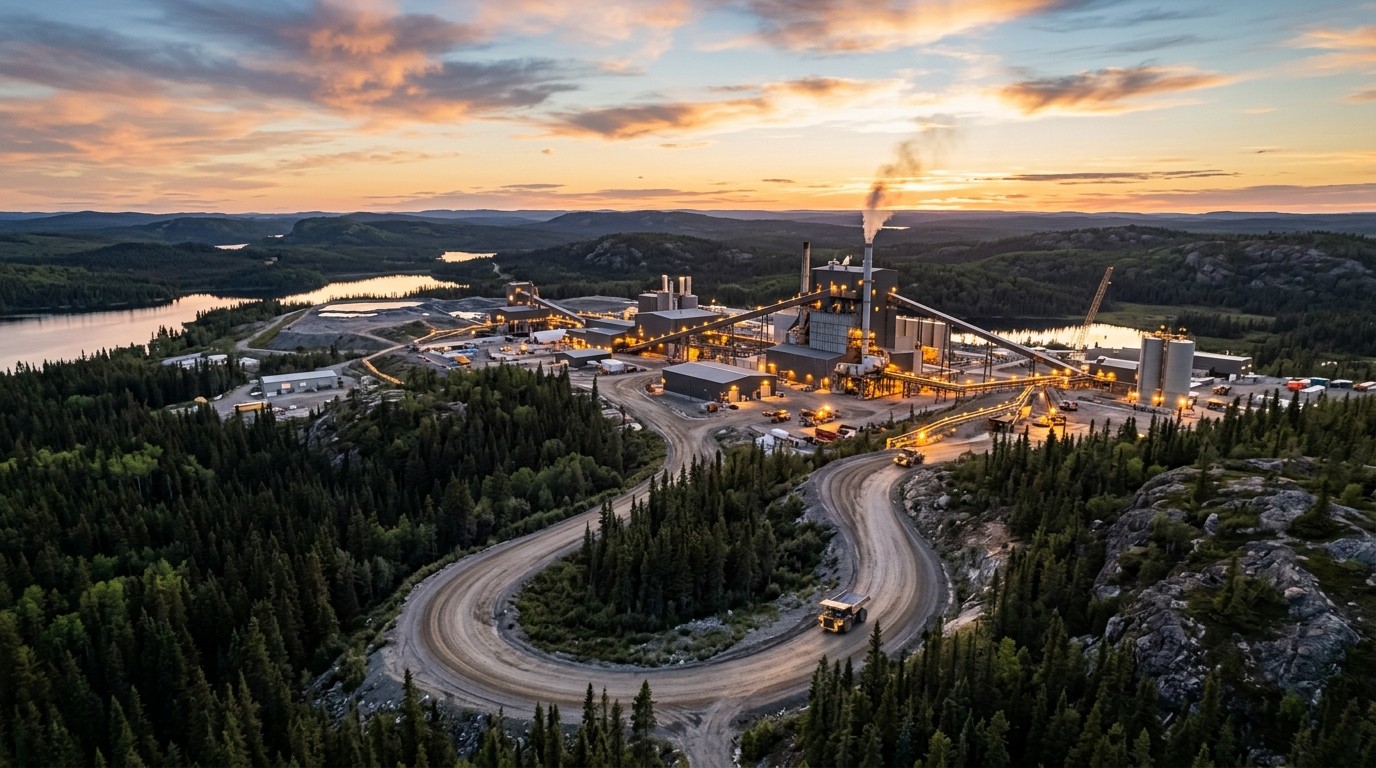
The company in focus is NexGen Energy, a developer building a large high-grade uranium mine and mill in Canada. The flagship is known as Rook I. Management has talked about annual output on the order of 30 million pounds once the operation is running. Completion is framed around 2030. That is not next quarter. It is not even next year. Still, the bank’s analyst argued that the portfolio screens well on three things investors actually pay for in this sector: grade above 2 percent, scale that could represent more than 10 percent of the market, and a jurisdiction that does not keep you awake at night.
I’ve found that uranium coverage often splits into two camps. One camp wants ounces in the ground and a pretty map. The other camp wants permits, funding, and a mine plan that can survive a messy commodity cycle. This note leaned hard into the second camp. The project is described as fully permitted. Funding providers are said to be supportive. Adjacent prospects could stretch mine life across decades if they get folded into the plan. That last point matters more than the headline target. A single high-grade pit is a story. A district that keeps feeding a mill is a business.
While construction is not without risk, headline risk looks longer-dated and valuation looks undemanding, which leaves an attractive risk-reward.
That is the tone of the initiation. Not reckless. Not breathless. Just a claim that the market is not paying enough for a permitted, high-grade Canadian asset with a path to multi-decade life. Street consensus already looks friendly. Every analyst covering the name sits on a buy or strong buy, and the average target implies the shares could more than double from current levels if those models hold. Year to date, the stock has barely moved. That mismatch is catnip for growth-oriented commodity investors.
Why Grade And Jurisdiction Still Decide Uranium Stories
Uranium is not a “any pound will do” market. Utilities care about security of supply. Lenders care about political risk. Equity holders care about whether a mill can stay full when the spot price wobbles. High grade helps on all three. A deposit north of 2 percent is not a rounding error. It can mean less rock moved for each pound of product, lower unit costs if execution holds, and a smaller environmental footprint than a sprawling low-grade pit. In my experience, that combination is what separates a developer that survives a funding winter from one that endlessly issues stock.
Canada is not perfect. Nothing is. Winters are brutal. Indigenous consultation is not a box-tick exercise. Infrastructure in the north is expensive. Even so, the country remains one of the few places where a large uranium project can be built without the same overlay of sanctions risk, sudden tax raids, or export bans that haunt other producing regions. The bank made that point plainly. Jurisdiction is not a slogan here. It is a discount-rate input.
Scale is the third leg. A project that could supply more than a tenth of the market is not a niche explorer. It becomes part of the utility conversation years before first production. Offtake talks, strategic investors, and government interest tend to arrive earlier when the pounds are large and the grade is real. That does not guarantee a premium multiple. It does change who sits across the table.
- Grade above 2 percent can compress operating intensity if the mill is designed well.
- Canadian permitting, already completed on the core project, reduces a classic developer bottleneck.
- Potential market share above 10 percent gives the asset strategic weight with utilities.
- Adjacent prospects create optionality after the first mine plan is locked.
Permitting Is The Quiet Edge Most Investors Underprice
Perhaps the most interesting aspect of the note is not the 50 percent target. It is the comparison with peer projects that are not fully permitted. Uranium developers love to talk resources. Markets eventually talk licenses. A fully permitted mine and mill in a stable country is rarer than slide decks suggest. That rarity is why the analyst called the stock especially appealing relative to other critical-mineral names on the same coverage list.
Does permitting mean construction will be smooth? Of course not. Earthworks slip. Labor is tight. Equipment lead times stretch. Capital budgets have a habit of growing once steel is ordered. The bank did not pretend otherwise. The claim was narrower: headline risk is later, and the starting valuation does not already price a perfect build. That is a different sentence from “this will be easy.”
I keep coming back to timing. 2030 sounds distant until you remember how long nuclear fuel contracting cycles run. Utilities do not shop for pounds the week a mill starts. They line up supply years ahead. A developer that can point to permits, funding support, and a defined mill has a better chance of entering those conversations before first yellowcake hits a drum. That is the real optionality hiding behind a price target.
How The 50 Percent Target Fits The Broader Street View
The new target sits at 14 dollars and was framed as more than 50 percent above Friday’s close. Shares were up nearly 3 percent the following session. That is a polite move, not a melt-up. The market heard the call and did not lose its mind. Fair enough. Construction risk is still sitting on the table.
Consensus is already constructive. Eight analysts, all on the buy side of the ledger. The average target, depending on the data snapshot you use, points to a double rather than a 50 percent bounce. So the new note is not a lonely contrarian shout. It is another institutional voice joining a bullish chorus, with a slightly more conservative number than the loudest targets on the Street.
| Factor | What The Bull Case Emphasizes | What Still Can Go Wrong |
| Grade | High-grade feed supports cost potential | Mill recoveries and dilution can disappoint |
| Permits | Core project described as fully permitted | Conditions, delays, or scope changes |
| Scale | Potential double-digit market share | Ramp-up may take longer than models assume |
| Funding | Supportive capital providers cited | Cost inflation can reopen the funding gap |
| Timeline | Path toward 2030 completion | Construction slip pushes cash flow out |
Look at that grid long enough and you see why the risk-reward language showed up. The upside case is not magic. It is a permitted high-grade asset in Canada with scale. The downside case is the usual developer list: capex creep, schedule slip, and a uranium price that refuses to cooperate when you need it. Neither side is imaginary.
What 30 Million Pounds A Year Would Actually Mean
Thirty million pounds is a big number in this market. Global mine supply is not infinite. A single operation at that scale would be a pillar asset, not a rounding error in a utility’s book. If the mill hits nameplate and stays there, cash flow math changes fast once the build is done. That is why developers trade on optionality for years and then re-rate, sometimes violently, when first production stops being a rumor.
But nameplate is a brochure word. Ramp-up is a living thing. Grades vary by stope. Water management gets complicated. A mill designed for high-grade feed can still choke if the mine plan is optimistic. I would rather investors obsess over the first three years of actual output than over a peak annual figure printed in a presentation. The bank’s note gestured at multi-decade life through adjacent prospects. That is the healthier way to think. First the mine works. Then the district feeds it.
There is also the simple question of who buys the pounds. Nuclear utilities plan on long cycles. They like diversity of supply. A large Canadian producer, once built, is an easy name to put on a short list. That does not mean offtake will be signed at dream prices. It does mean the commercial conversation is plausible, which is more than many earlier-stage deposits can say.
Construction Risk Is Real, Even When Valuation Looks Soft
Let’s not dress this up. Building a mine and mill in northern Canada is a heavy industrial project with weather, logistics, and labor constraints. Steel and skilled trades are not cheap. A schedule that points to 2030 can slide. When it slides, equity holders usually fund the gap. That is the unglamorous part of developer investing, and it does not disappear because a research note used the word undemanding.
Still, there is a difference between risk that can hit next month and risk that sits years out. The analyst’s point was that much of the ugly stuff is longer-dated. Markets sometimes overpay for near-term noise and underpay for distant, high-quality assets. If you believe that framing, a 50 percent target is not a lottery ticket. It is a claim that today’s multiple does not fully reflect a permitted tier-one project.
The stock offers a rare mix of tier-one asset quality and long-dated growth optionality compared with other critical mineral names.
That sentence is doing a lot of work. Tier-one is a worn phrase in mining. Here it is tied to grade, scale, and country. Long-dated growth optionality is the satellite deposits and the chance that the mill becomes a hub rather than a single-asset machine. If those satellites never get integrated, the story is still large. If they do, mine life stretches and the valuation debate shifts from “will they build it” to “how long can they run it.”
Where This Fits In The Nuclear Fuel Cycle Debate
Nuclear energy has crawled back into polite conversation. Power demand from data centers, grid reliability worries, and decarbonization targets all push in the same direction. Uranium is the fuel, not the reactor. The stock in question is a mine developer, not a utility. That distinction gets blurred in social-media threads and should not be blurred here.
A tighter uranium market helps every producer and every advanced developer. It does not finish a concrete pour. It does not hire millwrights. The bull case on this name is a sandwich: structural demand for nuclear fuel on one side, a specific permitted Canadian project on the other. Remove either slice and the target looks softer.
I’ve watched uranium equities trade like a single organism when the spot price jumps. They are not a single organism. Producers with cash flow behave one way. Developers with permits behave another. Explorers with a press release behave a third. This initiation treats NexGen as the second group, and that is the right bucket. You are underwriting a build, not a drill bit.
- Map the project against peers that still lack full permits.
- Stress the capex and schedule, not just the peak production slide.
- Ask how adjacent pounds actually enter the mine plan.
- Watch funding terms as construction spending accelerates.
- Separate uranium price hope from execution milestones.
Valuation Language And What “Undemanding” Usually Hides
Analysts love the word undemanding. Sometimes it means the stock is cheap versus net asset value after a conservative discount rate. Sometimes it means the market is tired and the chart went nowhere while the story improved. Year-to-date performance near 2 percent, against a wall of buy ratings, hints at the second meaning. The asset advanced. The share price did not throw a party.
That can be a gift. It can also be a warning that investors want first steel in the ground before they pay up. Both readings can be true at once. A 14 dollar target is not a promise. It is a model output. Models break when inflation hits the capital budget or when the uranium term price sulks. Anyone buying this name because a single note said 50 percent is doing it wrong. The note is a prompt to re-read the project, not a substitute for that work.
In my view, the cleaner way to use the initiation is as a checklist. Does the market still underappreciate a fully permitted high-grade Canadian mine with district scale? If yes, the target has a landing strip. If you think construction risk should carry a fatter discount until 2028, then 50 percent is a stretch and you wait for a better entry or for milestones that shrink the unknown.
Funding Support Is Not The Same Thing As A Finished Check
The research note highlighted support from funding providers. That is meaningful. Large uranium builds do not happen on retail enthusiasm alone. They need project finance, strategic equity, or a mix that can live with long-dated cash flows. Supportive language from capital providers is a green light, not a closed deal for every dollar of capex.
Watch the mix. Equity-heavy funding can dull per-share upside even if the mine is a technical success. Debt-heavy funding can look elegant until costs overrun. Hybrid structures with offtake-linked support are often the grown-up path in this sector. None of that is in the headline. All of it will show up in future filings.
A subtle personal take: I would rather see a slightly lower headline production target and a funding plan that does not assume a perfect commodity tape. Markets reward mines that get built more than mines that look spectacular in a base-case spreadsheet.
How Investors Might Frame Position Size
This is not a widow-and-orphan holding. It is a pre-production developer with a large prize and a long clock. Position size should respect that clock. A small core holding for investors who already like nuclear fuel exposure can make sense if they are willing to sit through construction headlines. A concentrated bet because a target says 50 percent is how people get educated the hard way.
Time horizon is the other filter. If your horizon is two months, you are trading a research-note bounce. If your horizon is the first half of the 2030s, you are underwriting a mine. Those are different jobs. Mix them up and the stock will feel broken even when the project is fine.
A Practical Reading List For The Next Twelve Months
Ignore the noise around any single session’s 3 percent pop. Track a shorter list. Capex updates. Hiring and contractor awards. Community and regulatory conditions that can still bite after a permit is in hand. Term uranium prices, not just the spot print that dominates headlines. And any shift in how adjacent prospects get described in technical reports. That last item is where multi-decade life either becomes real or stays a slide-deck flourish.
Also watch how peers without permits are valued. If those names start catching this one, the scarcity argument weakens. If the gap stays wide, the initiation’s core claim is still alive.
Simple developer scorecard:
  Permits in hand
  Funding path visible
  Grade that can carry costs
  Jurisdiction that lenders accept
  District pounds behind the first pit
Score four out of five and you have a serious project. Score all five and you understand why a major bank was willing to plant an overweight flag and a double-digit target on a name that has gone almost nowhere this year.
The Human Side Of A Long Build
It is easy to talk about pounds and targets. Harder to remember that a project like this is a community, a workforce, and a multi-year industrial campaign in a cold landscape. Local partnerships are not a footnote. They are part of whether the schedule holds. Investors who treat social license as a soft topic usually rediscover it as a hard delay.
That is one reason the Canadian setting keeps coming up. The rules are demanding. They are also knowable. Knowable beats improvised when you are trying to finance a mill. I would rather own a slower, cleaner process than a faster story that keeps colliding with politics.
Will the stock rally more than 50 percent from here? Maybe. Models say it can. Markets will decide after they see steel, spend, and the first honest construction updates. The initiation did its job. It forced a fresh look at a high-grade, large-scale, permitted uranium project that the tape had treated like background noise. That, more than the precise target, is the part worth sitting with.
If you came for a simple slogan, here is the least-simple version I can offer. This is a long-duration bet on nuclear fuel demand attached to a specific Canadian mine that already cleared a permitting bar many peers have not. The upside case is sizable. The calendar is not short. Treat both facts with the same respect, and the research note becomes useful instead of hypnotic.
And if the shares drift again after the first burst of attention, that would not shock me. Developer stocks do that. They nap between milestones. The question is whether the nap is an opportunity or a verdict. Right now the bank’s answer is opportunity. Your answer depends on how much construction fog you can live with before first production finally shows up on a balance sheet instead of a slide.