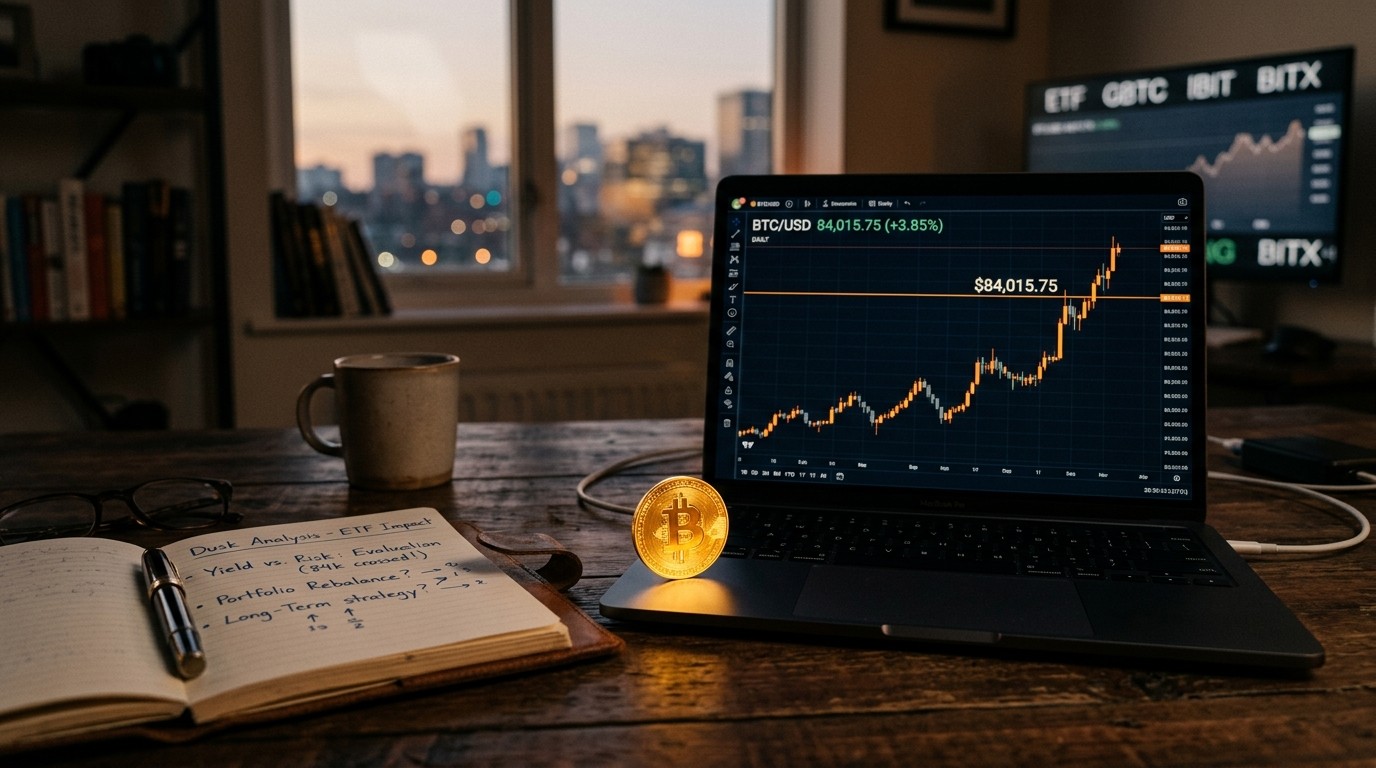

Did you watch Bitcoin slump toward $76,000 and assume the party was over? Plenty of people did. Risk appetite thinned, headlines turned sour, and idle wallets went quiet. Then the tape flipped. Capital drifted back, spot products started taking in money again, and the price punched through $84,000. For a few hours it even flirted higher. That kind of snapback always looks neat in a chart. In real life it leaves holders with a messier question: if the coin can bounce this fast, should it just sit there waiting for the next round?
What The $84,000 Break Actually Changes
A round number is not magic. Traders treat it like one anyway. Crossing $84,000 after a slide toward the mid-$70,000s is less about a single print and more about who showed up. When institutional products start posting fresh net inflows, the market stops feeling like a closed club of exhausted holders. It starts feeling like capital is shopping again.
I have found that these rebounds rarely arrive with a clean story. Geopolitical noise, sticky inflation talk, and shifting rate expectations can knock the same asset down in a week and lift it the next. Bitcoin sits in that awkward middle ground now. Some still call it digital gold. Others treat it as a high-beta growth bet that moves when liquidity loosens. Both camps can be right on different days. That is what makes the current tape so restless.
The latest flow snapshot is the part worth lingering on. After a stretch of strain, U.S. spot Bitcoin products saw money return. One session alone brought in hundreds of millions. A large share went into a well-known issuer’s flagship fund, with another heavy sleeve landing in a rival product. You do not need the ticker symbols to see the point. When two of the biggest wrappers in the space take in cash on the same day, the bid is not a rumor. It is an allocation.
Price can look like a story. Flows are the receipt.
That receipt matters because Bitcoin had just been treated like a risk asset that had to be sold first. When that reflex eases, even a modest thaw in liquidity can travel a long way through a market that already knows how to squeeze. The move from the $76,000 area back through $80,000 and then $84,000 is that kind of travel. It is not a guarantee of a new cycle. It is proof that idle demand was not dead. It was waiting.
Why Holders Stopped Treating The Rebound As Enough
Here is the part that surprised me, and I say that as someone who has watched more than one Bitcoin rally get treated like a finished job. A lot of long-term holders are glad the price is up. They are less willing to let the entire return rest on another green candle. Sitting through a drop toward $76,000 leaves a mark. You start asking whether coins that just sit in a wallet are being used well, or simply stored.
That question is older than this week’s chart. People have tried lending desks, structured notes, staking lookalikes, and more than a few products that promised the moon and delivered a headache. The current conversation is not brand new. It is louder because the bounce arrived quickly and the memory of the dip is still fresh. Nobody wants to feel clever at $84,000 and helpless the next time the tape slips.
So the hunt for idle-asset yield is back on the table. Not because every holder suddenly became a trader. Because waiting has a cost, even when the cost is opportunity rather than an invoice. If Bitcoin is going to spend weeks digesting a level, some people want the coins to work while they wait. Others would rather keep the stack untouched and accept the opportunity cost. Both choices are adult. Pretending only one of them is “real Bitcoin culture” is just branding.
ETF Money, Liquidity, And The Mood Shift
Spot Bitcoin funds changed the plumbing. That is not a slogan. Before those products scaled, a large pool of capital had to wrestle with wallets, custody setups, and internal policy. Now a portfolio manager can express a view inside a familiar wrapper. When that wrapper takes in cash, the underlying market feels it. When it leaks cash, the market feels that too.
The recent inflow burst did not happen in a vacuum. Some of the pressure that knocked risk assets around began to ease. Oil softened at the margin. Rate-policy talk grew a little less one-sided. None of that turns Bitcoin into a savings account. It does change the odds that a dip gets bought instead of abandoned. In my experience, that is how these rebounds usually start: not with fireworks, but with fewer people rushing for the exit.
There is a temptation to treat every inflow day as the start of a straight line to new highs. Resist it. Fund flows can reverse. A single strong session can be followed by two quiet ones. The useful read is the cluster. A market that can attract hundreds of millions after a bruising stretch is telling you that the buyer base is still alive. Alive is not the same as unstoppable. It is still better than empty.
The Holder’s Dilemma After A Fast Recovery
Imagine you bought lower, sat through the slide, and now you are looking at a rebound that recovered most of the damage in a hurry. Do you sell strength? Add? Do nothing? That last option is more popular than people admit. Doing nothing can be a strategy. It can also be inertia wearing a hoodie.
The holders I keep hearing from are not all trying to become miners. They want a cleaner answer to a simple problem. Bitcoin is volatile. Time spent waiting is real. If there is a way to put unused coins or unused capital to work without building a warehouse of machines, they want to understand it. That curiosity is healthy. Blind trust is not.
This is where cloud mining and other automated hash-rate products sneak back into the conversation. The pitch is familiar. You do not buy racks. You do not negotiate power contracts. You buy a slice of computing capacity and hope the payout covers the fee. Daily settlement sounds neat. So does “set it and forget it.” Neat is not the same as safe.
Any product that promises a fat daily check from idle coins deserves more skepticism than excitement. Yield is not a personality trait. It is a risk transfer.
What Automated Hash-Rate Products Claim To Solve
Traditional mining is a business. Hardware ages. Power prices jump. Facilities need staff. Difficulty adjusts. That stack of problems is exactly why some platforms sell contracts instead of rigs. The user picks a plan, locks a budget, and watches a dashboard. Earnings, if they arrive, show up on a schedule. Withdrawals, if they work, go back to a wallet. On paper, that removes the ugly parts of the industry.
On paper is doing a lot of work in that sentence. A contract is only as good as the operator behind it, the energy source feeding it, the reserve policy holding customer funds, and the honesty of the advertised rate. I have seen too many glossy pages that talk about bank-grade firewalls and third-party audits without giving a reader enough to verify. Fancy language is cheap. Proof is not.
Still, the demand is easy to understand. If you hold BTC, ETH, a stablecoin, or a handful of large-cap coins, converting everything into mining hardware is a chore. A platform that accepts several major assets lowers the friction. That convenience is the product as much as the hash rate. Convenience always has a price. Sometimes the price is fees. Sometimes it is opacity. Sometimes it is both.
- Holders want coins to earn something while price consolidates.
- Operators sell access to hash rate instead of physical machines.
- Daily payout language is used to make the product feel tangible.
- The real test is withdrawal reliability, not the landing-page calculator.
A Clear-Eyed Look At Daily Return Claims
Let’s talk about the number that always gets waved around in this genre of content: oversized daily returns. You have seen the style. A headline hints that ordinary holders might pull thousands a day. That line is designed to stop a scroll, not to survive a spreadsheet. Mining economics are public enough that extreme, steady, outsized payouts should make you sit up, not lean in.
Hash price moves. Difficulty moves. Power costs move. Coin price moves. A contract that pretends those variables are optional is selling a story. Perhaps the most interesting aspect is how often the story leans on bonuses, login gifts, and “choose the plan that fits your dream.” Those extras are marketing. They are not a substitute for a transparent fee schedule and a realistic net yield after difficulty adjustments.
If a platform supports a wide list of deposit assets, that can be useful. It can also be a way to widen the top of the funnel. BTC, ether, large-cap alts, and dollar-pegged tokens all attract different users. The more rails you open, the more deposits you can collect. That is not automatically sinister. It is a reason to ask where those deposits go after they leave your wallet.
| Holder Goal | Typical Approach | Main Risk |
| Ride the rebound | Hold spot Bitcoin | Drawdowns after a fast rally |
| Seek extra yield | Hash-rate contracts or similar products | Operator, liquidity, and payout risk |
| Stay flexible | Keep dry powder in trusted custody | Opportunity cost if the tape runs |
How A Careful Holder Would Pressure-Test The Idea
Start with size. If the product only works when you commit a painful share of your stack, walk away. A yield experiment that cannot survive a total loss is not an experiment. It is a bet dressed as infrastructure. I would rather see someone test a small slice, demand a real withdrawal, and keep notes than watch them roll a full bag into a dashboard because a banner said the rebound was the moment.
Then look at the payout path. Daily settlement is only meaningful if the assets actually leave the platform when you ask. Watch the first withdrawal like a hawk. Time it. Check the fee. Confirm the address rules. If support becomes poetic when you mention an exit, you already have your answer. Poetry is for novels.
Next, separate computing reality from brochure reality. New-generation machines exist. Efficient fleets exist. So do rented hashrate markets with visible pricing. If a retail contract implies a cleaner, fatter, more stable result than the open market for a long stretch, ask why the operator is sharing that edge with strangers. Sometimes there is a genuine scale advantage. Sometimes the edge is the deposit.
- Write down the maximum loss you can accept before you click anything.
- Compare the advertised yield with public mining economics, not with wishful math.
- Test a withdrawal early, while the amount still feels small.
- Keep the rest of the stack in custody you already understand.
- Revisit the decision if Bitcoin’s trend or network difficulty changes sharply.
Regulation Talk Versus What A User Can Verify
Many platforms now drape themselves in compliance language. They mention jurisdictions, audits, cold storage, multi-signature setups, firewalls, and asset segregation. Some of that can be real. Some of it is wallpaper. A reader in 2026 should treat every one of those phrases as a claim that needs a document, not a vibe.
Operating “within” a region’s framework is not the same as being a supervised bank. An audit can cover a narrow slice of operations. A cold wallet can hold some assets while hot paths handle the rest. Multi-signature sounds strong until you ask who holds the keys and under what policy they move. I am not saying every operator is sloppy. I am saying the adjectives are doing too much work in this corner of the market.
If a company wants to be taken seriously as a digital-asset manager, it should make the boring details easy to find. Who audits what. How often. What happens in a halt. How customer assets are legally separated if the firm fails. That last item is the one people skip because it is grim. Grim is useful. Grim keeps you from confusing a dashboard with a vault.
Bitcoin As Growth Asset, Not Just A Trophy
One reason this conversation keeps returning is the way Bitcoin is being priced in investors’ heads. After the latest rebound, more desks are willing to treat it as a high-volatility growth asset again. That label cuts both ways. Growth assets can rip when liquidity improves. They can also give back months of gains when the same liquidity tightens.
That is why “holders exploring yield” is not a side plot. If you believe Bitcoin can keep oscillating between fear and feast, you will look for tools that make the waiting room less painful. Some of those tools belong in a serious portfolio. Some belong in a museum of cautionary tales. The job is to tell them apart before the next $8,000 swing teaches the lesson for you.
I keep coming back to a simple bias of mine. Price appreciation is still the main event for most long-term Bitcoin holders. Extra yield is a satellite idea. Satellites can help. They should not become the planet. If a product only looks attractive after you assume both a rising coin price and an unbroken payout stream, you have stacked assumptions. Stacked assumptions collapse together.
What The Rebound Does Not Prove
It does not prove that every dip is a gift. It does not prove that spot funds will keep absorbing supply at the same pace. It does not prove that automated mining contracts are the natural next step for anyone holding coins. Those are leaps. Markets love leaps because they turn a two-week bounce into a personality.
What the rebound does show is more modest, and more useful. Capital can return quickly when the worst of the scare fades. ETF plumbing can transmit that capital into the underlying market. Holders who felt stuck at $76,000 now have options again. Options create behavior. Some will sell into strength. Some will add. Some will look for a way to make unused assets feel productive. That last group should move slowly.
A recovered price gives you room to think. It should not give you a reason to stop thinking.
A Practical Framework For Idle Bitcoin
Split the stack on purpose. One sleeve is the long-term core. That sleeve should live in custody you can explain to a skeptical friend in two minutes. Another sleeve can be opportunistic. That is the only place a hash-rate experiment belongs, if it belongs anywhere. A third sleeve can stay liquid for taxes, life, and the next ugly candle. Ugly candles are not a theory. They are a calendar event that has not been scheduled yet.
Write the thesis in plain language. “I want exposure to Bitcoin’s upside and I am willing to accept drawdowns.” That is a thesis. “I want a dashboard to pay me every day because waiting feels inefficient.” That is a mood. Moods change after one failed withdrawal. Theses can survive a messy month if the size was honest from the start.
Simple sleeve sketch:
  Core hold: coins you can leave untouched through a 30% slide
  Experiment: a small allocation you can lose without rewriting your year
  Dry powder: cash or stable value for fees, life, and bad timing
Notice what is missing from that sketch: a promised daily figure. If the product cannot stand without a headline number, the product is the headline. I would rather under-earn and sleep than over-claim and refresh a support inbox at 2 a.m. That is not romance. That is portfolio hygiene.
Market Context Without The Mythology
Zoom out from the $84,000 print and the picture is mixed, which is normal. Risk assets breathe with policy expectations, energy prices, and the public’s patience for uncertainty. Bitcoin just happens to breathe louder. When those inputs loosen, the same coins that looked heavy at $76,000 can look athletic a few sessions later. When they tighten, the athleticism vanishes.
Fund inflows are the cleanest recent signal that the buyer is not only a leveraged tourist. That does not crown a bull market by itself. It does tell you the rebound had sponsorship. Sponsorship can fade. Until it does, holders get a window to rebalance like adults instead of reacting like a comment section.
Maybe that is the least glamorous takeaway, and the one I trust. The interesting part of this week is not a slogan about turning waiting into a paycheck. It is the reminder that Bitcoin can lose a crowd and then find one again before the narrative writers have finished the funeral draft. If you held through the ugly bit, you already did the hard thing. The next hard thing is not chasing every product that noticed you were relieved.
Where Sentiment And Process Should Diverge
Sentiment likes neat arcs. Process likes checklists. After a rebound, sentiment says the market has chosen a direction. Process asks whether your custody, tax lot, and time horizon still match the position you actually hold. Those are different jobs. Mixing them is how people turn a good bounce into a complicated mess.
If you are exploring automated mining or any similar yield wrapper, keep the language ordinary. You are renting computing risk from a third party. You are not unlocking a secret layer of Bitcoin that the rest of the network forgot. The network is public. The fees are public. The difficulty is public. A private dashboard does not repeal that.
And if you decide the extra complexity is not worth it, that is not a failure of imagination. Plenty of durable holders never touched a contract, a lending desk, or a points program. They bought, secured the keys, and let time argue with the chart. Boring still works. It just does not trend as hard as a promised daily figure.
The Bottom Line For Anyone Sitting On Coins
Bitcoin’s jump back through $84,000 is a real market event with a real flow story behind it. Spot products took in fresh cash. Liquidity conditions looked less hostile. The asset behaved like a high-volatility growth holding that can recover when the selling pressure lifts. That is the news.
The product pitch that often rides along with the news is a different story. Holders can look for ways to use idle assets. They should. Curiosity is rational after a violent round trip. What is not rational is treating an advertised daily payday as the natural companion of an ETF inflow print. One is a market observation. The other is a sales page standing next to the observation and hoping you do not separate them.
So keep the rebound. Keep the lesson from the $76,000 scare. Keep a bias toward things you can verify. If a hash-rate contract still makes sense after that filter, size it like an experiment and demand an exit that works. If it does not make sense, let the coins sit. Watching a chart is not glamorous. Neither is wiring value to a stranger because the last green candle made waiting feel inefficient.
The market will give you another test. It always does. The holders who look steady next time will not be the ones who found the loudest yield slogan this week. They will be the ones who decided, in advance, which coins were allowed to work and which coins were allowed to wait.