
Have you ever looked at your paycheck, done the math in your head, and still felt tight by the middle of the month? That gap between “I earn enough” and “why does this feel so hard” is more common than people admit. In my experience, it is rarely a simple income problem. It is a timing problem dressed up as a money problem.
Bills do not arrive on the same day as your salary. Insurance hits twice a year. A car repair shows up on a Tuesday. A credit card statement lands after a weekend of small purchases that did not feel small when you tapped the card. You are not careless. You are working with delayed information. And delayed information is expensive.
Why A Clear Money Signal Beats Another Financial Product
A well-known budgeting founder has a blunt way of putting it. People tell themselves they make good money. They do make good money. The stress comes from not seeing what that money is already promised to do. The fix is not a fancier card or a flashier savings bonus. The fix is a signal.
A signal is knowing what your money is doing. But you must know what you are trading off.
That line is simple on purpose. Awareness without a trade-off is just a dashboard. A real signal tells you, before you spend, that this dinner is coming out of next month’s car insurance or this upgrade is coming out of the trip you keep saying you want. Once that trade-off is visible, decisions get quieter. Not perfect. Quieter.
Timing Mismatch Is The Hidden Source Of Stress
Paydays and due dates live on different calendars. That lag used to be managed with a checking account and a paper register. Now it is managed with revolving credit, installment plans, and one-click checkout. Those tools are not evil. They just hide the lag. You feel rich on Friday and squeezed on the 17th.
I have found that people who “make enough” still run a silent overdraft in their heads. They borrow from next week without calling it borrowing. A buy-now service or a card with a long grace period makes the borrowing look like normal life. Then the statement arrives and the story changes. The story was always the same. The signal was late.
Think of cash flow like traffic. Income is cars entering the highway. Expenses are exits. If you only look at the on-ramp, you miss the pileup three miles ahead. A signal is the overhead sign that says the exit is coming. You can still take it. You just stop pretending you did not see it.
The Escrow Lesson Most Households Already Know
A mortgage escrow account is an unglamorous example of a good signal. Taxes and homeowners insurance do not show up every month. They show up in lumps. Left alone, those lumps wreck a budget that looked fine in April. An escrow spreads the annual cost into a regular payment. You feel the trade-off in smaller pieces. That is the point.
You can copy that idea without a lender. Split irregular costs across the months they actually belong to. Put a slice of car insurance, gifts, school fees, and travel into a holding place the day income arrives. The account does not have to be fancy. It has to be visible. Visibility is the signal.
- List every bill that does not hit monthly
- Divide the yearly total by twelve
- Move that amount on payday, before lifestyle spending
- Treat the holding balance as already spent
It sounds almost too plain. That is why it works. Fancy systems fail when life gets loud. A plain monthly set-aside still works when you are tired.
Paid Tools Versus Free Tools And The Real Trade-Off
Here is a personal preference I share with that same founder. Paying for a tool can be cleaner than using a free one that monetizes your data. When you pay with money, the cost is obvious. When a product is free, you are still paying. You are just paying with attention, profile details, and a feed of offers you did not ask for.
That does not mean free is always wrong. A free tier can be a smart test drive. It does mean you should name the trade-off out loud. If a budgeting app is free because it wants to sell you refinance ads, that is a product choice. Treat it like one. Ask whether the signal it gives you is worth the noise it adds.
I would rather pay a modest fee for a calmer screen than spend an hour each week ignoring upsells. Other people love a robust free plan and ignore the extras. Fine. The adult move is to pick on purpose.
Zero-Based Budgeting As A Daily Signal
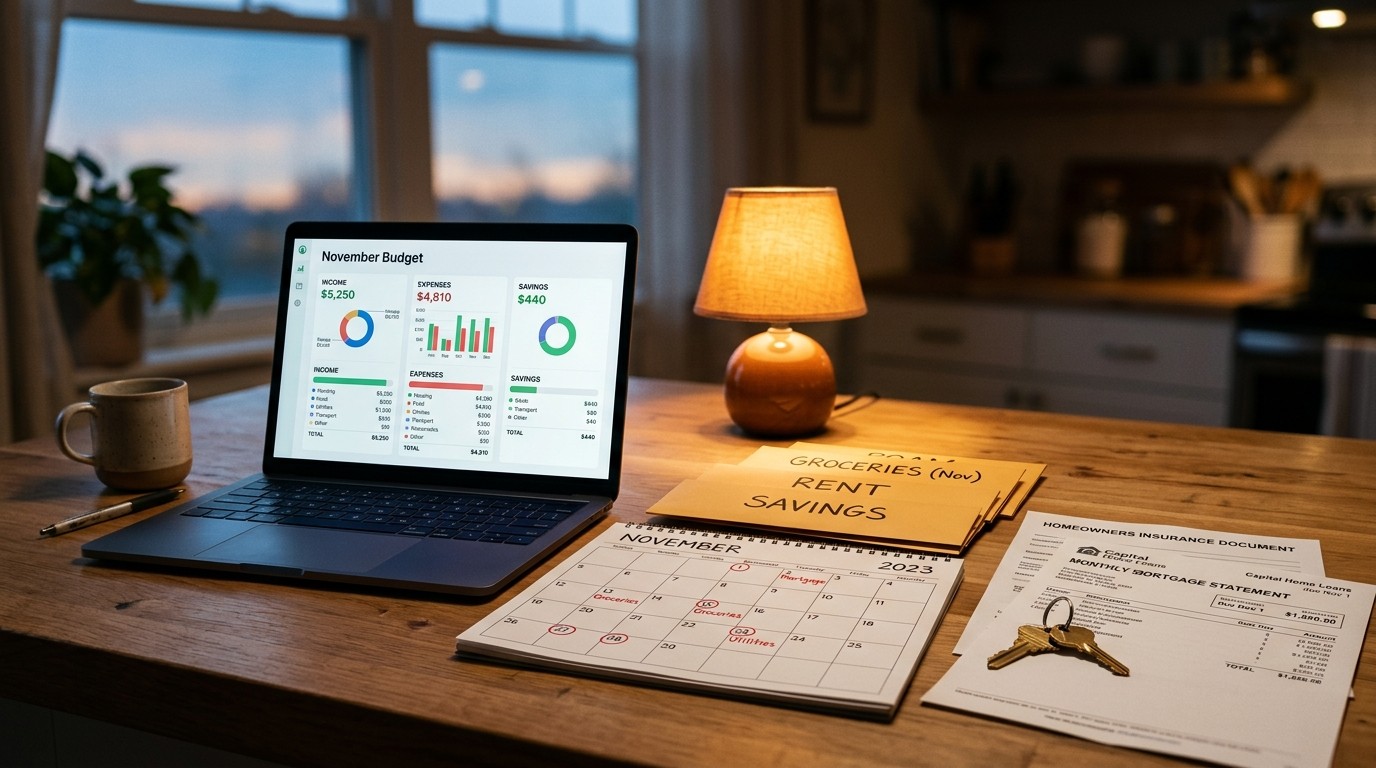
Zero-based budgeting is less a religion than a lighting system. Every dollar gets a job when it arrives. Not next month. Now. Groceries, rent, sinking funds, fun, debt. When the jobs are assigned, leftover money is not a mystery pile. There is no mystery pile.
That method can live in an envelope app, a spreadsheet, or software that asks you to give every dollar a category. The method matters more than the brand. If you overspend groceries, the envelope turns red or the category goes negative. That color change is a signal. It arrives before shame does, which is the whole game.
Some people hate assigning dollars. They want a target number and a hope. Hope is not a signal. Hope is a mood. Moods do not pay the water bill.
Alerts That Arrive Before The Damage
Most cards already let you set a ping when a charge crosses a limit or when a due date is close. Use that. A bill calendar in one place is not exciting. It is useful. Subscription tracking is useful too, because recurring charges are quiet leaks. Quiet leaks sink more budgets than one loud mistake.
Perhaps the most interesting part is how little willpower you need once the ping exists. You do not become a different person. You just get a tap on the shoulder while there is still time to choose. That is cheaper than a late fee and kinder than a lecture from your future self.
- Turn on due-date reminders for every recurring bill
- Set a spend alert at an amount that would surprise you
- Review subscriptions on a fixed day each month
- Cancel anything you would not buy again this week
Automation Is A Signal You Do Not Have To Babysit
Once you decide what money is for, automation keeps the decision from depending on a good mood. Direct a slice of each paycheck to savings before the checking account looks generous. Send another slice to retirement. The remaining balance is what lifestyle gets. That remaining balance is the honest number.
High-yield cash accounts make the parking place less painful. Fees still matter. So does access. An account that pays a solid rate and lets you move money the same day is a working tool, not a trophy. I care more about whether the transfer happens without drama than about a tiny rate difference that I will forget by Thursday.
Automation is not set-and-forget forever. Life changes. Raises happen. Rent jumps. Recheck the splits a few times a year. The first setup is the hard part. The later tweaks are maintenance.
How To Choose A Tool Without Getting Lost In The Aisle
The financial industry is loud. Every product claims to be the one that finally makes money simple. Most of them are solving a feature problem, not an awareness problem. Start with the job you need done.
| Job you need | Signal it should give | Watch-out |
| Stop mid-month surprises | Category balances that update fast | Manual entry fatigue |
| Handle lumpy bills | Sinking funds you can see | Forgetting to refill them |
| Cut quiet leaks | Subscription and due-date list | Fees for extras you will not use |
| Grow cash on purpose | Automatic transfer you notice | Low access when you need funds |
If a tool cannot show a trade-off in under ten seconds, it is entertainment. Entertainment is allowed. Just do not confuse it with a plan.
Credit Cards And Pay-Later Plans Change The Clock
Cards are useful when they are a payment rail, not a lifestyle upgrade. Points can be worth it if the statement is paid in full and the categories are already funded. The minute a card becomes the way you buy time, the signal gets muddy. You spent in March. You feel it in April. The feeling arrives after the fun.
Pay-later plans do the same trick with a friendlier face. Four payments look smaller than one. They are still one purchase. If those installments stack, your future paychecks are pre-assigned and you will not see it until three plans overlap. I have watched careful people get surprised by overlap more than by one big splurge.
A practical rule: if you cannot assign the full purchase to a category today, do not split it into tomorrow. That rule is annoying. It also works.
What Financial Awareness Actually Feels Like
People expect peace to feel like a spreadsheet that never turns red. Real peace is smaller. It is knowing that Thursday’s grocery run is funded. It is knowing the August insurance bill is already sitting in a named bucket. It is knowing that saying yes to a weekend trip means saying no to a gadget, on purpose.
That is not austerity. It is adult taste. You still spend. You spend with the lights on.
Much of the stress around money is about timing, not talent.
When the timing is visible, talent matters less. You do not need a new personality. You need fewer surprises.
A Simple Weekly Rhythm That Keeps The Signal Fresh
Pick one short admin window. Twenty minutes is plenty. Match transactions to categories. Move money into the lumpy-bill buckets. Glance at the calendar for the next fourteen days. That is the whole meeting. If you wait for a perfect Sunday morning, you will skip it. A messy Tuesday night still counts.
Weekly money check:
  1. Assign new income
  2. Cover the next two weeks of bills
  3. Refill sinking funds
  4. Look at one number that still bothers you
The last step matters. If one category keeps breaking, the category is wrong or the life is wrong. Change one of those. Do not shame yourself for a number that never had a chance.
Building An Emergency Buffer Without Making It Abstract
An emergency fund is a signal that future-you will not have to use a card as a parachute. Start with a number that would cover a painful but realistic month. Then grow it. The first thousand is not magic. It is a doorstop. It keeps a broken appliance from becoming a debt story.
Keep that cash boring. Boring is the feature. If the account is too easy to spend from on a whim, put it one transfer away. Friction is a signal too.
Investing Comes After The Lights Are On
Automation into retirement accounts is wise once the monthly machine works. If the monthly machine is on fire, investing can wait a beat. Not forever. A beat. Watching an investment app grow while the checking account is bouncing is a special kind of stress. Get the signal in the operating account first. Then let long-term money do long-term work.
Fees, tax wrappers, and risk all matter. They matter more after you know which dollars are actually free to invest. People skip that order because markets feel like progress. Progress that empties the grocery category is not progress. It is a costume.
Talking About Money Without Turning It Into A Fight
Households break on timing more than on values. One person sees a full checking balance and hears permission. The other person sees the same balance and hears the insurance bill hiding in it. A shared signal fixes more arguments than a shared lecture.
Put the categories on a screen you both can open. Agree on the names. Agree on what “fun” includes. Then let the numbers carry the awkward part. Numbers are less personal than tone. That is a gift.
Common Traps That Kill A Good Signal
- Linking every account and then never opening the app
- Creating thirty categories you will not maintain
- Treating a credit limit as available cash
- Skipping the sinking funds because the month “looks fine”
- Chasing a new tool every time a category goes red
Red is information. It is not a verdict on your character. If you switch tools every time you feel guilty, you will become an expert in onboarding and a beginner at follow-through. Pick a system that is good enough. Stay long enough to learn your own patterns.
A Practical Starter Plan For The Next Thirty Days
You do not need a perfect stack. You need one month of honest tracking and one habit of assigning money on payday. That is enough to feel the difference.
- Write down the next 30 days of known bills
- List irregular costs for the next 12 months and divide by 12
- On the next payday, assign every dollar a job
- Turn on two alerts you will actually read
- Automate one transfer to savings the same day income lands
- Hold a 20-minute review each week
- Adjust one broken category instead of rebuilding the whole plan
Will this make you rich by Friday? No. It will make Thursday less foggy. Foggy is what drains people. Clear is what lets them keep a promise to themselves.
Why This Still Works When Life Gets Messy
Kids get sick. Hours get cut. Travel pops up. A signal does not prevent mess. It shortens the time between mess and response. That shorter gap is the whole advantage. You notice the shortfall while there is still a choice. Choice is dignity. Dignity is underrated in personal finance writing.
I keep coming back to that escrow picture. Nobody loves sending extra money with a mortgage payment. People love not getting flattened by a tax bill in November. The feeling you want is November-in-March. Small payments now. Fewer landmines later.
The Quiet Goal Behind All The Tools
Money management is not a hobby unless you want it to be. For most of us it is infrastructure. Roads should not be interesting. They should get you home. A good budget tool, a plain high-yield account, a calendar of due dates, and a habit of naming trade-offs are infrastructure. Use them. Then go live the life the categories were built to protect.
If you only remember one idea, remember this. Knowing what your money is doing is the signal. The products are just carriers. Choose the carrier that makes the trade-off obvious. Ignore the rest of the aisle until that part is solid. The stress drops after the picture gets clear, not after you download one more app.