
Have you ever watched a project look unstoppable in spring and then, by late summer, start shedding partners like loose bolts? That is the feeling hanging over advanced nuclear right now. A high-profile construction alliance on a Wyoming reactor has come apart, and a planned public listing that was supposed to put fresh capital behind another nuclear name has been pulled back. Nothing here is a full stop. It is messier than that. It is the kind of mid-course friction that tends to show up right when an industry is trying to prove it can deliver on time.
Why This Nuclear Partnership Break Matters Now
The split involves the contractor long associated with large nuclear builds and the developer behind a sodium-cooled design paired with thermal storage. They had been moving toward the next phase of work at a site in Wyoming. Then talks failed. A layoff notice made the break public. The language was polite enough. The companies could not reach an agreement and would move forward separately. Polite language rarely hides the operational headache underneath.
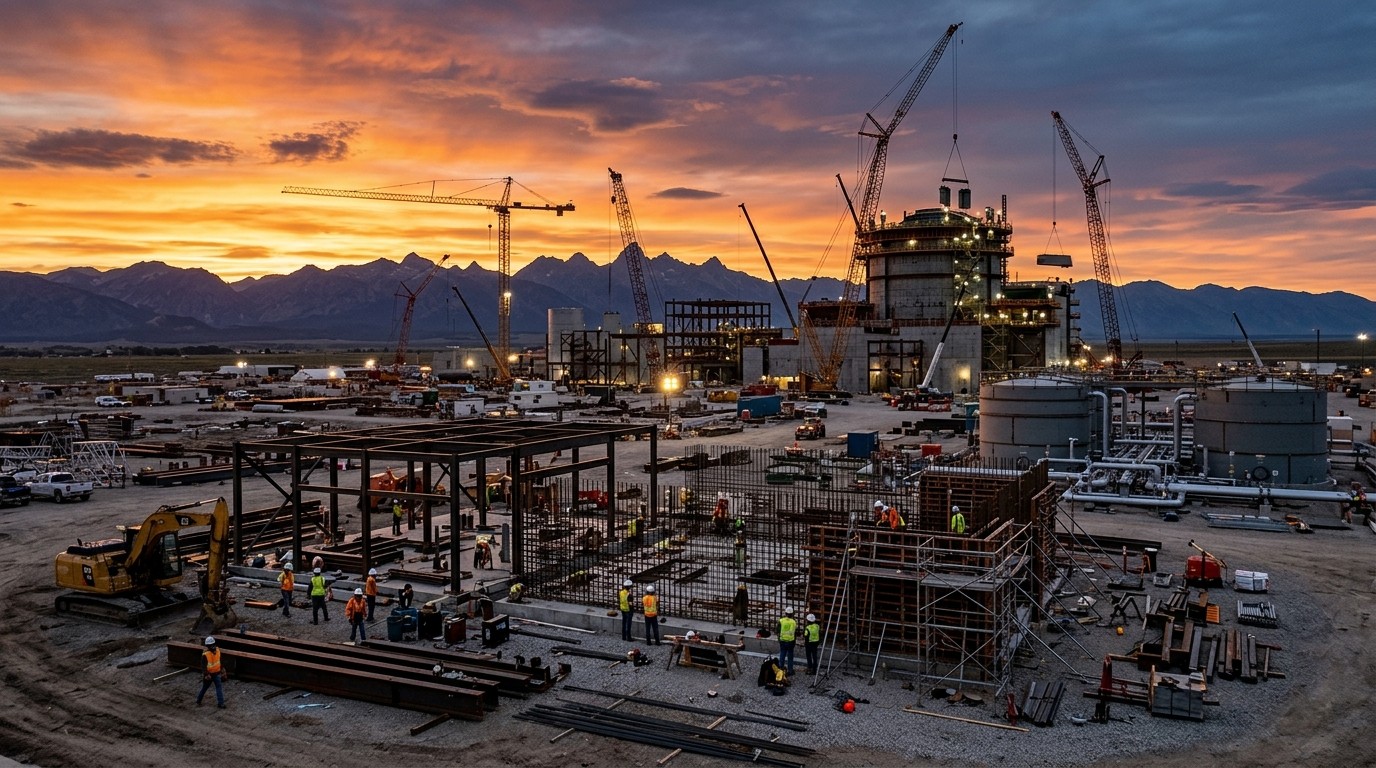
Only months earlier, the same contractor was talking up mobilization and field execution. The developer was still pointing to a completion target around 2030 for a 345 MW plant plus a molten-salt storage system. That target has not been formally abandoned. Construction has not been declared frozen. Still, changing contractors after mobilization is not a tidy handoff. It is more like swapping engines while the plane is already on the runway.
I keep coming back to timing. Nuclear is in the middle of its loudest attempted comeback in decades. Data centers want firm power. Utilities want carbon-free baseload. Policymakers want domestic industrial capacity. In that climate, two of the more visible names struggling to stay aligned looks awkward. It does not kill the thesis. It does test whether the sector can manage people, contracts, and sequencing as well as it manages slide decks.
What The Natrium Design Was Supposed To Prove
The Wyoming plant is not a carbon copy of a 1970s light-water station. The core idea is a sodium-cooled fast reactor tied to a large thermal storage loop. In plain terms, the reactor can keep making heat, store it in salt, and send electricity to the grid when the system operator actually wants it. That pairing is the commercial pitch. Firm power with a little flexibility. Not a battery farm. Not an intermittent plant with a backup story taped on later.
A 345 MW unit is not huge by old utility standards, but it is large enough to matter in a coal-transition county. The site sits in a region that already understands energy work. That local familiarity is an asset. So is the political attention around first-of-a-kind advanced reactors. First-of-a-kind also means first-of-a-kind risk. Licensing, specialized materials, supply chains for sodium systems, and craft labor that can work to nuclear quality all have to line up. When the construction partner changes, those lines get redrawn.
Changing the builder after mobilization is rarely just a paperwork event. It is a schedule event, a culture event, and often a cost event.
In my experience watching infrastructure programs, the quiet period after a contractor exit is when the real damage either gets contained or starts compounding. Vendors wait. Subcontractors renegotiate. Field supervisors leave. Design packages that were “almost issued” suddenly need another set of eyes. None of that shows up in a press line about moving forward separately. All of it shows up later in the critical path.
The Short List Of Firms That Can Actually Finish This
There is a large construction industry in the United States. There is a much smaller group that can run nuclear-grade engineering, procurement, and construction without learning on the owner’s dime. That distinction matters more than people admit on conference panels.
On the domestic side, one obvious name sits just behind the outgoing contractor in nuclear pedigree. That firm has already been circling other advanced reactor work, including early planning around a multi-unit development at an industrial site in Texas. That kind of adjacent experience helps. It does not automatically mean a clean drop-in replacement for a sodium plant in Wyoming. Different technology. Different vendors. Different quality program. Different union and craft mix.
A stronger candidate on paper may sit overseas. A major Korean engineering and construction group already has a framework deal with the same developer for as many as eight future units. That agreement was built around completion, price, and performance guarantees meant to make project finance less frightening. If the first unit in Wyoming becomes the proving ground for that relationship, the split with the current U.S. contractor looks less like an accident and more like a pivot toward a model investors can underwrite.
- Domestic nuclear EPC capacity is thin once you demand real plant experience.
- Guaranteed price and schedule terms are becoming as important as technical design.
- Repeatable fleets matter more than a single demonstration unit.
- Craft labor and nuclear quality culture cannot be improvised in a hurry.
Perhaps the most interesting aspect is how quickly the developer locked an international partner for later units while the first unit was still tied to a different builder. That can be smart portfolio management. It can also create tension on the first site if two construction cultures start overlapping. Owners hate dual command. Field teams hate it more.
Holtec’s Shelved Listing Adds A Second Jolt
The contractor split would have been enough news for one week. Then came the postponed offering from a company that has been trying to restart an existing plant and sell a small modular design at the same time. The deal had been marketed around 50 million shares in a $15 to $18 range, which implied a raise that could have approached $900 million if pricing held at the top. It did not get that far.
Management pointed to weaker investor mood and uncertainty around data-center development. That last phrase is doing a lot of work. For two years, nuclear stories have been welded to the idea that artificial intelligence campuses will buy every spare megawatt. Some will. Some already are signing letters and term sheets. The market, at least this month, decided the path from letter of intent to contracted offtake still looks foggy.
The company said it would keep the registration statement on file. Work on the plant restart and the modular program would continue. That is the correct public posture. It is also a reminder that public markets can slam the window even when the underlying industrial plan is still alive. Private capital can fill gaps. It usually does so with tighter covenants and less patience.
| Company Focus | Near-Term Issue | What Still Moves Forward |
| Advanced sodium plant | EPC partner change | Site work and 2030 target talk |
| Plant restart plus SMR | IPO postponed | Restart program and design work |
| Broader nuclear sector | Investor selectivity | Policy support and offtake talks |
Data Centers Changed The Story, Then Complicated It
Let’s be honest. A lot of the recent nuclear enthusiasm was not born in utility integrated resource plans. It was born in load forecasts that suddenly jumped because server halls want power that does not blink. That demand is real. The contracting is slower than the headlines. Interconnection queues, transmission upgrades, water, land, and local politics still sit between a campus rendering and a commissioned substation.
When a nuclear issuer cites data-center uncertainty as a reason to wait on an offering, the market is saying something useful. It is saying the offtake story is not yet standardized. Some campuses want behind-the-meter supply. Some want grid power with a clean attribute. Some want a reactor next door in ten years and a gas turbine next year. Those are not the same credit. They should not price the same.
I’ve found that energy investors can tolerate technology risk or counterpart risk. They get jumpy when both arrive in the same slide. Advanced reactors still carry first-of-a-kind technology risk. Hyperscale offtake still carries timing risk. Stack them and the cost of equity rises even if the long-term need for firm clean power is obvious.
Construction Reality Versus Revival Narrative
Nuclear comebacks fail in the field more often than they fail in the lab. That is an old lesson and it remains unpaid. Welding procedures, module yards, quality documentation, and the simple availability of experienced supervisors decide whether a 2030 date is a plan or a wish.
The Wyoming project had already moved from concept into mobilization. That is further than most advanced designs ever get. Losing alignment with the builder at that stage does not erase the progress. It does reset parts of the execution model. New contractors want their own construction sequence. They want their own vendor list. They want their own contingency. Owners who try to keep every prior decision locked in usually pay twice.
Is a replacement even available at speed? Yes, in theory. No, if the standard is “same people, same productivity, next Monday.” Nuclear craft markets are tight. Travelers move toward the job that looks most certain to keep running. A public dispute, even a polite one, can slow that flow. I would rather see an owner spend three extra months choosing the right replacement than six extra years living with the wrong one. Schedule pride is expensive.
Why International Guarantees Suddenly Look Attractive
Western nuclear projects have a reputation problem on cost. Fair or not, lenders remember overruns. That memory is why completion guarantees, wrap structures, and export-credit support keep entering the conversation. A contractor willing to stand behind price and date changes the bank meeting. It does not remove risk. It relocates it to a balance sheet that investors understand.
That is the quiet logic behind looking abroad for the next builder. Serial construction in other markets created muscle memory. Standardized designs. Fabrication shops that have already made the same module more than once. If the Wyoming unit becomes the first brick in a fleet covered by those terms, the partnership break may be remembered as the moment the commercial model got serious. If the handoff slips, it will be remembered as lost time on the only date that matters: first power.
What Investors Should Watch Over The Next Year
Ignore the urge to treat every personnel notice as a thesis killer. Watch the boring indicators instead. Who signs the next EPC package. Whether the nuclear regulator’s review calendar stays intact. Whether major equipment orders continue. Whether local hiring notices resume after the contractor change. Those are the tells.
- Confirm a replacement builder with nuclear-quality credentials and a clear scope split.
- Watch whether the 2030 language survives the first quarterly update after the split.
- Track whether modular vendors keep fabrication slots or start sliding them.
- See if the postponed issuer returns to market after offtake news, not just after a better tape.
- Compare contracted power talks against actual interconnection milestones.
A postponed listing is not a death certificate. Plenty of industrial companies wait for a cleaner window. The risk is different. Waiting can become a habit if the underlying contracts do not tighten. Markets forgive delay when the order book improves. They punish delay when the story stays the same and the cash burn continues.
Policy Tailwinds Do Not Pour Concrete
Credits, loan programs, and political speeches still favor new nuclear. That support is meaningful. It lowers the cost of capital and keeps first projects from dying in committee. It does not weld pipe. It does not qualify a procedure. It does not settle a commercial dispute between an owner and a builder.
This is where a lot of commentary gets sloppy. People treat policy as a substitute for execution. It is not. Policy is a tailwind. Execution is the boat. If the crew changes mid-lake, you still have wind. You also have a new captain who needs charts, tools, and a crew that will take instructions.
Communities near these sites tend to be more practical than social media. They want payrolls, tax base, and a plant that actually runs. They have lived through boom-and-bust energy cycles before. A contractor split will be judged locally by whether layoffs linger and whether trucks keep rolling through the gate. That local test is as important as any national narrative about energy abundance.
The Talent Bottleneck Nobody Romanticizes
Ask people who have built nuclear plants what actually runs out first. It is not slogans. It is senior discipline engineers, quality inspectors, and superintendents who have closed out a system before. Those people are finite. When two high-visibility nuclear efforts wobble in the same news cycle, some of that talent starts taking calls from gas, data-center, or transmission jobs that look simpler.
I do not think the sector loses the decade because one alliance ended. I do think it can lose months it does not have. 2030 is not a mystical number. It is a date that sits inside political cycles, tax-credit windows, and corporate power-purchase calendars. Miss it by a little and the model still works. Miss it by a lot and the first unit becomes an expensive classroom instead of a product.
The nuclear revival will be decided by weld maps and contract exhibits, not by the volume of keynote speeches.
How A Contractor Change Can Still Be The Right Call
Not every split is a failure of vision. Sometimes it is the opposite. An owner looks at the next phase, looks at the commercial terms on the table, and decides the relationship will not survive first concrete. Better to break before the most expensive work than during it. That logic is cold. It can also be correct.
The test is successor quality. If the next firm brings a tighter wrap, a deeper bench, and a fabrication network that already exists, the project can come out stronger. If the next firm is simply the available body in the room, the owner has bought time and sold certainty. Readers should be skeptical of any statement that treats contractor identity as a detail. In nuclear, the builder is part of the technology.
There is also a cultural piece. Sodium systems, salt loops, and conventional nuclear quality programs do not automatically speak the same shop language. Integration is a management product. Somebody has to own the interfaces. When companies “move forward separately,” the interface owner has to be named quickly. Or the interfaces start owning the schedule.
Public Markets Are In A Show-Me Mood
The postponed offering fits a broader pattern. Investors will pay for operating cash flow, contracted megawatts, and plants that already exist. They are less eager to underwrite a story that still depends on a chain of future approvals and future customers. That is not hostility to nuclear. It is basic cycle behavior after a crowded trade.
Companies that need public equity anyway will have to arrive with sharper offtake, clearer construction partners, and fewer open design questions. That bar is higher than it was when every presentation led with artificial intelligence demand. Fine. Higher bars produce better projects. They also leave some issuers waiting longer than their cash models assumed.
What still supports the nuclear case:
  Firm clean power demand is rising
  Existing fleets are getting life extensions
  First advanced units are in the field, not just on paper
  Policy tools remain constructive

What can still break individual names:
  Contractor churn
  Soft offtake conversion
  Public-market windows that close
  Craft and quality staffing gaps
A Ground-Level Read On Wyoming And Beyond
Stand in a place that used to run on coal and the abstract debate changes. People there do not need a lecture on energy density. They need to know whether the next plant pays local wages and whether the lights stay on when the wind drops. A sodium reactor with storage is, on paper, a good fit for that question. Paper is not a turbine hall.
If site activity continues after the partnership change, the story remains one of friction inside a live project. If activity thins out while lawyers and commercial teams renegotiate, the 2030 date starts to look decorative. Watch the parking lot. It is an underrated research tool.
Elsewhere, restart campaigns and small modular programs will keep trying to show that nuclear can be a product line rather than a custom monument. That is the right ambition. Product lines need factories, repeat contracts, and builders who stay for more than one unit. A framework for eight future plants is more important than a single ceremony. Only if the first one gets built.
The Uncomfortable Middle Of A Comeback
Revivals are ugly in the middle. Early excitement is cheap. Late success looks inevitable. The middle is where contracts crack and offerings slip. That is the stretch nuclear is in. It is also the stretch that separates serious industrial efforts from theme-park narratives.
I do not read this week as proof that advanced nuclear was a mirage. I read it as proof that delivery still has veto power over enthusiasm. The sector can absorb a contractor change. It can absorb a delayed listing. It cannot absorb a habit of treating those events as unimportant. They are important. They are also survivable if the next signatures are better than the last ones.
So where does that leave a reader who cares about energy markets rather than press cycles? Stay long the need for firm power. Stay picky about who can pour the concrete. Ask who holds the performance wrap. Ask who the customer is after the memorandum expires. Ask whether the people who were on site in April are still on site after the breakup. Those questions are not glamorous. They are how you avoid confusing a comeback with a completed plant.
The next chapter will not be written by another round of optimism. It will be written by a replacement builder, a revised schedule, and, for one issuer, a decision about when the public window is real again. Until those items move, the nuclear story remains intact and a little more adult than it was last spring. That is not the headline people want. It may be the one the industry needs.