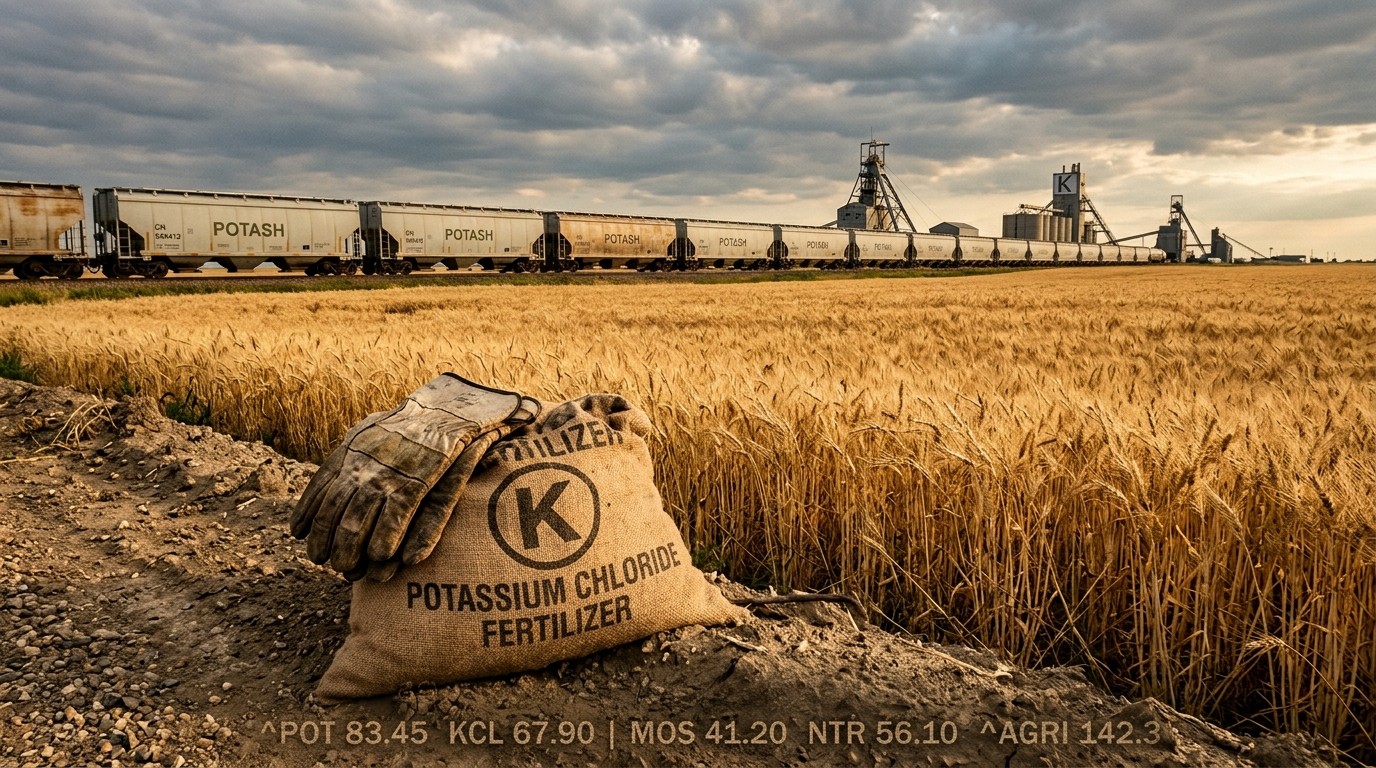

I still remember the first time a farm-input headline moved a stock faster than a crop report. It was not a drought. It was not a surprise harvest. It was a sentence about potash, dropped before lunch, and the tape treated it like a weather event. That is what happened again when a presidential post said Washington was working on a massive purchase of potash from Belarus, at prices well below what U.S. buyers have been paying for Canadian supply. Fertilizer names slipped to session lows almost on contact. Farmers heard cheaper nutrients. Equity desks heard a price cap.
Why One Potash Headline Shook Fertilizer Stocks
Potash is not a glamorous ticker. It is potassium chloride in railcars, barges, and warehouse piles. It is the nutrient that keeps corn from lodging and soybeans from looking tired in August. When the cost of that nutrient drops, growers breathe easier. When traders think the cost of that nutrient will drop for years, producers of the stuff lose pricing power. That simple split explains the morning selloff better than any slogan.
The message itself was short. The United States, it said, was working on a large deal to buy potash from Belarus. The pricing would be substantially lower than current Canadian levels. Farmers and ranchers were named as the winners. Markets did not wait for a contract, a volume, a delivery window, or a port schedule. They marked down the companies that live on the spread between mine cost and farm-gate price.
The United States is working on a massive Deal with respect to the purchase of Potash from Belarus. The pricing would be for substantially less than we are currently paying to Canada, very good news for our Farmers and Ranchers.
Shares tied to potash and broader fertilizer production slipped in a hurry. Names associated with North American potash mining and nitrogen production all felt the same first impulse: if a cheaper official channel opens, the old price deck looks less safe. In my experience, that first impulse is rarely the whole story. It is the opening bid.
What The Tape Did In The First Hour
Session lows arrived before most lunch orders. One domestic potash miner dropped around four and a half percent. A major phosphate and potash producer fell by a similar amount. A leading nitrogen company lost more than three percent even though nitrogen chemistry is not the same as potassium chloride. That last move is telling. Traders sometimes sell the whole fertilizer complex when they hear “cheaper nutrients,” then sort the details later.
Other large North American producers also traded heavy. The market did not need a full term sheet. It needed a credible threat to the Canadian price reference that has shaped U.S. farm costs for years. Canada has long supplied the overwhelming majority of U.S. potash imports. Change that reference, even as a possibility, and the valuation math shifts.
| Theme | First Market Read | Open Question |
| Headline supply deal | Lower potash prices | How many tons, and when? |
| Farmer benefit | Cheaper input bills | Does the saving survive logistics? |
| Producer equities | Margin compression | Is this structural or one cargo? |
| Trade politics | Canada leverage play | Will exemptions hold? |
Canada Still Sits At The Center Of U.S. Potash
Geography is stubborn. Saskatchewan holds enormous reserves. Rail lines already run south. Contracts already exist. Elevators already know the product. That is why U.S. farms have leaned on Canadian potash for decades, often in the range of four fifths to nine tenths of import needs depending on the year and the data set you trust.
Recent tariff rounds made the relationship look more fragile than the chemistry. Duties of fifty percent landed on a range of Canadian goods after talks stalled. Energy and potash still received important carve-outs. That exemption was not charity. It was recognition that a tariff on potash becomes a tax on Midwestern planting almost immediately. You can argue about autos for months. You cannot plant without potassium and wait for a court date.
So the new Belarus talk sits inside a trade fight, not beside it. If the goal is cheaper farm inputs, a sanctioned-then- unsanctioned supplier is a bargaining chip. If the goal is to remind Ottawa that Washington has options, the chip is political as much as agricultural. Markets priced both motives at once.
Belarus Has Tons. Delivery Is The Hard Part.
Belarus is not a bit player. Before the latest cycle of restrictions, it accounted for a large slice of global potash output, often cited near one fifth of world supply in stronger years. State-linked producers sit on long-life deposits. The product is real. The question is not whether the mineral exists. The question is whether it can move west in volume, on time, at the advertised discount, without breaking other contracts.
That is where the story gets messy. A senior Belarusian official was quoted as saying the country lacks spare capacity to supply the West in a meaningful extra wave. Much of the year’s output can already be spoken for. Rail paths that once ran through Baltic ports have been constrained. Cargo has been pushed onto Russian corridors where other shippers also need track. Paperwork can be cleaned. Steel wheels still need a slot.
I’ve found that commodity headlines die in logistics more often than they die in politics. A “massive deal” that cannot clear a port is a press note. A “massive deal” that arrives in New Orleans or a Great Lakes terminal in time for spring application is a market event. Until someone names vessels, terminals, and monthly tons, treat the first selloff as a probability adjustment, not a finished forecast.
- Mine output is not the same as exportable surplus.
- Existing contracts to Asia and Latin America can absorb product first.
- Transit routes remain the bottleneck after sanctions relief.
- Quality specs and bagging standards still have to match U.S. dealer habits.
- Seasonality matters: potash sitting in a warehouse in July is not potash under a planter in April.
Sanctions Relief Already Changed The Chessboard
This post did not arrive in a vacuum. Over the past year, Washington eased restrictions on Belarus-linked potash companies and certain financial channels. The policy mix included prisoner releases on one side and fertilizer access on the other. Officials framed the shift as practical help for growers facing expensive nutrients after other global shocks tightened nitrogen and phosphate flows.
Once those companies left the prohibited list, traders began to model a world in which Belarusian material could legally touch U.S. counterparties again. Legal permission is step one. Banking, insurance, and freight are steps two through ten. Still, the permission alone was enough to put a ceiling in the back of every producer model. Monday’s comment simply made that ceiling louder.
Perhaps the most interesting aspect is how quickly farm politics and great-power politics now share a spreadsheet. A nutrient that used to live in agronomy guides now lives in sanction annexes. That is not a comfortable place for a bulk commodity. It is, however, the place we are in.
Farmers Hear Relief. Producers Hear A Price Cap.
Walk a Midwestern coffee shop after a fertilizer spike and you will hear the same sentence in different accents: inputs are eating the crop. Potash is only one line on that invoice, sitting beside nitrogen, phosphate, diesel, seed, and interest. Even so, it is a line growers notice because it is hard to substitute. You can tweak rates. You cannot wish potassium into the soil.
A credible discount versus Canadian supply would matter at the farm gate. It would also matter in cash-rent negotiations and in the willingness of lenders to stretch operating lines. That is the bull case for rural America in this headline. It is clean. It is popular. It is incomplete.
Producers look at the same sentence and see a bid that undercuts the North American benchmark. Potash is globally traded. Extra low-cost tons do not stay neatly in one customs district. They leak into the price discovery process. If Belarusian product lands at a visible discount, Canadian and U.S. miners face a choice: match it, lose share, or idle high-cost capacity. Equity markets priced the first two options first.
Cheaper nutrients can be a gift to the field and a haircut to the mine in the same week.
Why Nitrogen Names Moved With Potash Miners
CF-style nitrogen producers do not mine the same rock. They make ammonia, urea, and related products. So why did those shares slip too? Because fertilizer desks often trade a mood. If official Washington is hunting cheaper farm inputs, the whole complex can look less like a scarcity story and more like a political price target. That is sloppy analysis on a quiet day. On a headline day it is how risk gets booked.
There is a tighter link as well. Growers budget a nutrient package, not a single molecule. If potash costs fall and cash is freed, some of that cash can shift toward nitrogen timing. Some of it simply repairs margins. Either way, the sector beta rises when policy talks about “massive” fertilizer deals. I would rather see investors separate the chemistries by afternoon. In practice, they often wait until the second session.
The Canadian Price Reference Is The Real Battlefield
Listen closely to the wording. The discount was defined against Canada, not against a floating global index. That is the tell. The political comparison is bilateral. The market comparison will not stay bilateral. Once a number is named as “substantially less,” every procurement manager in the Corn Belt has a talking point for the next bid cycle.
Canadian supply remains the practical backbone. New mine phases in Saskatchewan are still the long-cycle answer to Western Hemisphere demand. A large greenfield project is moving toward late-decade output measured in millions of tons. That is the structural story. Belarus is the swing story. Swing stories move stocks. Structural stories move decades.
Could Ottawa restrict exports in a deeper trade fight? In theory, yes. In practice, that would be an agricultural weapon aimed at a customer who also buys a mountain of other goods. It would also invite the exact search for alternatives we are watching now. Both capitals know that. That is why exemptions keep appearing even when the rhetoric gets loud.
Capacity Claims Versus Contract Reality
Here is the part that should slow the victory lap. A producing country can be large and still be sold out. Annual mine plans get committed to Brazil, China, India, and other repeat buyers. Diverting cargoes is possible. Diverting them without paying liquidated damages, irritating long-term clients, or starving another region is harder. “We would like to sell to the West” is not the same sentence as “we have uncommitted ships this quarter.”
That official skepticism about spare capacity should sit next to the presidential optimism, not under it. Markets hate two official narratives at once. They usually resolve the conflict by fading both until freight data appears. Watch rail loadings, Black Sea and Baltic alternative routes, and U.S. import manifests more than adjectives.
Deal checklist investors can actually use:
  1. Named annual tonnage
  2. Delivery months aligned to U.S. application
  3. Price formula versus Canadian benchmark
  4. Financing and insurance confirmation
  5. Repeat-year option, not a one-off cargo
How Growers Should Read The Next Ninety Days
If you run acres, do not rebuild a whole fertility program on a social post. Do ask your retailer whether any Belarusian-origin product is being offered, at what spec, and with what delivery guarantee. Do compare that net price with your usual Canadian-origin quote after freight, blending, and application timing. The farm-gate number is the only number that pays the note.
Also remember that cheaper potash does not automatically mean a better year. Crop prices, weather, and nitrogen still dominate most budgets. A twenty dollar move in potash can matter. A fifty cent move in corn can matter more. Keep the nutrient in proportion even when the politics get noisy.
- Ask for origin, not just a delivered price.
- Lock timing before you celebrate a discount.
- Stress-test your plan if the cargo slips a month.
- Do not assume next season inherits this season’s headline.
How Equity Investors Should Separate Noise From Thesis
For stock pickers, the first question is duration. Is this a one-time political cargo designed to make a point in a trade argument? Or is it the start of a multi-year procurement channel that resets North American netbacks? The first case is a trading dip. The second case is a multiple reset for miners with high operating leverage to potash prices.
Balance sheets matter here. A producer with low net debt and flexible mines can idle and wait. A producer with heavy sustaining capex and a market that suddenly doubts the price deck will look more fragile. Nitrogen-heavy names should be judged on gas costs and ammonia spreads, not on a potash rumor, unless management guidance starts bundling the whole nutrient suite into one caution.
In my experience, the cleanest way to stay honest is to write two columns on a pad. Column A: tons that can physically arrive before the next application window. Column B: political language. Trade Column A. Read Column B. Do not confuse them.
Global Price Discovery Will Not Stay In One Country Pair
Potash buyers in Brazil and Southeast Asia already live with a three-way supply map: Canada, Russia, and Belarus, plus smaller sources. If Washington becomes a visible bid for Belarusian tons, other buyers notice. They may bid to keep cargoes. They may demand matching discounts. The result can be a softer global marker even if U.S. arrivals stay modest. That is how a “domestic farm story” becomes a worldwide equity story.
It also cuts the other way. If Belarus cannot actually spare the tons, the global marker firms again and the Monday dip looks like an overreaction. Both outcomes are live. That is why conviction should stay humble until shipment data shows up.
The Political Discount Has A Hidden Premium
There is a cost that never appears on a fertilizer invoice. Buying a strategic nutrient from a tightly controlled state producer creates future optionality for the seller. Today the pitch is cheap potassium. Tomorrow the pitch can be leverage. That does not mean the purchase is foolish. It means the discount should be large enough to pay for political uncertainty, not just freight.
I do not say that as a lecture. I say it as a risk manager. Agricultural supply chains already learned this lesson with other inputs after 2022. Concentration feels efficient until the corridor closes. Diversification feels expensive until the corridor closes. The smart posture is neither purity nor panic. It is a book of origins.
What Would Confirm The Bear Case For Miners
Confirmation would look boring on a calendar and violent on a price chart. Multi-quarter U.S. import prints showing a rising Belarusian share. Retail quotes in Iowa and Illinois that gap down versus last year’s Canadian-origin offers. Guidance from listed producers that mentions “incremental competitive supply” without a matching cut in industry operating rates. Those are confirmations. A single post is not.
If those prints arrive, the market will not need another speech. It will grind the spot price lower and force high-cost tonnes off the board. That is classic commodity hygiene. It is painful for equity holders who bought scarcity and received policy.
What Would Rescue The Producer Thesis
Rescue would also look dull. Belarusian officials keep saying there is no spare product. Manifests stay thin. Canadian rail remains the workhorse. Spring demand firms. And the political deal, if it exists, turns out to be a modest book of cargoes rather than a new pillar of U.S. fertility. In that world, Monday’s dip is a gift for patient holders who wanted a cheaper entry into an oligopolistic nutrient market.
Domestic projects still matter in that rescue case. A U.S. mine that can actually run, and a Canadian expansion that hits its start date, reduce the need to turn every diplomatic opening into a supply panic. Self-help is slower than a headline. It is also harder to revoke.
A Practical Framework For The Week Ahead
Do not hunt for certainty on day one. Hunt for documents. Is there a memorandum of understanding? A tender? A trader mandate? A credit line? Those objects are not romantic. They are how bulk commodities move. Without them, the story is still a speech.
Watch the second session as closely as the first. Headline selloffs often reverse a slice of the loss when desks remember logistics. They also deepen when a follow-up comment adds volume numbers. Either path is information. Sitting on your hands for one extra close is allowed. In fact, it is often the professional move.
Policy can reprice a sector before a single extra railcar is loaded. The railcar is still the fact that matters.
The Human Layer Under The Tickers
It is easy to treat this as a screen sport. It is not only that. A grower in Nebraska does not care which capital wins the talking point. That grower cares whether the blended product shows up before the applicator leaves the yard. A mine worker in Saskatchewan does not care about a phrase on a social platform. That worker cares whether the mill runs Saturday overtime. Both lives sit under the same potassium atom.
That is why I keep coming back to tone. Celebrate cheaper food production if the tons are real. Do not pretend a diplomatic bargain is the same thing as a warehouse full of granular product. The country can want both farm relief and reliable allies. Markets will force a sequence. Sequence is strategy.
Closing Read: Treat The Discount As A Hypothesis
So where does that leave a reader who has to act? Treat the promised Belarus discount as a hypothesis with a high political probability and an unproven physical probability. Price a little extra supply into models. Do not blow up a long-term producer thesis on adjectives. Do not ignore the farm-gate upside if cargoes actually clear. Hold both thoughts. Adult markets do that all the time.
The morning drop in fertilizer stocks was rational as a first draft. First drafts get edited by freight, contracts, and weather. If you only remember one line, remember this: potassium does not trade on speeches. It trades on tonnes that can be weighed. Until those tonnes show up, the headline is a warning light, not a finished map.
And if the tonnes do show up at the advertised discount, the map will change fast. Farmers will lock product. Retailers will reset quotes. Miners will defend share or cut rate. That is the chapter still unwritten. It is also the chapter worth waiting for, because it will be written in railcar counts rather than capital letters.