
Have you ever watched a listing so crowded that the bid book starts to look like a concert queue rather than a share sale? That is the feeling around India’s National Stock Exchange offer right now. A $2.3 billion deal has pulled in more than $10 billion of demand, and the price tag sits at a richer earnings multiple than several large U.S. exchange groups. I have covered a lot of public offerings. Few of them arrive with this mix of national pride, retail momentum, and a valuation that makes even seasoned buyers pause before they click confirm.
Why The National Stock Exchange Listing Feels Different
The numbers are loud. On a single Monday the book showed bids for 505.81 million shares against 88.64 million shares on offer. That is about 5.7 times covered. Last week, anchors already put in 67.5 billion rupees, or roughly $704 million. Names in that corner included a major sovereign wealth buyer from the Gulf, a large Asian official investor, and the country’s biggest life insurer. When those tickets land early, the rest of the market tends to follow.
This is the largest Indian listing of the year so far and the second-largest on record after a $3.3 billion auto offering in 2024. The company has been circling the public markets since 2016. That long wait matters. By the time the documents finally printed, household balance sheets in India had already shifted toward equities and funds in a way that would have looked implausible a decade ago.
In my experience, delayed listings either lose their story or grow into it. This one grew. Equity and mutual-fund savings as a share of annual household financial savings climbed to 15.2% in the year ending March 2025 from 2% in the year ending March 2012. That is not a rounding error. That is a change in how families store wealth.
A Market That Already Dominates Its Own Backyard
India sits among the world’s ten largest equity markets, with a total capitalization near 492 trillion rupees, or about $5.1 trillion. The National Stock Exchange is the main venue. It holds a 93% share of the cash market, nearly all equity futures, and about 75% of equity options. If you want a single listed vehicle that tracks the plumbing of Indian risk, this is the closest thing on offer.
An asset-light model helps the story. High incremental margins and steady cash conversion are the phrases brokers keep repeating. I find that language a little polished, but the economics are real. Matching trades does not require a steel mill. Once volumes scale, profit can scale faster than headcount.
Growing participation and deeper financialization give the exchange a long runway that most mature venues in the West no longer enjoy.
That runway is the heart of the bull case. New investors keep arriving. A rival exchange chief noted earlier this year that tens of millions of accounts were added on his platform in 2025 and that a large slice of the population still has not entered the market. Domestic flows also cushioned local indexes when foreign money stepped back. That is a structural change, not a one-month headline.
The Valuation Gap That Makes People Argue
Here is the part that will keep dinner conversations going. At the top of the price band, the implied multiple is about 42.9 times earnings based on per-share profit for the year ended March 2026. Large U.S. exchange groups trade closer to the low twenties. One well-known cash-and-listings venue sits near 23.6 times. A bigger multi-asset operator sits near 21.9 times. Same industry family. Very different sticker.
Is that a reason to walk away? Not automatically. Growth rates are not the same. A mature U.S. franchise is priced like a utility with optional tech upside. An Indian franchise is priced like a growth compounder riding a still-young savings shift. The question is whether 43 times already assumes a perfect decade.
| Venue Type | Approx. P/E Context | What The Market Is Paying For |
| Indian cash and derivatives leader | Low-40s at IPO band | Volume growth and household financialization |
| Large U.S. listings and data group | Low-20s | Stable cash flow and product mix |
| Global multi-asset operator | Around 22 times | Diversified fees and clearing scale |
I’ve found that multiples this rich only work if three things hold: volumes keep rising, regulation stays predictable, and competition does not steal the options pie. Miss two of those and the premium compresses fast. Hit all three and early buyers look clever in five years.
Who Is Actually Buying This Deal
Institutional and high-net-worth books drove the first wave. That is typical for a flagship listing. Retail will still matter on allotment day because Indian offers often split demand across categories with different oversubscription math. The headline 5.7 times figure is a blended number. The real heat often sits in one bucket while another looks merely healthy.
Anchor support changes psychology. When official capital and a domestic insurer show up before the public window, later buyers treat that as a quality stamp. Sometimes that stamp is deserved. Sometimes it is just liquidity looking for a national champion. You have to separate prestige from price.
- Official and sovereign-style tickets that signal size and patience
- Domestic institutions that already live inside the same market structure
- High-net-worth accounts chasing scarcity in a thin free float
- Broader public demand tied to the retail participation story
Scarcity is not a small point. A tightly held float can keep the aftermarket tight even when the fundamental multiple looks full. That can be a gift in the first weeks and a trap if the lock-up calendar later dumps supply into a quieter tape.
The Retail Wave Underneath The Listing
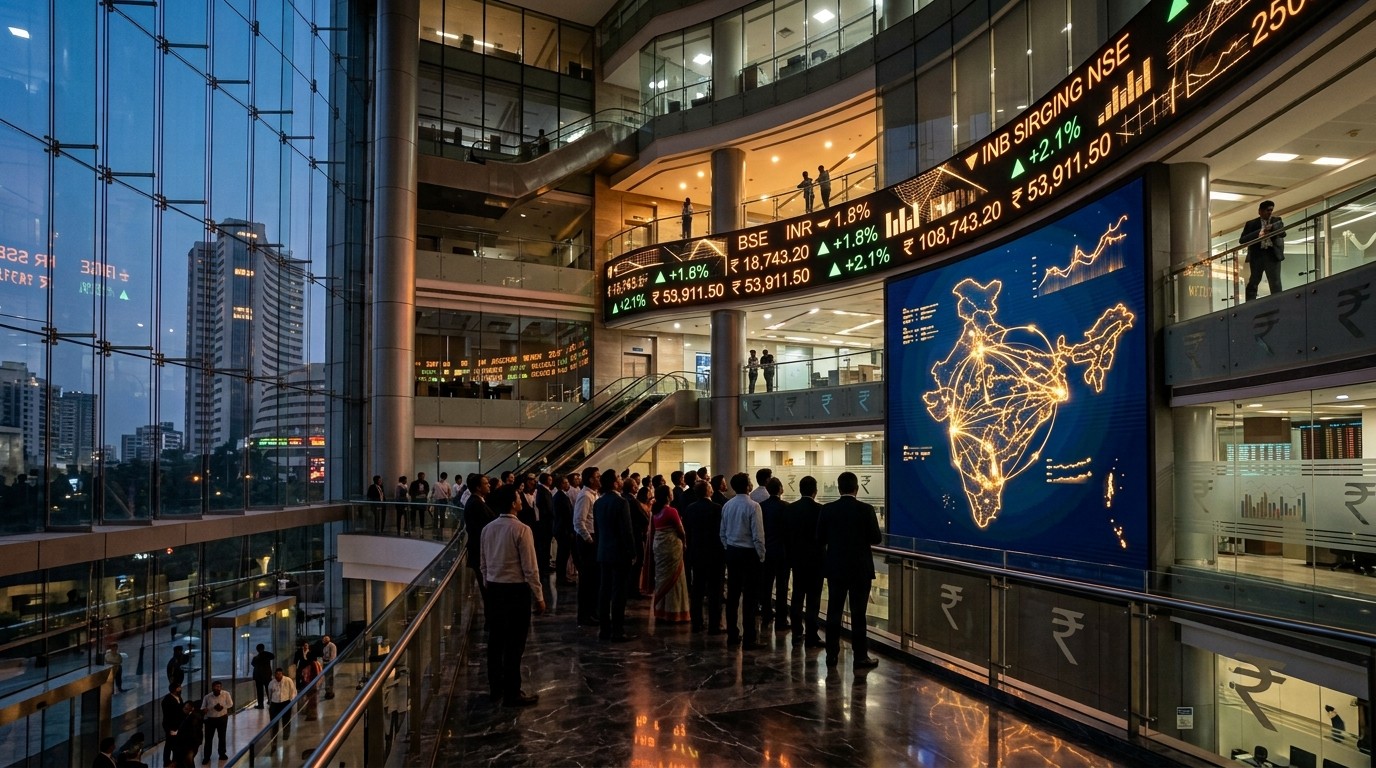
Forget the atrium photos for a minute. The deeper story is the household. Equity used to be a thin slice of Indian financial wealth. It is now a meaningful line item. Apps, lower ticket sizes, and a long bull stretch taught a generation that markets are not only for a handful of city professionals.
That shift feeds the exchange in two ways. First, cash-market turnover. Second, derivatives activity, which is where a lot of the economic juice sits. Options in particular can turn a venue into a fee engine that looks nothing like a sleepy listings hall. Nearly full share in futures and a dominant options slice is the kind of moat investors pay up for.
Still, I get uneasy when everyone recites the same “financialization” line. Cycles exist. A sharp drop in index levels can slow account openings and cut trading intensity. The business is high margin, yes. It is also high beta to national risk appetite. That is not a criticism. It is just the job.
How The Business Actually Makes Money
Think of an exchange as a toll road with software attached. Transaction fees, membership, data, and clearing-related income do the heavy lifting. Incremental trades cost little once the rails are built. That is why the phrase asset-light keeps appearing in notes. Capex is real, but it is not a factory expansion every other year.
Cash generation matters after listing because public shareholders will want a capital-return story. High margins without a use of cash can look elegant on a slide and awkward in a governance review. Watch how the board talks about dividends, technology spend, and any adjacent products after the debut.
Product mix is the quiet swing factor. If options volumes keep compounding faster than cash volumes, earnings quality can stay rich even if cash-market share inches around. If options cool and cash stays flattish, that 40-plus multiple starts to look like a stretch.
Competition, Regulation, And The Things That Break Narratives
A rival venue is not asleep. Account growth there has been loud. Share of cash can stay lopsided for years and still leave room for a second player to chip at options or new products. Markets hate monopolies until they love the cash flows those monopolies throw off. Then they worry again when a regulator leans in.
Policy risk is not theoretical. Transaction charges, position limits, and product approvals can move the P&L faster than a new listing pipeline. I would rather own a great franchise at a fair price than a great franchise that needs every rule to stay frozen.
Perhaps the most interesting aspect is how local ownership of the market has already changed shock absorption. When overseas funds sold, domestic accounts kept a floor under prices. That same domestic base is now being asked to pay a premium multiple for the venue itself. Circular, in a way. Comforting, in another.
What The Oversubscription Really Tells You
Five to six times covered sounds like a victory lap. Sometimes it is. Sometimes it is just cheap leverage and fear of missing a national story. I have seen both. The useful test is simple. After the first week of trading, do quality holders still want more stock, or does the book flip to traders who only wanted the pop?
- Check how much of the book came from long-only capital versus opportunistic money.
- Watch the aftermarket float and any early selling from non-anchor pockets.
- Compare realized volumes and fee trends with the growth implied by the multiple.
- Revisit the gap versus global exchange peers once the stock has a real trading history.
If those four checks stay friendly, the premium can be earned. If they slip, the listing will still be remembered as a landmark. Memory does not protect a share price.
A Longer View On Indian Capital Markets
Zoom out and the listing is a chapter, not the book. A $5.1 trillion equity market with rising household participation can support more than one winner. The exchange is the pick-and-shovel name. Brokers, asset managers, depositories, and data vendors ride the same wave with different risk shapes.
I keep coming back to that jump from 2% to 15.2% in the savings mix. Trends like that do not reverse in a month. They can stall. They can surprise to the upside if pensions and insurance portfolios keep lifting equity weights. Either path still leaves the venue at the center of the pipe.
There is also a cultural piece that models miss. Listing a national market utility is a pride event. Pride can inflate a book. It can also create a shareholder base that holds through ugly tapes because the company feels like infrastructure, not a fashion stock. That is soft analysis. Soft analysis sometimes explains price action better than a spreadsheet.
How I Would Frame The Risk-Reward
If you need a neat slogan, here is mine. You are buying the toll booth on a road that is still being paved, and you are paying highway prices before every lane is open. That can work. It worked in other emerging-market infrastructure stories when volumes arrived on schedule. It failed when the multiple assumed a straight line.
Position size should respect that. A core holding for a long-horizon India allocation is a different decision from a flip because the book is hot. Mixing those two motives is how people get hurt in landmark IPOs.
Simple filter I use on exchange listings:
  Growth story clear?
  Fee mix durable?
  Multiple already pricing a perfect decade?
  Float tight enough to distort the first month?
Answer those without marketing language and the decision gets cleaner. Not easy. Cleaner.
What To Watch After The Bell
The first prints will be theater. The useful work starts in the following quarters. Volume mix, options intensity, technology outages, and any shift in cash-market share will tell you whether 43 times was a beginning or a ceiling.
Also watch guidance tone. Newly listed market utilities sometimes talk like growth companies in week one and like regulated utilities by year two. Both voices can be honest. They imply different valuation anchors.
Currency and global risk appetite will leak into the stock even if the business is local. Foreign holders who missed the IPO may wait for a dip. Domestic holders who feel they “own a piece of the market” may not sell the first 15% drawdown. That split can create odd tape.
A Note On Hype Versus Homework
Hot books flatter everyone. Bankers look brilliant. Buyers feel early. Commentators get a clean headline. Homework is slower. It asks whether the earnings used in that 42.9 times figure already bake in a strong year, and whether the next year needs another leap just to justify staying in place.
I’ve sat with enough post-listing regrets to prefer boredom. Boredom means you sized the position for a multi-year compounding story and you can live with a dull first month. Excitement means you needed the pop to feel smart. Markets do not pay you for feeling smart.
Pay for the franchise. Do not pay twice for the crowd that already discovered it.
Putting The Whole Picture Together
So where does that leave a reader who is not in the syndicate and not managing a sovereign book? It leaves you with a high-quality monopoly-like venue in a market whose households are still migrating into risk assets, offered at a price that already respects that migration. Quality and price are both high. That combination is rare and uncomfortable.
If your horizon is measured in years and your India weight is building anyway, this name can sit in the core as a way to own market structure rather than a single sector bet. If your horizon is the first green candle, you are not investing. You are renting a headline.
The atrium in Mumbai will look beautiful in every recap photo. The bid-to-cover ratio will be repeated until it becomes trivia. The only number that will still matter in 2028 is whether volumes, fees, and trust in the rails grew fast enough to catch the multiple that buyers accepted in 2026.
That is the unglamorous ending, and it is the honest one. Landmark listings feel finished on allocation day. They are not. They are the start of a public-market argument about growth, power, and how much of the future you are willing to prepay. On that argument, this deal is going to be noisy for a long time.
One last thought, because these pieces always risk sounding like a scorecard. I like businesses that sit in the middle of other people’s activity. Exchanges do that. I like them less when the ticket already assumes nobody else will build a faster lane. Hold both ideas at once and you will read the prospectus with a cooler head than the people who only saw the $10 billion of bids.
Cooler heads still buy great assets. They just refuse to pretend that a rich multiple is a detail. In this case the multiple is the story sitting right next to the story everyone prefers to tell. Ignore either half and you will misread the listing. Keep both in view and you can decide, without the theater, whether this toll booth is priced like a road that is already finished or like one that still has miles of pavement ahead.