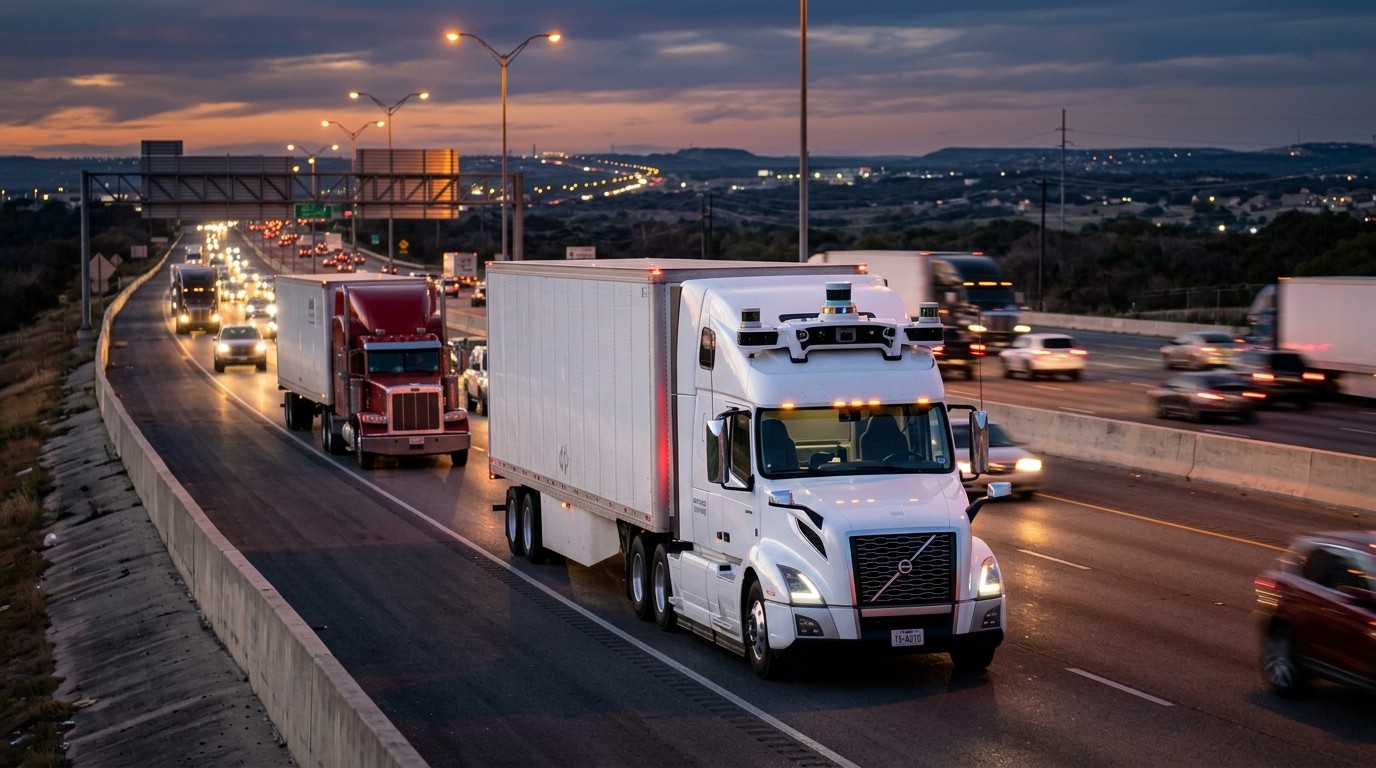

Have you ever glanced at a long-haul cab on a packed interstate and wondered what the whole industry would look like if that seat stayed empty on purpose? I had that thought again this week after sitting with the idea of driverless freight for far longer than is probably healthy. The picture is no longer science fiction parked in a test lot. It is a handful of tractor-trailers already moving cargo between Texas cities, and a company arguing it can turn that trickle into a cash-generating machine before the decade is out.
Why Empty Cabs Suddenly Matter To Freight Money
The pitch is blunt. An autonomous truck can run longer, burn fuel with fewer sloppy habits, and keep rolling when a human driver would be legally required to sleep. That is not a slogan. It is the entire commercial argument. If the math holds, shippers pay less per mile and operators squeeze more work from the same iron. If the math slips, you are left with very expensive sensors staring at a sunset.
I keep coming back to the scale of the existing market. There are roughly 3.5 million Class 8 semis on American roads. Only a sliver of that fleet is driverless today. Even a modest slice of those miles, priced as a service rather than a one-off robot sale, could move a lot of money. That is the bet. Not a sci-fi demo. A billing model.
An autonomous fleet should be nearly 7.5 times as profitable as a human-driven fleet today.
Another estimate floating around the Street puts the service cost near $0.85 per mile against about $1.30 per mile for wages and benefits alone, before you even count the indirect labor load. Those numbers will be argued to death. They should be. Still, they explain why investors keep showing up for a story that lost more than $800 million last year and still talks about positive free cash flow by 2028.
What A Three-Hour Ride Actually Feels Like
Picture Interstate 45 between Houston and Dallas, or I-20 stretching west from Fort Worth toward El Paso. Those corridors are thick with trailers. They are also the kind of relatively structured highway environment where autonomy has a fighting chance. Lasers, radar, and cameras watch every lane. The software decides when to merge, when to hold speed, when to give a little space to a tired four-wheeler who drifted too close.
The ride that has been described in public is almost boring, which is the point. Three hours. One brief pull-off to reset hazard lights that flickered for no obvious reason. No panic. No cinematic swerve. Passing drivers did double takes when they realized the cab was empty. That human reaction may be the most honest review the technology will get for a while.
In my experience, the public does not judge autonomy on slide decks. People judge it on whether the truck next to them looks calm. Uneventful is a compliment in this business. Drama is a lawsuit.
From Twenty Trucks To Two Hundred
The current count is small. About twenty driverless trucks on the road. The near-term plan is two hundred by year end. That is still tiny next to national freight volume, but it is a different species from a single prototype circling a closed course. Volume is how you learn the ugly edge cases. Volume is also how you start talking about unit economics instead of science projects.
Since public-road testing began in 2022, the company has logged more than 440,000 miles. Most of those miles still included a safety operator ready to grab the wheel. That distinction matters. Testing with a human in reserve is not the same product as a truck that has to solve a blown tire, a sudden work zone, or a stalled pickup without anyone in the seat.
Leadership likes to point at internal timelines and say they have mostly hit them. Fair enough. Hitting a testing milestone is not the same as hitting a cash-flow milestone. One is engineering pride. The other is whether the lights stay on without another round of patient capital.
Driver As A Service, Not A Robot For Sale
The commercial wrapper is simple on paper. Customers pay by the mile. The company supplies the “driver,” which in this case is a stack of sensors and software bolted onto a conventional tractor. Freight firms keep the relationship with shippers. They just stop paying a person to sit in the same seat for eleven hours at a stretch.
Why would anyone buy that? Three reasons keep coming up.
- Fuel economy can improve when a computer does not get impatient or heavy-footed.
- Goods can move overnight and through hours a human legally cannot cover.
- Fleets that cannot hire enough qualified drivers still have freight that has to move.
That last point is the quiet engine of the whole story. The driver shortage is not a myth invented by software people. It is a grinding operational fact. It is also incomplete. Drivers do more than hold a lane. They handle dock quirks, protect cargo, talk to receivers, and make judgment calls when a plan meets a messy yard. Anyone who pretends those extras do not exist is selling a brochure, not a network.
The drivers do more than just move the rig. There is judgement. There is customer service. There is protection.
I tend to side with that caution. Autonomy can own the long, dull highway middle. The first mile and last mile still look stubbornly human. The companies that admit that split will age better than the ones promising a clean sweep of the profession by next Tuesday.
Hours Of Service Versus Hours Of Software
Federal rules cap how long a person can drive before mandatory rest. That cap exists for good reasons. Fatigue kills. An autonomous tractor does not get sleepy in the same way. In theory it can work toward twenty hours in a day, pausing for fuel, inspection, and charging or maintenance rather than for a bunk.
That extra utilization is where the 7.5 times profitability claim tries to live. More productive hours on the same tractor. Fewer hotel stays. Tighter schedules. Less waiting for a driver who is legally out of hours fifty miles from the delivery window. You can see why a freight desk would lean forward.
You can also see the new failure modes. Software does not get tired. It can get confused. A construction barrel in the wrong place, a glare event, a sensor that needs a wipe, a municipal truck blocking a lane with no standard marking. Humans improvise. Code follows a policy. The policy has to be good enough that improvisation is rare.
Safety Skeptics Are Not Going Away
A truck doing 65 or 70 with nobody in the seat will always make people nervous. That instinct is healthy. The counter is experience. Millions of simulated tests. Hundreds of thousands of public miles. A claim of about 15 million tests before hardware went out for real work. Those figures sound large until you remember how many weird things happen on American interstates before lunch.
Perhaps the most interesting aspect is not the marketing number. It is the operational humility of pulling over for a minute when hazard lights misbehave. That is not a failure of the dream. That is how you keep the dream from becoming a wreck. I would rather see a company stop and reset than insist the stack is already perfect.
Rivals are not sitting still. Other teams are building their own driverless freight stories, some focused on shorter dedicated lanes, some on broader highway ambition, some on passenger vehicles that might someday share components. Competition is useful. It keeps claims honest. It also means the first company to two hundred trucks is not automatically the company that owns the category in 2030.
The Cash Flow Clock Ticking Toward 2028
Last year the hole was deep. More than $800 million gone. That is the price of sensors, compute, mapping, salaries, insurance experiments, and the slow work of convincing regulators and customers that an empty cab is not a stunt. The target now is positive free cash flow by 2028, powered by a much larger autonomous fleet on the road.
Can that happen? Maybe. It depends on a few unglamorous things landing at once.
- Hardware cost per truck has to fall as volume rises.
- Uptime has to stay high enough that customers trust the schedule.
- Insurance and liability frameworks have to settle into something priced like a product, not a science experiment.
- Corridors have to expand beyond a couple of Texas interstates without the software falling apart in messier weather and traffic.
Miss two of those and 2028 becomes a slogan. Hit all four and the per-mile gap versus human labor starts to look like a real business, not a lab with a press team.
| Factor | Human-driven fleet | Autonomous service pitch |
| Typical paid labor per mile | About $1.30 in wages and benefits | Quoted near $0.85 for the service |
| Daily utilization | Limited by rest rules | Aimed closer to 20 productive hours |
| Hiring friction | Chronic shortage | Software scale, hardware lead time |
| Judgment at the dock | Strong | Still a weak spot |
| Public comfort | Familiar | Still forming |
Texas As A Proving Ground, Not The Whole Map
Texas highways are a gift to this industry. Long stretches. Heavy freight density. Weather that is often more heat than ice. Political appetite for experiments. If you cannot make the product work between Houston and Dallas, you probably cannot make it work in a Nor’easter on a broken shoulder in New England.
The danger is treating Texas success as national readiness. Different states mean different enforcement cultures, different winter maintenance, different mixing of passenger cars and farm equipment. Autonomy loves consistency. America is not consistent. That is not a reason to stop. It is a reason to stop pretending a single corridor is a continent.
I’ve found that the companies that talk about geofenced excellence first tend to sound more adult than the ones promising every zip code by the next product cycle. Crawl the profitable lanes. Then crawl the next set. Pride is a terrible navigation system.
What Shippers Quietly Want
Ask a freight broker what they actually buy and the poetry disappears. They buy reliability at a price that does not wreck the bid. They want a trailer that shows up. They want fewer surprises at the appointment window. They want a phone number when something breaks.
Autonomy can help the first two if utilization is real. The third is a service design problem. Who answers when the truck is stuck behind a jackknifed load and the receiver is screaming? Software can reroute. Someone still has to own the relationship. That someone will either be the carrier, the autonomy vendor, or a messy blend of both. Customers hate messy blends.
There is a version of this future that looks less like replacing drivers and more like stretching them. Highway legs go robotic. Complex city approaches stay human. Relay points become normal. That hybrid is less exciting in a keynote. It is more likely in a P&L.
The Labor Question Nobody Should Dodge
Every conversation about empty cabs eventually hits the same wall. What happens to the people who currently do this work? Some will move into yard operations, remote assist, maintenance, and training. Some will not. Pretending otherwise is insulting.
The honest frame is transition, not disappearance. Long-haul is the piece most exposed. Local delivery, specialized haul, oversized loads, and anything that requires a person to climb out and solve a physical problem will keep needing humans for a long time. That is not comfort for someone whose lane is I-45 at 2 a.m. It is still the shape of the next decade.
Policy will lag the trucks. It always does. Training programs, insurance rules, and inspection standards will get rewritten after the first ugly incident, not before. That is a grim pattern, but it is the pattern.
Investors Hear A Growth Story. Operators Hear A Cost Story.
Wall Street likes optionality. A platform that can theoretically sit on a huge share of national truck miles is catnip. Operators like fewer headaches per load. Those two audiences use the same words and mean different things. Growth for one group is headcount and valuation. Growth for the other group is whether Thursday’s produce still arrives cold.
That gap is why the per-mile price will matter more than the keynote adjectives. If the service is cheaper and on time, fleets will try it on easy lanes. If it is cheaper and late, they will go back to people they already know how to yell at. Reliability beats novelty in freight. Always has.
Rough mental model:
  Highway middle miles  -> strongest autonomy case
  Weather and work zones -> still expensive to get right
  Docks and yards       -> stubbornly human
  Cash flow             -> a 2028 question, not a 2026 trophy
What Would Make Me Believe The 2028 Line
Timelines are cheap. Evidence is not. I would want to see the two hundred truck target actually land, then hold utilization through a messy quarter, not a cherry-picked week. I would want third-party insurance pricing that looks boring. I would want a second and third corridor that is not just a copy of the first Texas run. I would want customers renewing without being courted like a launch partner.
I would also want fewer mystical sentences about “the need.” Freight already knows the need. Freight wants a vendor who answers the phone when a sensor suite throws a tantrum at dusk. That is not romantic. It is how industrial technology becomes a line item instead of a headline.
Is 2028 possible? On a good path, yes. On the path where hardware stays pricey and every new state is a science fair, no. The company has shown it can put trucks on real pavement and keep them from being a circus. That is necessary. It is not sufficient.
The Small Moments That Will Decide The Category
The hazard-light pause on that Texas run is the kind of detail I trust. Not because lights matter. Because the team stopped. Autonomy fails in public when pride outruns process. A one-minute reset is process. A refusal to admit a glitch is how you get the story nobody wants to write.
Other small moments will pile up. A night in heavy rain. A sudden lane closure with poor signage. A passenger car cutting across two lanes to make an exit. A load that shifts. A sensor cover filmed with summer bugs. None of that belongs in a launch video. All of it belongs in the reliability log.
If those logs stay dull, the profitability target gets easier. If they stay exciting, the market will wait. Freight can wait. It has been waiting on better ideas for a century.
A Clearer Way To Watch The Next Two Years
Ignore the adjectives. Watch the fleet count, the miles without a safety operator, the corridors added, and whether customers talk about cost the way they talk about any other vendor. Watch whether remote assistance stays a rare backup or becomes a hidden second driver. Watch winter. Watch insurance. Watch maintenance intervals on the sensor stack, because a dirty lidar is a parked asset.
Also watch the tone. Companies that are winning tend to get quieter and more specific. Companies that are stretching tend to get louder about the future. I have no unique pipeline into this one. I do have a bias for specifics. Two hundred trucks is a specific. Positive cash in 2028 is a specific. Empty adjectives are not.
Will driverless freight remake long-haul? Parts of it, yes. All of it, no. The interesting fight is not whether a truck can hold a lane on I-45. We have seen that. The fight is whether a service priced by the mile can cover the ugly hours, the ugly weather, and the ugly exceptions without lighting another $800 million on fire.
That is the story worth staying with. Not the double take from the next lane. The invoice that follows a quiet, on-time run, week after week, until an empty seat stops looking like a stunt and starts looking like a line on a freight budget. If that happens by 2028, a lot of skeptics will pretend they always believed. If it slips, the highways will still be full of people who know how to back a trailer at 4 a.m. Either way, the cargo still has to move.