
I kept circling back to the same question after this story landed again: if a major energy exporter walks away from a high-profile cross-border experiment, is that a funeral for a whole alliance or just a change of venue? The latest wave of commentary treats the Saudi departure from mBridge as a sudden crack in BRICS. In my experience, sudden cracks in finance are rarely sudden. They are usually the moment someone finally writes down what insiders already knew.
What The Saudi Exit From Mbridge Actually Changes
Saudi Arabia has stepped back from the multi-central-bank digital currency platform often described as a China-led answer to slow, expensive dollar plumbing. Officials now say participation was always limited and ended after a proof of concept completed in May 2025. That timeline matters. The test happened. The membership did not continue in the same public form. Quiet contact may still exist. Formal membership does not.
Here is the part that gets flattened in most recaps. mBridge was never the entire China strategy. It was one rail among several. The heavier domestic-to-international settlement machine remains CIPS, the Cross-Border Interbank Payment System. Mix those two up and you will misread both the headline and the next five years of settlement politics.
I have found that markets love a clean morality play. BRICS fails, dollar wins, end of story. Real plumbing is messier. Countries hedge. They test. They keep a second phone number. Then they pick the channel that actually clears invoices without creating a political headache at home.
A Platform, Not The Whole Plan
Call mBridge what it is. A shared experiment in faster wholesale settlement using central bank digital money among participating authorities. China carried a lot of the technical weight. Other members sat at the table. That is not the same as a single-country payment monopoly. CIPS is closer to that national backbone. mBridge was the group project.
Group projects stall for ordinary reasons. Legal mismatch. Different risk appetites. Uneven urgency. One partner wants speed. Another wants cover from Washington. A third wants optionality without a press release. None of that requires a conspiracy. It does require patience, and patience is not what summit communiqués sell.
When a proof of concept ends and the membership list shrinks, the story is not that digital settlement died. The story is that the public consortium version lost momentum while other rails kept running.
That distinction is not academic. If you trade energy, metals, or anything invoiced across borders, you care which ledger actually settles the last mile. A lab success that never becomes daily volume is a press clip. A slightly boring bank-to-bank system that already moves value is a competitor.
Why Riyadh Was Never All In
Saudi policy toward the dollar has been a long negotiation, not a conversion experience. Energy sales still live inside a dollar-heavy world. Security ties still lean West. At the same time, more oil buyers sit in Asia. More capital projects involve Chinese contractors. You do not need a manifesto to see the tension. You need a treasury desk.
So they tested mBridge. They finished the concept work. They left the formal club. Reports of more discreet engagement fit the pattern. Keep the technical relationship. Drop the branding. Avoid becoming the poster child for a payment revolt you may not want to lead in public.
Is that bearish for the petrodollar this week? Not really. Is it a forever blessing for dollar invoicing? Also no. I would call it a pause in one particular theater, not a surrender of the broader campaign to create optionality.
- Formal mBridge membership is over after the 2025 test window.
- Discreet technical contact can continue without a flag on the website.
- Dollar energy settlement remains the default until volume proves otherwise.
- Asian demand still pulls policy toward more than one settlement currency.
BRICS Looks Tired Because Coordination Is Hard
Perhaps the most interesting aspect is not the Saudi line item. It is the mood around the wider grouping. Over recent months, conversations with people who watch mainland policy have sounded cooler. Less enthusiasm. Fewer proactive pushes. Less airtime in official talk. That does not mean the brand vanishes. It means the center of gravity can drift when partners move at different speeds.
Alliances of this type always look tighter on a stage than in a working group. One member wants a louder line on a regional conflict. Another wants trade first and speeches later. A third is busy with a domestic credit cycle. You can print a joint statement. You cannot print a shared balance sheet.
When the pace disappoints the member with the deepest industrial base and the most complete payment stack, attention slides toward tools that member already controls. That is a human reaction as much as a geopolitical one. Why wait on a committee if your own rails already clear?
CIPS Gains When The Club Project Slows
If mBridge fades as a headline vehicle, CIPS does not automatically inherit the earth. It does inherit a cleaner narrative. Less need to share governance. Less need to wait for every partner to bless a standard. More room to push yuan settlement through channels Beijing already operates.
Think of two products on the same shelf. One is co-branded and politically sensitive. The other is national infrastructure with growing correspondent links. When the co-branded item loses a famous customer, shoppers do not stop buying payments. They look at the item that still ships.
I keep coming back to that boring truth. Settlement share is not won in a summit photo. It is won in repeated invoices, correspondent relationships, and a legal path that treasurers can defend to a board. CIPS is built for that grind. mBridge was built, at least in public, as a showcase of multipolar cooperation. Showcases are fragile. Grind is not glamorous. Grind compounds.
| Rail | Character | Near-term read |
| mBridge | Multi-party CBDC experiment | Weaker as a public club after the Saudi step-back |
| CIPS | China-centered wholesale settlement | Relatively stronger if consortium energy fades |
| Dollar correspondent banking | Incumbent global plumbing | Still dominant, less pressured in the short run |
| Hong Kong RMB plus gold links | Onshore-offshore bridge | Rising as a practical workaround |
Hong Kong, Gold, And A Different Kind Of Hub
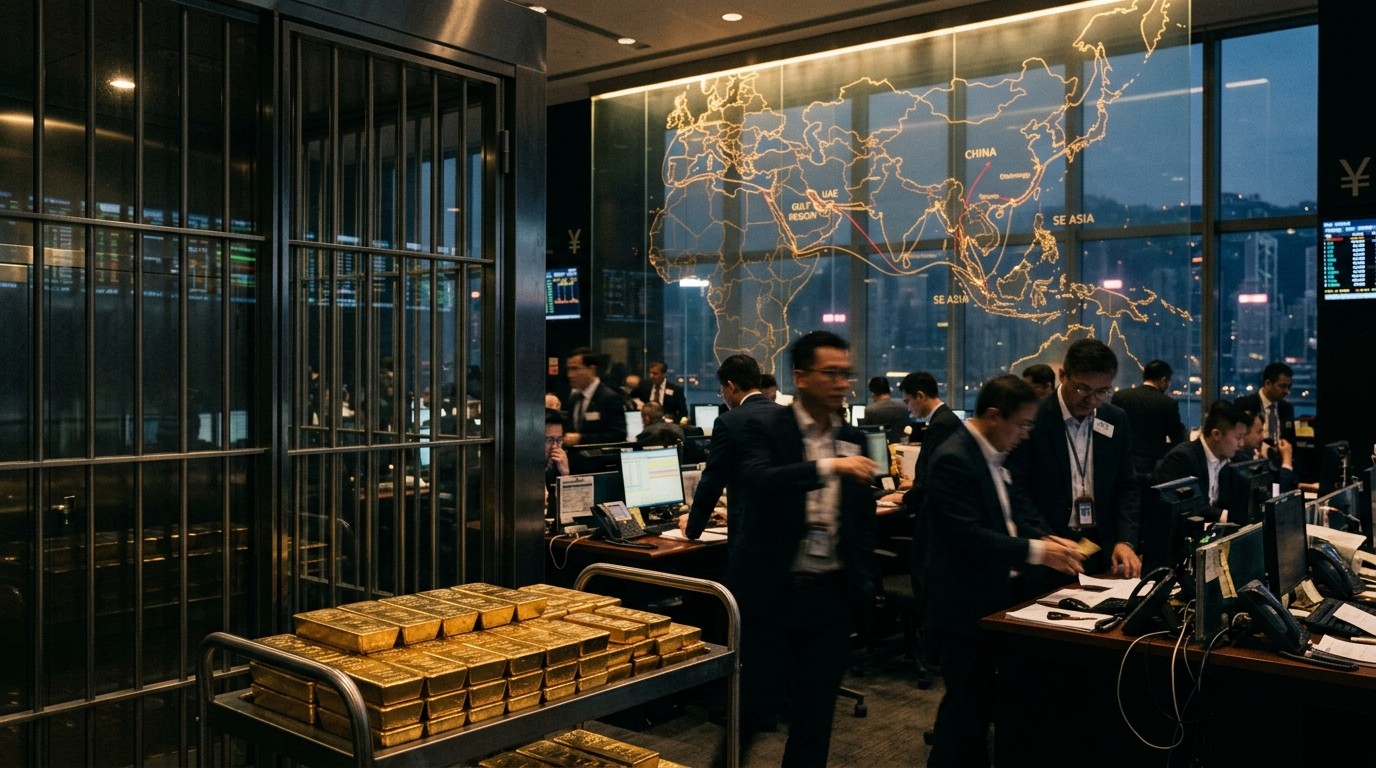
Another thread in this story is vaulting. There was an earlier idea of linking gold storage outside the mainland into one connected map. That map proved harder than the slide deck. The practical response looks simpler. Concentrate trusted vaulting where legal and market infrastructure already talk to the mainland, then pair that metal with offshore yuan liquidity.
Hong Kong sits in that gap. Not because a slogan says so. Because banks, law, and trading hours already live there. If gold can sit in a place that also speaks RMB, you get a two-asset conversation: metal as collateral or confidence asset, currency as the payment leg. That pairing does more for daily use of the yuan than another communiqué about a shared CBDC sandbox.
Does that kill dollar gold pricing overnight? Of course not. Pricing conventions move slower than vault locations. But if more physical metal and more RMB deposits share a city, the option to settle away from old habits becomes less theoretical. Options change behavior even before they become the default.
Short-Term Relief For The Petrodollar, Not A Lifetime Guarantee
Let me be blunt. A famous Gulf producer leaving a China-associated CBDC club is not a disaster for dollar oil bills this quarter. Markets that feared a coordinated sprint away from greenbacks can exhale a little. That exhalation is the short-term read, and it is fair as far as it goes.
The longer read is less comforting for anyone who thinks the incumbent system is frozen in amber. Energy buyers in Asia still want local-currency tools. Sanctions risk still teaches treasurers to keep spare rails. Technology still makes wholesale settlement cheaper than it was ten years ago. None of those pressures clock out because one membership list got shorter.
So you get a split screen. Screen one: BRICS looks less tight, mBridge looks less inevitable, the dollar looks less immediately threatened. Screen two: China doubles down on the rails it owns, Hong Kong becomes a more serious RMB-and-gold workshop, and the plan changes address rather than destination.
They are changing venues. They are not obviously changing the plan to give the yuan a larger settlement role.
How To Read The Politics Without Getting Played
Sensitive files attract spin. One camp will say this proves alternative architecture cannot work. Another camp will say the exit is fake and everything proceeds in secret. Both camps are doing marketing. The middle path is dull and more useful.
Limited participation that ends after a test is a real signal of limited appetite for the public product. Continued discreet contact is a real signal that technical curiosity did not die. Drawing “no broader inference” while publishing the story in a way that invites inference is just how high politics and high finance talk past each other.
I’ve found that the cleanest filter is volume. Who is actually paying whom, in what currency, on what message standard, with what fallback if a correspondent bank says no? Until those numbers move, rhetoric is just weather. When those numbers move, rhetoric becomes a lagging indicator.
- Separate the consortium brand from the national payment stack.
- Treat proof-of-concept exits as data, not destiny.
- Watch Hong Kong RMB liquidity and gold inventory together, not apart.
- Measure invoice currency mix in energy and commodities, not summit adjectives.
- Assume most large states want optionality more than a loyalty oath.
What Investors And Treasurers Should Watch Next
If you sit on a desk that cares about currency regimes, the next tells are practical. Correspondent additions to CIPS. The share of bilateral trade settled in yuan. The tone of Gulf official comments on invoicing experiments that never make the front page. The speed at which Hong Kong products package metal and RMB in the same conversation.
Also watch disappointment inside the wider grouping. When public discussion of the club thins out, it can mean two opposite things. Either the project is quietly working and no longer needs a megaphone, or the project is stalled and the megaphone became embarrassing. Distinguishing those two is the whole job.
My own bias, stated plainly, is that stalled public clubs often feed stronger private or national systems. That is not a law of physics. It is a pattern. Committees are slow. Balance sheets are impatient. The player with the working pipe keeps using the working pipe.
The Dollar Still Clears. That Is Not The Same As Permanence.
None of this requires you to join a dollar-collapse choir. The incumbent system still has depth, law, and habit on its side. Most commodities still think in dollars first. Most global banks still route through familiar correspondent chains. Habit is a moat until it is not.
The Saudi step-back reduces the odds of a cinematic, coordinated break in the near term. Fine. Price that. Just do not confuse a quieter year for BRICS theater with a freeze in settlement innovation. The interesting competition has always been less about flags and more about which message hits the beneficiary bank on Tuesday afternoon.
And Tuesday afternoon is where CIPS, offshore yuan, and metal-linked confidence trades live. Not in a slogan. In a confirmation message.
A Plain-Language Map Of The Moving Parts
If a friend asked me to explain this over coffee, I would not start with acronyms. I would start with a shipping invoice. Someone sold a cargo. Someone has to pay. Banks in two countries have to trust a path. For decades that path leaned on dollar accounts and a small set of messaging habits. Alternatives now exist in pieces. Some pieces are clubs. Some pieces are national pipes. Some pieces are city-level hubs that sit between legal systems.
mBridge was the club piece with a digital-currency twist. The Saudi chapter of that club closed after the test. The national pipe did not close. The city hub looks busier as a concept. That is the map. Everything else is commentary.
Simple scorecard I keep on a notepad:
  Public BRICS cohesion: softer
  mBridge as a headline rail: weaker
  CIPS as a workhorse: relatively stronger
  Petrodollar this quarter: less immediate pressure
  Yuan optionality over five years: still the live debate
Why The Old News Still Matters When It Returns
One reason this episode feels recycled is that the test window was already known to people who follow the file. What changed is the packaging. A withdrawal framed today, in a tense diplomatic season, lands differently than a quiet technical note last year. Timing is a message even when the underlying fact is stale.
That does not make the fact fake. It makes the amplification strategic. Readers should hold both ideas at once. The membership change is real. The decision to treat it as a banner development now is also a choice. Good analysis separates the two without becoming cynical about everything.
I still think the useful question is downstream. If the club rail is less central, where does the next incremental yuan invoice actually clear? If the answer keeps pointing to CIPS and Hong Kong, then the “BRICS is fraying” headline and the “yuan still wants a bigger role” headline can both be true. Markets hate two true things at once. Reality does not care.
Risks People Underplay On Both Sides
Cheerleaders for alternative rails underplay legal depth, capital controls, and the simple fact that many counterparties still prefer the devil they know. Cheerleaders for permanence underplay how fast corporate treasurers can add a second currency clause once a large buyer asks for it. Both sides talk like systems flip with a switch. Systems accrete.
There is also coalition risk. A grouping that cannot align on security crises will struggle to align on money standards. Money standards need trust about sanctions, data, and last-resort liquidity. That is heavier than a pilot on a test network. If trust among partners thins, national systems look safer than shared ones. That logic cuts against mBridge more than against CIPS.
On the dollar side, complacency is the quiet risk. A year with less BRICS noise can become an excuse to ignore invoice-level shifts that never trend. By the time those shifts are large enough for a magazine cover, the plumbing has already moved.
What This Is Not
This is not a prediction that oil stops being priced in dollars next winter. This is not a eulogy for every multipolar experiment. This is not a claim that one country has lost interest in a larger financial role. It is a claim that the public vehicle most associated with a shared CBDC club just lost a prominent name, and that loss redistributes attention toward other tools.
If you only remember one sentence, remember that. Vehicles change. Ambitions migrate. Settlement share is earned in repetition.
A Closing Read For Anyone Who Has To Decide Something
If you allocate capital, do not trade a headline about a proof of concept as if it were a regime change. If you run a treasury, keep the dollar stack you already trust and keep learning the alternative message paths before you need them. If you follow geopolitics as a hobby, resist the urge to declare a winner because one logo left a pilot.
The Saudi decision is a data point about appetite for a particular public club. The cooler mood around the wider grouping is a data point about coordination costs. The continued build-out of national and city-level RMB tools is a data point about persistence. Put those three on the same page and the picture is neither collapse nor coronation. It is a reroute.
Reroutes are how financial history usually moves. Not with a single dramatic vote. With a test that ends, a membership that shrinks, a hub that gets more gold and more yuan, and a workhorse system that keeps clearing while the speeches get quieter. That is less exciting than a broken alliance on a poster. It is also closer to how money actually travels when the cameras leave.
So yes, the club looks frayed. Yes, one famous energy producer is no longer listed where many expected it to stay. And yes, the incumbent currency gets a breather. Just keep an eye on the other pipe. That is where the next quiet invoices will try to live.