
Have you ever watched a stock grind higher for months and still felt like the options market was falling asleep at the wheel? That is the odd feeling around Nvidia right now. The shares have been strong. The story is still loud. Yet the price of protection, and the price of a big swing bet, has quietly slipped. In my experience, that mix does not last forever. When cheap options meet real event risk, someone usually gets paid for noticing the gap.
Why Cheap Nvidia Options Matter Right Now
Nvidia has already delivered a solid 2026 run, up about 24% on the year and sitting only a few percentage points under its May closing peak near $235.74. Five sessions in a row of gains will do that to a tape. The stock looks expensive if you only glance at the price. Look under the hood and the picture is messier. The forward multiple has eased because earnings power keeps expanding. That is not a crash. That is a company growing into its valuation.
Here is the twist. Options on that same stock are not acting like a name sitting near highs with news still on the calendar. Implied volatility has drifted toward the low end of the past year. In plain English, the market is not charging much for expected movement over the next few weeks. I find that curious. Cheap options are not a free lunch. They are a signal that consensus expects a quiet path. Consensus is often right until it is not.
Two items sit on the near-term map. First, diplomacy around artificial intelligence policy, including a high-profile Washington visit that could put export rules, demand, and tone back in the headlines. Second, a major memory supplier reports results at month-end. Memory is not Nvidia. It is still a useful read on how hungry the AI buildout remains. If those events stay dull, the cheap options stay cheap. If they do not, the people who bought movement at a discount will look pretty clever.
The Quiet Gap Between Price Strength And Option Cost
Strong stocks with sleepy options create a specific kind of setup. Traders call it a volatility disconnect. You do not need a PhD to feel it. The shares keep climbing. The option premiums refuse to keep up. That can happen after a long trend, when the market treats every dip as a gift and every rally as inevitable. Complacency has a smell. It smells like low implied vol on a name that still lives in the news cycle.
Perhaps the most interesting part is how quickly semiconductor names can reprice. One session last week showed that in public. A peer ripped higher and crossed a huge market-value mark. Others jumped double digits on fresh excitement about chip demand. Nvidia itself did not need to explode that day for the lesson to land. The group can still move fast. Fast group moves and cheap single-name options do not always stay friends.
When implied volatility sits near a one-year low while catalysts are still on the calendar, the market is offering a discounted ticket to uncertainty.
I am not saying the stock must break. I am saying the cost of being wrong about calm weather looks unusually light. That is a different claim. Direction is a guess. The price of a guess is data. Right now that data leans cheap.
Two Catalysts That Could Wake The Tape
The first catalyst is political as much as commercial. Leadership meetings in Washington tend to put AI policy, export limits, and supply-chain talking points back on every desk. Nvidia sits in the middle of that conversation whether it wants the spotlight or not. A warmer tone can lift risk appetite. A colder tone can hit sentiment even if the actual rule change takes months. Markets trade the mood first.
The second catalyst is operational. A large memory producer reports fiscal fourth-quarter numbers near September 30. That print is a proxy for how hard the industry is still running to feed data-center demand. Strong memory commentary can support the whole AI hardware complex. Soft commentary can raise awkward questions about inventory and timing. Nvidia does not report that night. It still lives next door.
- Policy headlines can change export assumptions overnight.
- Memory earnings can confirm or challenge AI demand narratives.
- Sector ripples often hit the leader even when the news is one company over.
- Low implied volatility means those ripples are not fully prepaid in option prices.
Neither event is a guaranteed explosion. That is the point. You do not buy a movement structure because you know the headline. You buy it because the market is not charging much for the chance that the headline matters.
A Defined-Risk Way To Bet On A Big Move
One trader-facing structure that fits cheap vol is a reverse iron condor. Fancy name. Simple idea. You want the stock to leave a middle range by a set date. You do not need to pick up or down in advance. You pay a net debit. You cap the pain. You also cap the gain. That last part bothers some people. I would rather cap the gain than pretend unlimited risk is a personality trait.
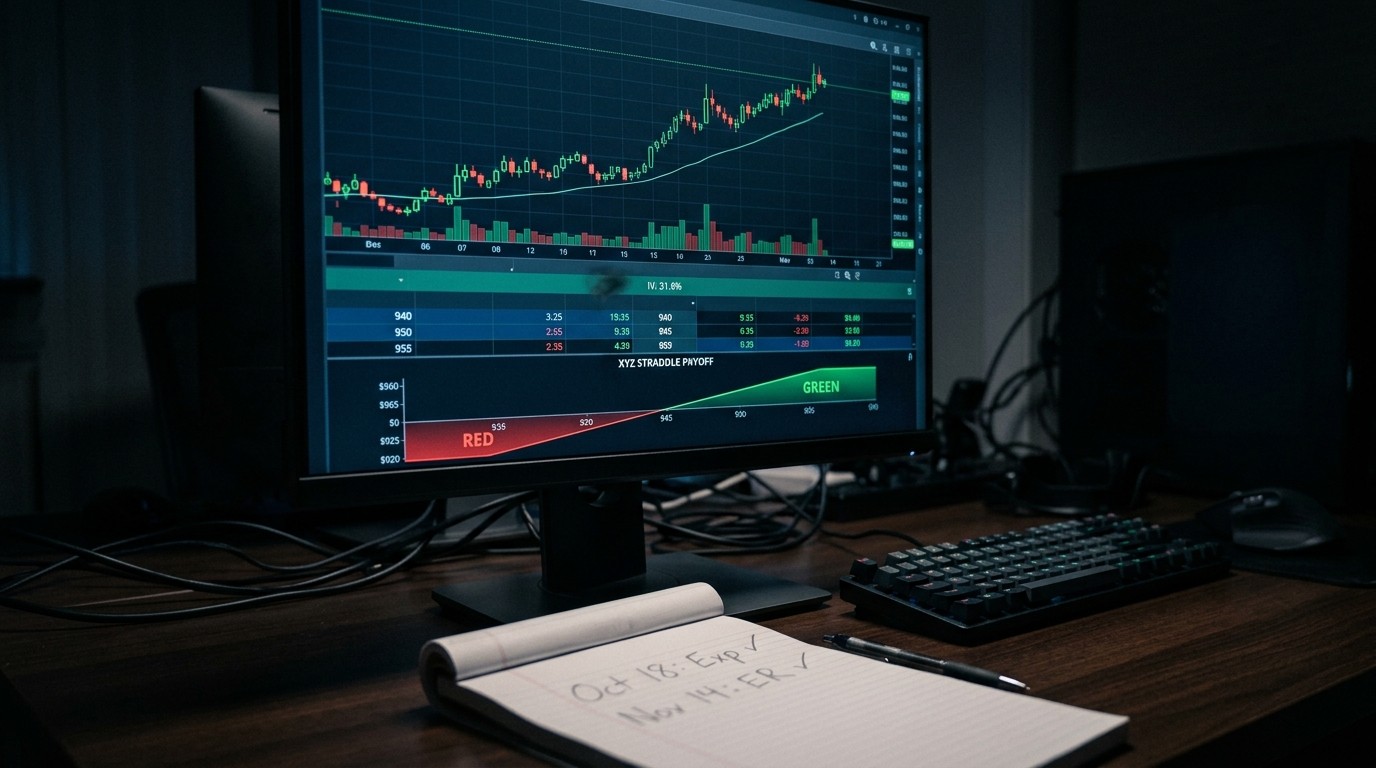
The concrete version discussed around this tape uses October 16 expiration. Buy the 210/220 put spread. Buy the 235/245 call spread. Combined debit around $4.86. In dollars, that is roughly $486 of maximum loss per package if Nvidia dies of boredom between 220 and 235 into expiration. Maximum gain sits near $514 if the stock finishes at or beyond 210 on the downside or 245 on the upside. Breakevens land near $215.14 and $239.86. Call it a 5% to 6% push from recent levels by mid-October.
The long 220 put and long 235 call are the engine. Those strikes sit closest to the current neighborhood and look relatively inexpensive because implied vol is depressed. Selling the 210 put and the 245 call, each about ten points farther away, throws off a credit. That credit lowers the ticket and lifts the theoretical probability of profit toward the mid-50s. Nothing magical. Just arithmetic.
| Piece | Role | Why It Matters |
| Long 220 put | Downside engine | Pays if shares slump hard |
| Short 210 put | Financing leg | Cuts cost, caps extra downside profit |
| Long 235 call | Upside engine | Pays if shares break higher |
| Short 245 call | Financing leg | Cuts cost, caps extra upside profit |
Is this the only way to play cheap options? Of course not. You could buy a straddle and pray. You could buy a strangle and need an even bigger move. You could sell premium and hope the calendar stays polite. The reverse iron condor is a compromise. It admits you do not know the direction. It also admits you should not pay full freight for both wings.
What The Numbers Actually Ask The Stock To Do
A 5% to 6% move by mid-October does not sound wild for Nvidia. This name has done that in a sleepy week. It has also sat still for longer than fans like to remember. That is why the structure is a bet on range expansion, not a prophecy. If shares loaf between 220 and 235, the long options decay and the debit becomes a lesson. If they travel, one side starts to work and the short wing eventually limits how rich the win can get.
Think of the short strikes as insurance you sold to yourself. They make the trade cheaper. They also mean a melt-up to 260 does not turn into a lottery ticket. Same story on a washout toward 190. Defined risk cuts both ways. I have found that traders who hate capped wins often ignore how often uncapped fantasies arrive with uncapped nights of staring at the screen.
Rough map by October 16
Inside 220–235: max pain near $486
Beyond 210 or 245: max gain near $514
Breakevens near 215.14 and 239.86
Need about 5%–6% travel from recent prices
Those figures assume held-to-expiration pricing and ignore commissions, slippage, and early assignment quirks. Real life is messier. That is why many people close defined-risk spreads before the final bell rather than gift the market a pin risk souvenir.
Why Implied Volatility Is The Real Character In This Story
Implied volatility is just the market’s weather forecast expressed as a price. When it sits near a yearly low, the forecast is mild. Mild forecasts feel comfortable after a winning streak. They also leave less cushion if the forecast is wrong. Buying options when the forecast is mild is not automatically smart. It is cheaper than buying them when everyone is already shouting.
There is a second layer. Even if the stock does not gap, a jump in implied vol can lift the value of those long wings before expiration. Policy noise and an earnings proxy in the same neighborhood can do that. Then again, vol can stay asleep. Cheap can get cheaper. Anyone who has sold premium into a dead tape knows that song.
So the trade is not “vol must explode.” The trade is “movement is mispriced relative to the calendar I can see.” Subtle difference. I would rather live with that framing than with a slogan.
Sector Context: Semiconductors Still Know How To Sprint
Chip stocks have a habit of looking sleepy right until they do not. Demand narratives around artificial intelligence do not move in a straight line. They lurch. A design-win rumor, a data-center capex comment, a policy leak, a memory pricing print. Any one of those can re-rate a group that already trades on future scarcity.
Monday-style sessions, where several names jump hard on renewed enthusiasm, are a reminder. Leadership can rotate inside the group. The largest name does not always lead the sprint. It often still participates. That participation is enough for a reverse iron condor that only needs a mid-single-digit push.
- Watch whether the group keeps making impulsive daily ranges.
- Watch whether implied vol on the leader stays depressed after those ranges.
- Watch whether the two catalysts produce headlines that travel outside specialist desks.
- Decide in advance whether you will hold through expiration or cut risk early.
I keep coming back to that last point. Assignment risk on short options is not theoretical near expiration, especially if one side goes deep in the money. Closing early is boring. Boring is underrated.
Who This Setup Is For, And Who Should Walk Away
This is not a starter kit for someone who just learned what a call is yesterday. You need to understand debit spreads, short-strike assignment, and the fact that a “neutral” structure can still lose money in a grind. You also need a plan for size. A few hundred dollars of defined risk is a teaching position for some accounts and noise for others. It is never a personality.
Walk away if you need the stock to go up because you already own a pile of shares and want the options to agree with you. Walk away if you cannot tolerate being wrong in a tight range. Walk away if you will stare at every tick of a Washington dinner and call it a trading process. Process is the part that happens before the headline.
Options are a way to rent a view on movement. They are a poor way to rent a mood.
If you already think Nvidia is going to $300 because the future is inevitable, just say that and buy calls or shares. Do not dress a directional crush in a market-neutral costume. Honesty about motive saves more money than any clever strike selection.
Risks That Do Not Show Up On The Payoff Sketch
The sketch says max loss equals the debit. True on paper. In practice you can mismanage exits, pay wide markets, or hold a winning side too long while the other side decays into dust. You can also get a move that is real but late. A stock that rips the week after expiration is a great story for someone else.
Liquidity is usually decent in this name, which helps. It does not make you immune to a one-minute quote that looks like a practical joke. Use limits. Check the spread. Do not market-order your way into a “smart” structure and then complain about fill quality.
Another quiet risk is narrative fatigue. If both catalysts land as non-events, implied vol can sink again. Long options hate that. The reverse iron condor still has a defined hole in the middle. A dull tape plus falling vol is how that hole wins.
A More Human Way To Think About Positioning
I like to treat event weeks as questions, not answers. Will policy talk change the demand story, or just fill a news cycle? Will memory results confirm that AI hardware still has a pulse, or hint that the buildout is digesting? Cheap options let you ask those questions with a known bill. Expensive options make the same questions feel like a vanity project.
There is also a psychological trap. After a 24% year-to-date run, bulls feel validated and bears feel late. Both camps can overpay for conviction. A structure that only needs travel is a way to step outside that argument. You are not required to join a team. You are required to respect the debit.
Does that sound hedgy? Good. Markets punish certainty more often than they punish curiosity. Curiosity with a cap on losses is, to me, the adult version of speculation.
Practical Management Before Mid-October
If the stock gaps through one wing early, you can take the winning spread off and let the other side expire, or you can close the whole package and stop negotiating with hope. If nothing happens into the first catalyst, you can decide whether the second catalyst still justifies the remaining time value. Dead money is still money.
- Write your exit rules before you click buy.
- Decide a profit target that is smaller than max gain on purpose.
- Decide a time stop if both events pass and vol does not wake up.
- Avoid holding short options into expiration unless you truly want the assignment mess.
None of that is glamorous. Glamour is for screenshots. Management is for still having an account next quarter.
The Bigger Lesson Behind One Ticker
Nvidia is the example because it is loud, liquid, and sitting near highs with options that look tired. The lesson travels. When a leader’s implied volatility compresses into a window that still contains real news, look at the price of movement before you look at another hot take. Sometimes the hot take is already in the stock. The discount is in the options.
That does not mean every quiet options market is a gift. Some stocks are quiet because the story is finished. This one does not feel finished. It feels expensive in cash terms and oddly inexpensive in option terms. That tension is the article. The trade is just one way to rent the tension for a few weeks.
Will the shares sprint through 245, slump through 210, or take a nap in the middle? I do not know. Neither does the person quoting the debit. What I do know is this: when the market marks uncertainty at a discount, it is worth at least reading the ticket twice before the calendar turns the page.
Final Thoughts Before You Touch The Chain
Cheap Nvidia options ahead of two catalysts are not a secret handshake. They are a visible quote. Anyone can see implied vol leaning low. Anyone can see the calendar. The work is deciding whether a defined-risk, both-ways structure matches your temperament. If it does, size it so a full loss is dull. If it does not, stand aside and let other people pay tuition.
I keep a simple rule on event trades. If I cannot explain the max loss in one sentence, I do not belong in the position. Here the sentence is easy. About five hundred dollars disappears if Nvidia refuses to leave a tight band by mid-October. About five hundred dollars appears if it leaves that band with room to spare. Everything else is commentary.
Commentary is cheap. Options, for once, look a little cheap too. That combination is rare enough to write about. It is still not a promise. Treat it like a short lease on uncertainty, keep the risk defined, and do not confuse a tidy payoff diagram with a crystal ball. The tape will settle the argument soon enough.