
Have you noticed how often “AI for good” sounds like a slogan until someone actually writes a check? That was my first reaction when Circle Foundation confirmed its first domestic grants on September 22. Not another product launch. Not another stablecoin headline. A philanthropic bet on two community lenders that want machines to help people who usually get a polite no from a bank.
Why These First Domestic Grants Matter
Circle Foundation named Accion Opportunity Fund and Pacific Community Ventures as the first U.S. recipients. Both groups are Community Development Financial Institutions. In plain English, they lend to small-business owners who sit outside the usual credit box. The announcement landed during the Clinton Global Initiative Annual Meeting in New York. The company did not publish the size of either award. That silence is part of the story, and I will come back to it.
These are not the Foundation’s first grants overall. An international award went out in January to support a United Nations digital treasury project. The U.S. pair now gives the Foundation a split personality in year one: one track for global payment infrastructure, another for American small-business credit. I find that split more interesting than the press language around it.
Circle framed both awards around AI-enabled infrastructure rather than one-off loan dollars. That is a choice. You can fund a thousand individual businesses and still leave the underwriting process untouched. Or you can fund tools that a lender uses again and again. The Foundation picked the second path.
What Accion Plans To Do With Credit Compass 2.0
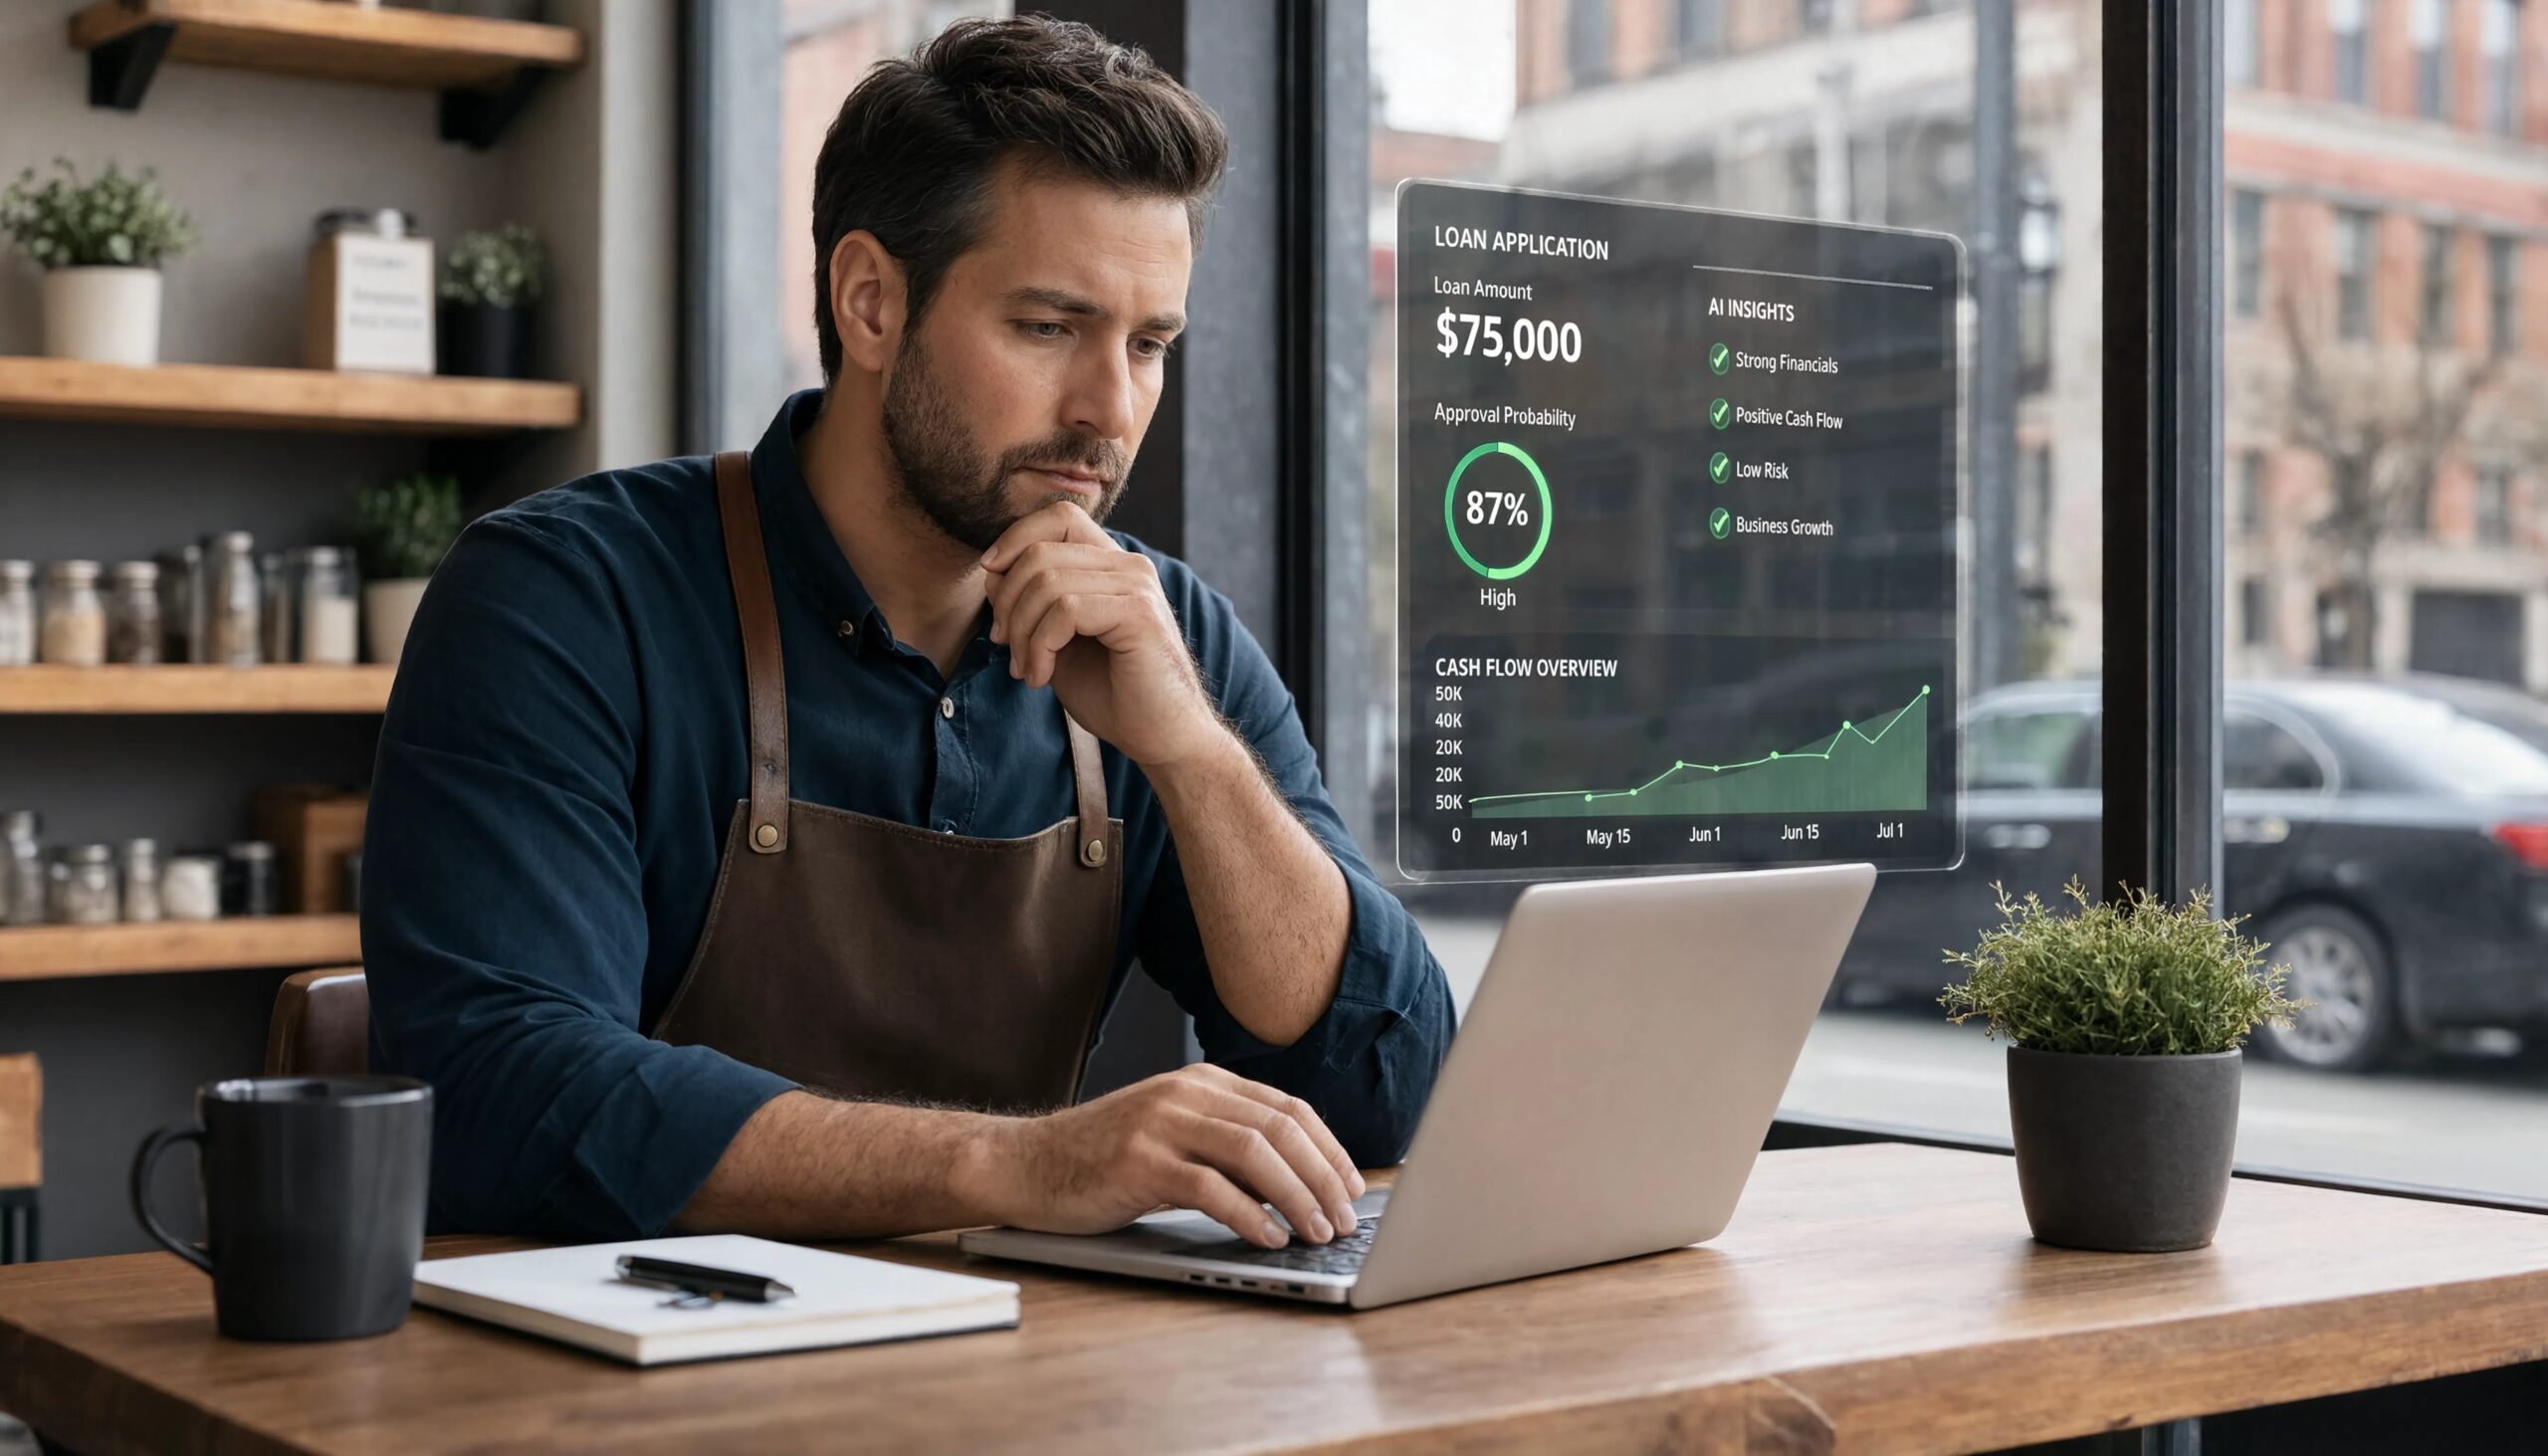
Accion Opportunity Fund is a nonprofit small-business lender with a long record inside the federal CDFI system. The grant is meant to support Credit Compass 2.0. The idea is simple on paper and harder in practice. Someone applies. The file is incomplete, thin, or not yet ready. Instead of a cold rejection, the tool uses application data to explain why the file fell short and what to fix before the next try.
Accion says applicants who use its educational resources are 84% more likely to qualify later. Circle repeated that figure. Neither side published sample size, time window, or an independent review. I would treat the number as a company claim, not a settled fact. Still, the product logic is easy to follow. A declined applicant who walks away with a checklist is cheaper to serve than one who disappears and comes back with the same gaps.
Credit Compass 2.0 gives small business owners a real roadmap to capital.
– Elisabeth Carpenter, Circle Internet Group
Luz Urrutia, Accion’s chief executive, put it in more human terms. Owners get a clear picture of where they stand. That sounds modest. It is not. A lot of mission lending still treats education as a brochure after the fact. Wiring the lesson into the application itself is a different design.
Circle has not said that USDC, Arc, or any Circle commercial stack will power the tool. That distinction matters. The Foundation sits apart from the listed parent. Mixing brand and charity too tightly would make the grants look like a customer-acquisition program. For now, the company is keeping the wall in place, at least in public language.
Pacific Community Ventures And The Radiant Data Hub
The second grant goes to Pacific Community Ventures for the Radiant Data Hub. PCV built the platform after buying a data and AI partner in 2025. That deal brought in AIKKA, a voice tool meant to gather qualitative feedback across major languages. The Hub is supposed to combine governance, predictive modeling, benchmarking, and impact analytics for mission lenders.
PCV also plans a CDFI Data Commons in fall 2026. The pitch is shared benchmarking across participating lenders, trained on mission-driven loan books rather than big-bank portfolios. If that works, a local lender in one city could compare performance against a national set of similar files. If it does not work, you get another dashboard that nobody opens after the pilot ends. I have seen both outcomes in community finance.
We intend to keep human judgment and community impact at the center as we expand AI use.
– Bulbul Gupta, Pacific Community Ventures
PCV published an ethical AI policy alongside the product story. That is smart politics and, if the policy is real, decent risk management. Predictive underwriting can encode old bias at new speed. A community lender that copies a model trained on the wrong population can lock people out faster than a loan officer ever could. The policy will only matter if it constrains product decisions when growth pressure shows up.
How The Foundation Pays For All Of This
The money trail is clearer than the grant sizes. Before Circle listed, the board reserved up to 2,682,392 Class A shares for Foundation contributions. That was about 1% of capital stock at the time of approval, to be contributed over ten years.
The first transfer came in November 2025: 268,239 treasury shares, booked as a $23.1 million general and administrative expense. By June 30, 2026, another 134,120 shares had moved, with $13.1 million in related expense. Full-year 2026 guidance pointed to 268,239 shares. Using a late-July reference price, the company sketched a non-cash cost near $22 million, with the usual warning that the final number follows the stock.
| Item | Detail |
| Shares reserved | Up to 2,682,392 Class A |
| Share of capital at approval | About 1% |
| First transfer | 268,239 shares in November 2025 |
| First-half 2026 transfer | 134,120 shares |
| 2026 full-year plan | 268,239 shares |
| Structure | Donor-advised fund at Fidelity Charitable |
The Foundation is a donor-advised fund. Circle covers operating costs so contributed resources can go to grants. Staff get up to 40 hours of paid volunteer time a year. All of that is governance hygiene. None of it tells you what Accion or PCV actually received last week. I’ve found that companies like the glow of a grant announcement more than the awkwardness of a dollar figure. Fair enough. Readers should still notice the gap.
The International Track Still Sits In The Background
In January the Foundation backed the United Nations Digital Hub of Treasury Solutions. Public descriptions talk about cross-border transfers, local-currency conversion, programmable disbursements, and links across more than 150 banking systems in over 100 countries. Fifteen agencies sit in the project. The toolkit includes AI treasury tools, on-chain disbursements, wallets, banks, and mobile money.
Related aid-payment pilots in other UN programs have claimed sharp drops in distribution costs in some markets. One frequently cited Syria example put costs at 2% after a blockchain trial, down from 10%. Those figures belong to the agencies, not to Circle’s new U.S. grants. I mention them only because the Foundation is clearly running two experiments at once: global treasury plumbing and domestic credit education.
Perhaps the most interesting aspect is how little the two tracks share on the surface. One is about moving money across borders under humanitarian pressure. The other is about helping a bakery owner in California understand why a file got declined. Same donor. Different problem.
Where Circle’s Commercial AI Story Fits, And Where It Does Not
Circle has another AI story in its commercial books. Company figures for the second quarter said USDC settled 99.3% of x402 AI-agent payment volume. That is a payments statistic, not a lending statistic. It shows the firm wants to sit next to machine-to-machine money movement. It does not prove that Credit Compass or Radiant will touch a stablecoin wallet.
I keep seeing people mash those stories together. Don’t. Philanthropy that funds a CDFI education tool is not the same thing as an agent paying another agent in USDC. Both can be true. Mixing them turns a grant into marketing copy.
- The grants fund lender tools, not Circle-branded loans.
- No public claim that USDC settles the Accion or PCV products.
- No published user targets or launch dates for either tool.
- No disclosed dollar size for either award.
Why Community Lenders Are The Test Bed
CDFIs exist because mainstream credit still misses people. Thin files. Informal books. Owners who look risky on a FICO printout and viable in a shop doorway. Federal award records show both Accion Opportunity Fund Community Development and Pacific Community Ventures have taken Financial Assistance and Technical Assistance support across multiple years. They already speak the compliance language of that system.
That makes them safer partners than a brand-new fintech with a slide deck. It also creates a tension. Federal programs reward prudence. AI products reward speed. A tool that tells an applicant “you are 14 points short” can help. A tool that quietly ranks neighborhoods is another matter. The Radiant Hub’s talk of nationally representative algorithms will need public testing, not just a fall launch party.
In my experience, the first year of a data commons is the easy year. Everyone wants the dashboard. Year two is when lenders notice that sharing portfolio data also means sharing their weaknesses. Some will stall. Some will send partial files. The model then trains on the willing, not on the representative. Watch for that.
What “Personalized Financial Education” Really Means
Credit Compass 2.0 is being sold as education. Fine. Education that is generated from an application file is also underwriting-adjacent. The same features that explain a decline can later score a file. That is not a scandal. It is a design fact. If the tool works, Accion will know more about failed applicants than most banks ever bother to store.
Used well, that knowledge becomes a coaching loop. Used poorly, it becomes a second filter that never says its name. I would want to see three things before I cheer too loudly:
- How advice is generated and who reviews edge cases.
- Whether declined applicants can contest the explanation.
- Whether the 84% lift holds after the grant publicity fades.
None of those items appeared in the announcement. That is normal for a first-day story. It will not be normal if they are still missing a year from now.
A Quiet Choice About Product Versus Cash
Circle could have funded loan loss reserves. It funded software. There is a worldview in that. Software scales. A reserve is spent. Software also creates dependency on vendors, data quality, and staff who can interpret a model. Community lenders are not always staffed for that. A grant that buys a platform without buying the people to run it can look generous and still stall.
I do not know which way these two shops will go. Accion already has an education product in market, so the grant is an upgrade path. PCV is assembling a newer stack after an acquisition. Upgrades and new stacks fail for different reasons. One dies of neglect. The other dies of integration.
The Ten-Year Equity Pledge Changes The Time Horizon
Most corporate foundations live on annual budgets that shrink when the stock has a bad quarter. Circle pre-committed a slice of equity over a decade. That does not make the Foundation independent. Share value still swings. It does make the funding story less brittle than a single cash appropriation.
It also ties charity to the listed company in a visible way. Investors can see the expense line. Critics can call it branding. Both readings can sit in the same room. The cleaner test is grant quality over time, not the poetry of a 1% pledge.
What to watch next:
  Grant values
  User counts for Credit Compass 2.0
  Launch timing for the Data Commons
  Any later link to Circle rails
  Independent review of the 84% claim
The Human Layer That AI Cannot Fake
Small-business credit is still a conversation. An owner explains a seasonal dip. A loan officer decides whether the story holds. Voice tools and dashboards can collect more of that story than a paper file ever did. They cannot decide whether the story is true. PCV’s line about human judgment is the right instinct. The industry’s record on keeping that instinct when a model looks confident is mixed.
There is also a language problem. AIKKA is described as working across major languages. That is useful in communities where English is not the operating language of the shop. It is only useful if the translation preserves meaning, not just words. Credit advice that misfires in a second language is worse than no advice.
What This Does Not Change In Crypto Markets
This announcement will not reprice a stablecoin. It will not settle a regulatory fight. It will not tell you whether Circle’s commercial AI payment share keeps climbing. It is a foundation story with a listed sponsor. Treat it that way.
If you care about Circle as an investment, the relevant facts remain the share reserve, the expense recognition, and the ten-year schedule. If you care about credit access, the relevant facts are product design, bias controls, and whether declined owners actually come back stronger. Those are different audiences. The announcement tried to speak to both. That is why it feels a little stretched.
A Few Practical Questions Worth Asking Now
Will Accion publish outcomes by cohort, not just a single lift percentage? Will PCV name the lenders in the first Data Commons and the rules for joining? Will Circle ever disclose grant sizes after the event glow fades? Will either tool remain independent of Circle’s commercial rails if the products succeed?
I would also ask who owns the applicant data after the coaching session ends. Education tools become valuable because they sit on rejected files. Those files are intimate. A bakery’s cash gaps, a contractor’s late invoices, a family guarantee. If that data trains a wider model, the owner should know.
My Read After Sitting With The Details
The grants look serious enough to watch and thin enough to doubt. Serious because the recipients are real CDFIs with federal histories, not pop-up labs. Thin because the money is hidden, the 84% figure is unverified in public, and the Data Commons is still a plan for fall. That mix is common in year-one philanthropy. It is not a reason to sneer. It is a reason to keep a notebook.
If Credit Compass 2.0 becomes a habit inside Accion’s pipeline, more owners will leave a decline with a map instead of a shrug. That is worth something even if the headline number moves. If Radiant becomes a shared book for CDFIs, smaller lenders might underwrite with less guesswork. That is worth something even if the algorithm is less “nationally representative” than the pitch.
And if both tools stall, Circle still will have booked the equity transfers and collected the conference photos. That is the unromantic version. I prefer the version where the tools get used, measured, and argued over in public. Community credit does not need another slogan. It needs fewer dead ends after a no.
So here is where I land. The first U.S. grants are a start, not a proof. Watch the products, not the stage. Ask for numbers. Keep the commercial AI story in a separate drawer. And remember that a roadmap to capital only matters if someone can actually walk it.