

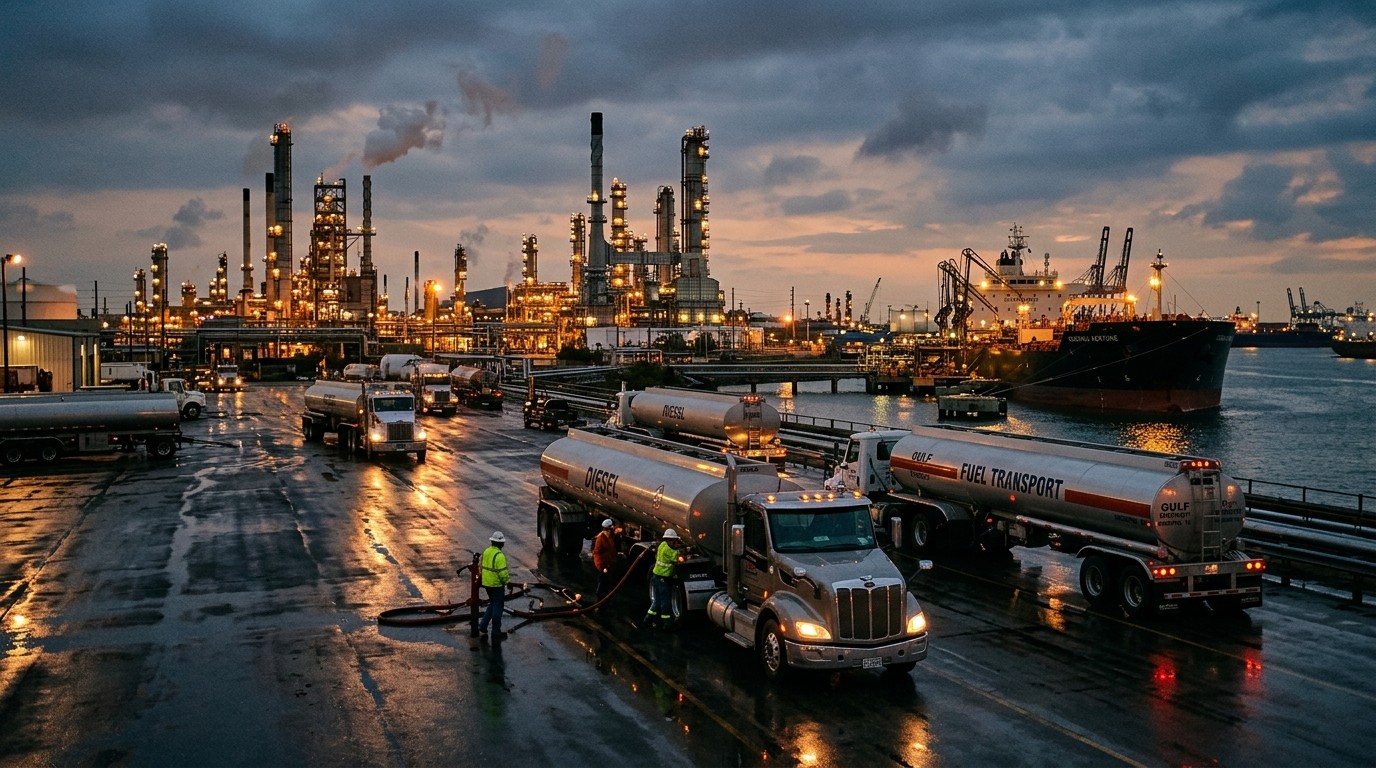

Have you ever watched a market flip in a single afternoon and wondered how much of that move was policy and how much was panic? That is roughly what happened when talk of a short-term US diesel export ban hit the tape. American futures dropped hard. European prices jumped just as fast. Truckers, refiners, and anyone who lives by the pump felt the whiplash before a single official document had even been signed.
Why A Short Export Ban Suddenly Feels Political
Diesel is not a glamorous product. It is the workhorse fuel. Farms, freight, construction sites, generators, and a big slice of the industrial economy run on it. When that price climbs into uncomfortable territory, households notice the grocery bill and companies notice the freight invoice. I have found that energy debates get loud the moment they stop being abstract and start showing up in weekly budgets.
That is the backdrop. Distillate inventories have looked tight on a seasonal basis. Pump prices have been elevated. Some officials see a simple lever: keep more barrels at home for a few months and force the domestic price down ahead of a politically sensitive stretch. Others see a blunt instrument that looks clever for a week and messy for a year.
The reported idea is a 90-day curb on diesel leaving the country. The legal path is still fuzzy. The political path is not. One camp inside the debate is basically saying the sky is falling at the pump and something has to happen. The other camp is saying that “something” can easily become a self-inflicted supply problem.
The blunt tool of banning diesel exports definitely does not work.
– US energy official, speaking against a broad curb
That quote is the heart of the split. Restricting exports can strand barrels on the Gulf Coast. Refiners then sit on product they cannot ship. Margins sag. Runs get cut. Gasoline and jet fuel get tighter too, because a refinery does not make diesel in a vacuum. Cut the crude slate and you cut the whole barrel.
What The Immediate Market Reaction Already Told Us
Price action is often ruder than a press briefing. US diesel futures sank more than 7 percent to an intraday low after the report circulated. European diesel jumped more than 7 percent to a session high. That is not a coincidence. Traders priced a world in which American barrels stay home and Europe has to fight for replacement cargoes.
Europe already lost a chunk of traditional supply after sanctions redirected Russian product and after Middle East flows tightened. The United States stepped into that gap. Weekly US product exports have at times approached record levels. Of the roughly 8 million barrels of diesel moved by sea each day worldwide, American barrels account for a large slice, on the order of 1.5 million barrels. Pull that source and you do not just rearrange a spreadsheet. You remove the single largest flexible exporter from the seaborne market.
The crack spread in Europe, the premium of diesel over crude, has been watched by people who care about inflation because it feeds through freight and food. When that spread blows out, the story is no longer just energy desks. It becomes a household story in another language.
Who Buys American Diesel And Why That Map Matters
Export destinations are not trivia. They show who gets squeezed first if barrels are locked inside US waters.
| Destination | Role In The Trade | Why It Matters |
| Mexico | Largest buyer of US distillate | Imports US products while sending heavier crude north |
| Chile | Second-tier but growing buyer | Limited domestic refining flexibility |
| Brazil | Major Latin buyer | Has also taken discounted barrels from other origins |
| Netherlands | Trading and re-export hub | Feeds Northwest Europe |
| United Kingdom | Large direct consumer market | High dependence on seaborne product |
Mexico still sits at the top of the list, even if volumes have eased from the prior year. Chile and Brazil matter because Latin America does not have a deep bench of spare refining capacity sitting idle. The Netherlands and the United Kingdom matter because they are the door into a European system that is already short diesel.
In my experience, people underestimate how much of “US energy independence” is really a two-way street. The United States exports light products and imports certain crudes and other grades. Slam one side of that door and the other side starts to creak.
The Refining Problem Nobody Wants To Own
Keeping diesel inside the country does not automatically put it in the right tanks. Pipeline direction, ship availability, and fuel specifications are not political slogans. They are plumbing. A surplus can pile up on the Gulf Coast while the East Coast and West Coast stay tight. Storage on the Gulf can absorb only so many weeks of stranded exports before the system clogs.
Industry analysts have warned that a broad curb could strand something like 1.5 million barrels a day, close to a third of US diesel output depending on the week. If those barrels crush local prices and margins, refiners have a rational response: run less crude. One widely cited estimate is that crude runs might need to fall by nearly 2 million barrels a day to clear a forced surplus. That is more than 10 percent of current throughput. It is not a rounding error.
- Trapped Gulf Coast barrels first, weaker local diesel prices second
- Weaker margins then invite run cuts and extra maintenance
- Lower runs tighten gasoline and jet as well as diesel
- Global buyers scramble for Indian, Middle Eastern, or leftover barrels
- Any later rebound in US demand meets a smaller refining slate
That last point is the asymmetry. You can engineer a brief dip in the domestic diesel price. You may also manufacture a tighter product market later. The more aggressive the restriction, the more that trade-off tilts toward tomorrow’s shortage.
Europe, Latin America, And The Search For Replacement Barrels
There is no neat substitute sitting in a warehouse labeled “emergency diesel.” Shipping desks have been saying as much for months. Latin America and Northwest Europe look particularly exposed. Competition for Indian barrels would intensify. China could make the squeeze worse if domestic stocks fall and export licenses stay tight.
Perhaps the most interesting aspect is how quickly a national policy idea becomes a global allocation fight. Diesel is fungible until it is not. Specs differ. Ships are booked. Insurance and sanctions screens slow cargoes that look simple on a map. A 90-day US pause would not pause winter demand in the North Atlantic or harvest demand in the Southern Cone.
I keep coming back to a simple picture. Imagine pulling the largest flexible supplier off a tight market and telling everyone else to share what is left. Prices do the rationing. That is not ideology. That is arithmetic.
Inflation, Freight, And The Quiet Path Into Core Prices
Diesel is an industrial input dressed up as a fuel. When it spikes, it does not stay in the energy column. It moves through trucking rates, food distribution, construction schedules, and manufacturing costs. Economists who watch core inflation have flagged this channel before. You do not need a dramatic shortage at every pump for the effect to show up in sticky categories.
That is why the European crack spread getting bid to extreme levels is not just a trader curiosity. Central banks notice energy that refuses to behave. Companies notice contracts that reprice with a lag. Households notice the second-round stuff: delivery fees, ticket prices, the cost of getting goods from a warehouse to a shelf.
A domestic ban that cheapens US diesel for a few weeks while lifting European diesel could still leave American importers of finished goods paying more. Supply chains are not patriotic. They are priced in the dearest available barrel that can arrive on time.
Why Officials Keep Reaching For This Lever Anyway
Let’s be honest. The political temptation is obvious. US diesel above uncomfortable pump levels is a visible problem. Distillate stocks sitting at seasonally weak readings make the problem look urgent. A 90-day window sounds temporary, surgical, reversible. It photographs better than “wait for refining maintenance to end and hope imports fill the gap.”
Resource nationalism has a long history in energy. Countries hoard when voters are angry. The trouble is that refined products are the output of plants designed to sell into a global market. Change the sales map overnight and you change the operating map. Plants are not light switches.
Restricting exports is not a solution to high prices. Removing US diesel from the market could instead result in reduced refinery runs, global economic damage and even higher US prices.
– Oil industry group warning
That is the industry line, and it is not hard to follow. Whether you like those companies or not, the incentive structure is clear. Nobody runs a complex at a loss for long just to fill political tanks.
Regional Winners, Regional Losers Inside The United States
A national headline hides local plumbing. The Gulf Coast is the export machine. It is also the place most likely to drown in unsold diesel if ships stop lifting. The East Coast relies more on waterborne product and can stay tight even if Houston tanks look full. The West Coast has its own spec and logistics headaches. A one-size ban does not produce a one-size price.
Truckers in one region could see a dip. Fleet operators in another could see no relief at all. Farmers already living with seasonal diesel demand would care less about the national average and more about the rack price at the nearest terminal. That is the part of energy policy that never fits on a bumper sticker.
- Map where the surplus would actually sit after an export stop.
- Check pipeline direction and Jones Act shipping limits for moving product coast to coast.
- Ask whether winter spec and summer spec can even swap into the tight region.
- Estimate how many weeks of storage exist before refiners cut crude runs.
- Model gasoline and jet balances after those run cuts, not just diesel.
If that checklist looks boring, good. Policy that ignores it tends to produce exciting prices later.
The Global Refining Crunch Is Not A One-Quarter Story
Desk notes from large banks have been pointing to a stretched global refining system well beyond the next news cycle. Diesel and gasoline can stay firm when capacity additions lag demand and when plants keep taking unplanned downtime. A US export pause does not add a single distillation unit. It only reallocates existing molecules.
Through 2026 and 2027, the system still looks tight in a lot of those notes. That matters because a 90-day political fix sits on top of a multi-year capacity problem. You can rearrange the chairs. You cannot pretend the room got bigger.
I have sat with enough energy people to know the phrase they use when politicians discover product markets: “You cannot ban your way to spare capacity.” It is a little smug. It is also usually true.
What A Smarter Toolkit Might Look Like
If the goal is lower pump prices without wrecking runs, the conversation usually turns to narrower tools. Targeted waivers. Faster permitting for logistics that actually move barrels to tight regions. Strategic coordination with neighbors who already buy US product and send crude the other way. Seasonal stock builds before the heating and harvest windows, not after prices explode.
None of that is as clean as a ban announcement. All of it is less likely to force a 2-million-barrel-a-day run cut. The boring path is often the one that keeps gasoline and jet from becoming the next headline.
There is also the credibility problem. Markets learn. If every price spike produces an export threat, exporters hedge differently, buyers diversify away, and domestic refiners treat overseas demand as less reliable. That can shrink the very complex you need when the next shortage arrives.
How To Read The Next Few Weeks Without Getting Fooled
Watch three things, not the loudest quote. First, the legal language. A rumor is not a regulation. Second, Gulf Coast inventories and crack spreads. If barrels pile up and margins collapse, run-cut talk will follow. Third, European and Latin American prompt differentials. Those will tell you whether the rest of the world found replacement cargoes or simply paid up.
Also watch gasoline. A diesel-only political story can become a multi-product story the minute refiners throttle crude. That is when the “we only meant diesel” line starts to look thin.
Quick field guide:
  Ban talk  -> US diesel down, Europe up
  Actual curb -> Gulf surplus, coastal basis chaos
  Run cuts    -> gasoline and jet join the squeeze
  Later       -> tighter balances if demand holds
If those arrows feel too neat, remember markets overshoot both ways. A denial can bounce US diesel just as fast as a leak crushed it. Volatility is the tell that policy is still unwritten.
The Human Layer Behind The Futures Screen
It is easy to treat this as a chart. It is not only a chart. A contractor bidding a job needs a diesel assumption that does not blow up the quote. A grocer in a rural county needs trucks that still show up at a price the store can stand. A European manufacturer already paying a record product crack does not care that the original idea was domestic politics in Washington.
Energy policy that forgets those people tends to create the next round of anger it was trying to prevent. That is not a partisan point. It is a timing point. Short-term optics and long-term barrels live on different clocks.
So where does that leave the story? Still unresolved. Still tradable. Still capable of surprising anyone who thinks a 90-day label makes the physics optional. The market already voted with a 7 percent move in both directions. The next vote will come from refiners, shipowners, and whoever has to fill a tank when the surplus is in the wrong place.
If there is a lesson I keep relearning in these episodes, it is this: product markets punish simplicity. Diesel looks like one fuel. It is really a network of plants, pipes, specs, and buyers who cannot wait for the politics to settle. Ban the exports if you must. Just do not pretend the rest of the barrel will sit quietly while you do it.



