
Have you noticed how a single week in energy markets can suddenly change the mood of an entire continent? I have. One morning the conversation is about growth data looking a bit healthier. By lunchtime traders are staring at diesel screens that refuse to sit still. That is the strange atmosphere hanging over Europe right now. Supply is tight, middle distillates are scarce where they matter most, and the price at the pump is no longer a distant wholesale story. It is sitting in household budgets and factory cost sheets at the same time.
Why European Diesel Markets Are Moving So Fast
During Wednesday morning trade in London, major European diesel futures jumped as much as 7% and touched about 1,528 dollars per ton. In rough barrel terms, that is close to 200 dollars. I know that number looks abstract until you convert it into a truck fill-up or a chemical plant’s monthly energy line. Then it stops being abstract.
The more telling figure is the gap between European diesel and Brent crude, the so-called diesel crack spread. That spread spiked toward 95 dollars per barrel. Market data put that among the widest readings seen since 2011. When the crack blows out like that, it usually means refined product is the bottleneck, not only raw crude.
I know when there is a problem at retail prices is when my parents call me and ask me what is going on with the price of petrol. That is when you know it is really felt by the end user. And looking at the forward curve, even next year is still way over 150 dollars a barrel.
– Energy markets specialist
That comment stuck with me because it cuts through the jargon. Families notice first. Then freight companies. Then manufacturers that burn a lot of heat and power. After that, the policy debate starts lagging the price action, which is never a comfortable place for central bankers.
Supply Tightness Is No Longer A Short Week Story
Escalating regional conflicts keep squeezing Europe’s diesel import options. Among the usual suppliers, export volumes from countries such as Russia and Saudi Arabia have fallen sharply versus early-year levels. That matters because Europe is not a closed refining island. It leans on seaborne barrels and product cargoes when local runs cannot cover demand.
European diesel futures have recently printed historic highs and more than doubled from the start of the year. I find that second point more important than the single-session spike. A one-day jump can fade. A market that has doubled over months is telling you inventories, logistics, and geopolitics are all pulling in the same direction.
- Import flows from key suppliers have dropped versus early-year volumes
- Product tightness is showing up first in diesel, not only in crude benchmarks
- The crack spread is flashing scarcity in refining and logistics, not just oil
- Forward prices remain elevated, which argues against a quick comfort rally
In my experience, markets can absorb a headline shock if traders believe replacement barrels will arrive in three or four weeks. They get nervous when the replacement map looks thinner and the curve stays elevated into the next calendar year. That is closer to where Europe sits now.
What Drivers Are Paying At The Pump
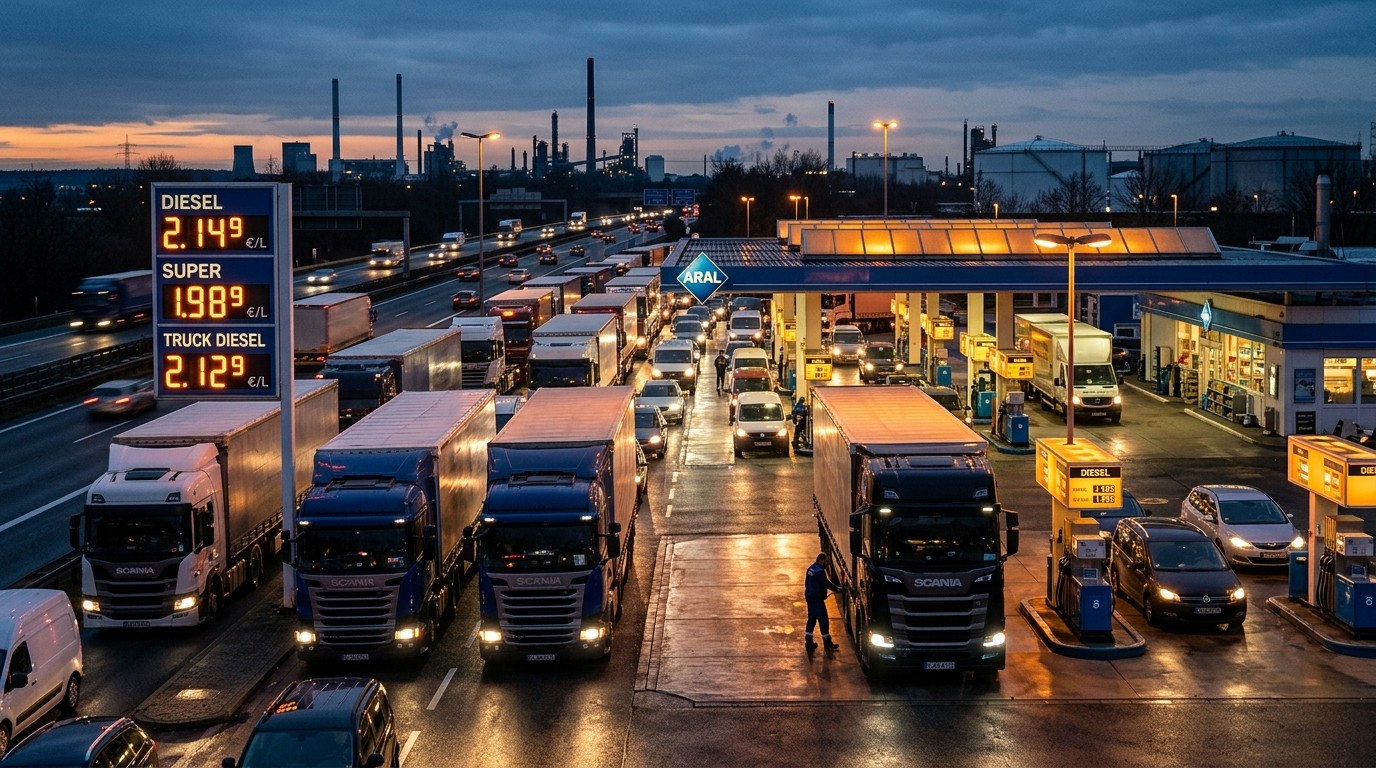
Consumer prices have jumped roughly 40% since late February. Institutional estimates circulating in market notes suggest European drivers now pay about 30 euros more to fill a diesel tank than they did before the latest conflict-related shock. Scale that across the region and you get more than 200 million euros in extra daily fuel costs.
That is a quiet tax on mobility. It hits commuters, delivery fleets, farmers, and construction crews. It also leaks into food prices and retail goods because almost everything moves on wheels at some stage. Perhaps the most interesting aspect is how quickly a wholesale futures move becomes a kitchen-table conversation. You do not need a trading screen for that. You need a receipt.
| Pressure Point | What Changed | Who Feels It First |
| Wholesale diesel futures | Sharp jump toward multi-year extremes | Traders, refiners, importers |
| Crack spread versus Brent | Widened toward 95 dollars a barrel | Refining margins and product buyers |
| Retail pump prices | About 40% higher since late February | Households and fleet operators |
| Daily extra fuel bill | Over 200 million euros across Europe | Consumers and transport-heavy firms |
I keep coming back to that daily extra cost. It is not a one-off invoice. It repeats. And repetition is how energy shocks migrate from the commodity page to the inflation print.
Factories Are Absorbing More Than Crude
Surging energy prices are not only squeezing consumers. They are raising operational uncertainty for businesses, especially in energy-intensive sectors. Beyond expensive crude, European firms are dealing with stacked costs in electricity, natural gas, and carbon credits. That stack is the part many casual readers miss. Diesel is loud. Power, gas, and carbon can be just as heavy on a plant’s books.
On the 22nd, a major British chemicals group said it would temporarily halt operations at three manufacturing plants. That kind of announcement is a flashing dashboard light. When a company pauses production, it is rarely about one expensive barrel. It is about the whole energy complex refusing to give the cost line a break.
Fresh survey data released on the 23rd showed the Eurozone composite Purchasing Managers Index rising to 53.1 in September, the strongest reading since April 2023. On paper, that signals faster expansion. Look one layer down and the picture gets messier. Input costs and selling prices both rose at their fastest pace since May. Survey analysts said corporate price metrics currently point to an underlying inflation rate around 4%.
Growth can look healthier on a headline index while energy costs quietly eat the margin that was supposed to fund the next hire, the next truck, or the next plant upgrade.
That tension is the heart of the story. Activity is not collapsing. Costs are climbing inside the expansion. I’ve found that this mix is harder for policymakers than a clean downturn, because the data argue in two directions at once.
Why The Crack Spread Matters More Than The Headline Barrel
People love quoting crude. It is simple. One number, one chart, one conversation. Diesel is messier. The crack spread tells you what refiners earn for turning crude into road fuel and heating product. When that spread explodes, either product is scarce, refining capacity is constrained, or logistics cannot move barrels to the right harbor on time. Sometimes it is all three.
A 95-dollar crack is not a normal weather bump. It is a signal that Europe is paying a scarcity premium for middle distillates. Think of it as the market shouting that the last available cargo is more valuable than the average barrel of crude sitting in a benchmark contract.
- Watch whether import volumes stabilize or keep sliding.
- Watch inventories in the main consuming hubs, not only headline crude stocks.
- Watch the front of the diesel curve versus next-year prices.
- Watch industrial downtime announcements in chemicals, metals, and glass.
- Watch how fast pump prices pass through into broader inflation surveys.
If those five stay hot together, the squeeze lasts. If one or two cool off, the market can still be expensive without being chaotic. Right now, too many of them are hot at the same time.
Households, Fleets, And The Quiet Second-Round Effect
A 40% rise at the pump since late February does not stay in the fuel tank. Delivery firms raise surcharges. Contractors bid higher. Food distributors revise routes. Then the supermarket ticket moves, and people call it grocery inflation even if the first spark was diesel.
There is also a behavioral layer. When filling a tank costs 30 euros more, some drivers cut weekend trips. Some small firms delay vehicle replacement. Some households shuffle other spending to keep commuting. None of that shows up neatly in a futures quote, but it shows up in retail traffic and services demand later.
Is every extra euro of fuel automatically a disaster? No. Wages and savings buffers differ across countries. Southern and northern Europe do not feel the same bill the same way. Still, a region-wide extra cost above 200 million euros a day is large enough to matter even if the pain is uneven.
The Industrial Bind: Power, Gas, Carbon, And Diesel Together
Energy-intensive companies rarely get to choose one fuel problem at a time. A chemicals site can face expensive process heat, expensive electricity for motors and compressors, carbon costs on emissions, and higher diesel for inbound and outbound freight. Stack those and a temporary shutdown starts looking rational rather than dramatic.
That is why the plant suspensions deserve attention. They are not proof that the whole Eurozone factory base is about to go dark. They are proof that the cost stack has reached a point where running at a loss is worse than pausing. Markets should treat that as a margin warning, not a curiosity.
Cost stack facing many European plants:
  Diesel and freight
  Electricity
  Natural gas
  Carbon credits
  Maintenance delayed by tighter cash flow
When cash gets tight, maintenance slips. When maintenance slips, outages rise later. That feedback loop is ugly and slow, which is why energy shocks can still be visible in industrial data long after the first futures spike fades from the headlines.
Growth Is Improving, But Inflation Is Getting Noisy Again
A composite PMI at 53.1 is not a recession signal. It is expansion. After a long stretch of soft readings, that should be welcome. The catch is the price components. Faster input-cost inflation and faster selling-price inflation in the same month tell you companies are both hurting and passing pain along.
An implied underlying inflation rate near 4% is awkward. It is high enough to keep real incomes under pressure and high enough to complicate rate-cut dreams. It is also not so high that the economy looks like 2022 all over again. The gray zone is the problem. Policy is hardest in the gray zone.
I’ve found that investors often over-weight the headline PMI and under-weight the price indexes inside the same report. That habit gets expensive in energy shocks. Activity can print green while margins print red.
What This Means For Monetary Policy
If energy prices stay stubborn, they can squeeze corporate margins and household spending at the same time. That combination raises inflation risk and growth risk together. For the European Central Bank, that is a nasty pair. One argument says hold policy tighter because energy is feeding prices. The other says ease because costly fuel will eventually cap demand.
Neither camp gets a clean win if diesel stays near current extremes. A durable energy shock can keep services inflation sticky even while manufacturers trim output. Then the recovery looks uneven: some service firms busy, some heavy industry cautious, consumers trading down.
If energy prices remain elevated, they could further squeeze margins and spending, add to inflation pressure, and make monetary policy more difficult, ultimately threatening the quality of Europe’s recovery.
That is the policy bind in one sentence. Recovery is not only about whether GDP is up. It is about whether the expansion can survive a fuel bill that refuses to normalize.
Reading The Forward Curve Without Getting Cute
The forward curve still shows diesel well above 150 dollars a barrel into next year. That does not guarantee those prices will print. Curves change. But it does tell you the market is not pricing a neat return to cheap middle distillates. Traders who want a quick mean-reversion story have to argue against that curve, not ignore it.
Why might the curve stay high? Limited spare export availability from key suppliers. Seasonal demand into winter heating and freight. Refinery maintenance risk. Geopolitical disruption that can close a route overnight. Any one of those can keep the crack supported. Together they create a floor under anxiety.
Why might it ease? A diplomatic thaw that restores some flows. Demand destruction if pump prices stay painful. A run of mild weather. Unexpected refining outages being resolved faster than feared. Possible, yes. Reliable, not yet.
Winners, Losers, And The Uneven Map Inside Europe
Not every country stands in the same spot on this map. Economies with heavier diesel vehicle fleets feel pump prices faster. Export manufacturers with thin margins feel input costs faster. Households that already spend a large share of income on transport have less room to absorb a 40% fuel jump.
On the other side, some refiners with available capacity can earn exceptional cracks when product is scarce. That sounds like a gift until you remember that policy risk, windfall debates, and demand destruction can follow fat margins. High cracks are profitable until they become politically loud.
- Transport-heavy economies feel retail diesel first
- Chemicals, metals, glass, and paper feel the broader energy stack
- Households with long commutes cut discretionary spending sooner
- Firms with pricing power pass costs through; others absorb and shrink margins
- Policy makers inherit a recovery that looks fine until the fuel line is included
How Businesses Can Think About The Next Few Months
I am not fond of generic advice that pretends every firm can hedge like a supermajor. Most cannot. Still, there are practical habits that separate companies that get surprised from companies that stay solvent.
- Separate diesel exposure from power and gas exposure instead of bundling them as “energy.”
- Revisit freight contracts before the next seasonal lift in road fuel.
- Stress-test margins at pump prices 10% to 20% above today’s receipt, not below it.
- Watch customer elasticity. Some buyers accept surcharges. Some walk.
- Keep an eye on plant-level cash, not only group-level averages.
None of that is glamorous. It is how you avoid discovering the shock after the quarterly numbers are already baked. In my view, the firms that stumble first are often the ones that treated diesel as a background cost rather than a strategic input.
The Inflation Path From Harbor To Shopping Basket
Energy inflation has a sequence. First wholesale product. Then retail fuel. Then transport services. Then goods that travel. Then wages if workers demand compensation for commuting costs. The later stages are the ones that keep central banks awake, because they linger after the tanker rates calm down.
Are we already in the later stages? Parts of them, yes. Pump prices have moved. Companies are lifting selling prices at the fastest pace since May. That is pass-through in real time. The open question is whether consumers can keep absorbing it without cutting volumes. If they cannot, growth cools. If they can, inflation stays annoying.
Either outcome is uncomfortable. That is why this diesel move is bigger than a trading session. It is a test of how much energy pain a still-expanding Eurozone can carry without losing the expansion.
What I Am Watching After The Spike
The 7% jump is the headline. The persistence is the story. I want to see whether export volumes from core suppliers stabilize. I want to see whether the crack stays near that 95-dollar neighborhood or mean-reverts once the first wave of restocking demand is done. I want to see if more manufacturers pause lines or if the chemicals halt remains an isolated decision.
I also want the next PMI price components. One hot month is a warning. Two or three start to look like a regime. And yes, I will keep an eye on that family-phone-call test. When relatives ask why the pump looks absurd, the market has left the specialist chat rooms and entered daily life.
Maybe the curve is too pessimistic. Markets overshoot. They do it often. But hoping for a clean unwind while imports are thinner and retail diesel is already up 40% is not analysis. It is wishful bookkeeping.
A Recovery That Has To Share The Road With Fuel Costs
Europe can grow and still feel poor at the pump. That sentence sounds contradictory until you live it. A PMI above 53 tells you more firms are seeing better orders or output. A diesel complex near historic highs tells you a slice of that improvement may be eaten by energy before it becomes profit, wages, or investment.
So where does that leave the outlook? Cautious, not panicked. The expansion signal is real. The cost signal is also real. The policy path is narrower than it looked a few months ago. And the consumer is already paying the bill in cash, not in theory.
If supply stays tight, the crack can remain wide and the extra daily fuel cost can keep grinding. If supply eases, prices can fall without instantly restoring last year’s comfort. Either way, diesel has moved from background noise to front-page constraint. That shift is worth taking seriously, even if tomorrow’s session is quieter than Wednesday’s.
The next few weeks will show whether this was a violent squeeze inside a still-functioning market or the start of a longer middle-distillate shortage. I lean toward “not short-term anymore,” because the curve and the pump receipts are saying the same uncomfortable thing. Europe can keep expanding. It just may have to do it with a much heavier fuel tank on its back.