

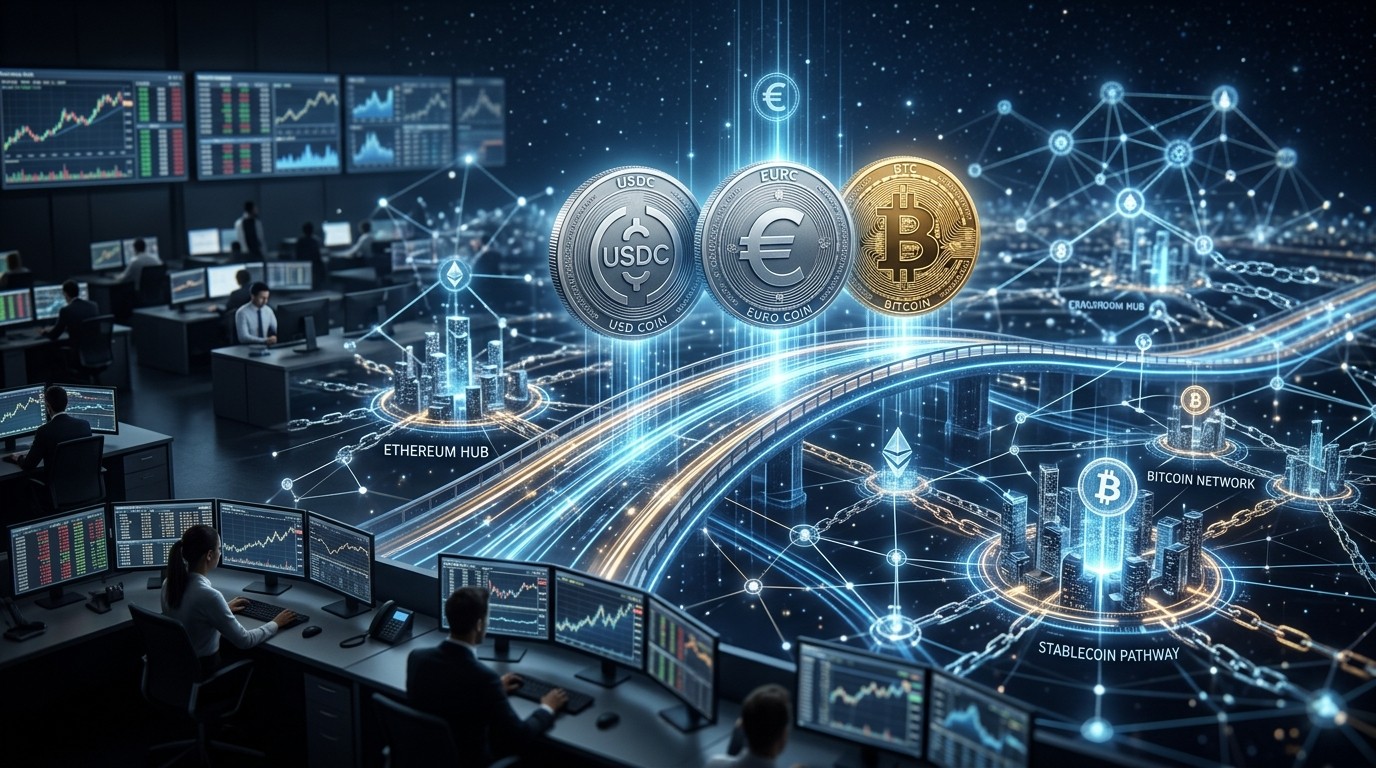
Circle Expands CCTP To EURC And CirBTC On Arc

Circle just pushed CCTP past USDC on Arc. EURC and cirBTC can now move natively on selected routes, but Gateway is still USDC-only. The gap between live rails and unfinished products is where the real story sits.
Financial market analysis from 24/09/2026. Market conditions may have changed since publication.
I keep coming back to the same question whenever a payments firm announces another interoperability upgrade: is this the moment cross-chain money stops feeling like a science project? Circle’s latest move on Arc does not settle that debate overnight, but it does change the texture of it. CCTP is no longer just a USDC pipe. Native EURC and cirBTC can now travel on selected Arc routes, and that is a bigger shift than a press line about “more assets” usually admits.
Why This Circle Expansion Matters Now
Arc went public in mid-September with USDC as gas, a permissioned founding validator set, and a promise that institutions would not have to stitch twenty networks together by hand. A week later, the interoperability layer arrived with CCTP, Gateway, and a Forwarding Service sitting inside the chain rather than hanging off it like an afterthought. Then the asset list grew. First the euro token. Then wrapped bitcoin. Then the claim that developers can treat these instruments as first-class travelers instead of awkward guests.
That sequence is fast even by crypto standards. It also creates a trap. People hear “expanded CCTP” and assume every Circle product now treats USDC, EURC, and cirBTC the same way. They do not. Routes differ. Gateway is still narrow. Pricing is preferential on Arc, yet not published as one tidy fee card. If you work in product, treasury, or market structure, those distinctions are the whole story.
I’ve found that the market often prices the headline and ignores the plumbing. This time the plumbing is the headline.
What CCTP Actually Does When It Leaves USDC Behind
CCTP started life as a burn-and-mint system for a dollar token. Burn on the source chain. Mint a native unit on the destination. No pool to drain. No wrapped IOU pretending to be the real thing. That design aged well because it kept the asset identical on both sides of the trip.
Extending the same model to a euro stablecoin and a bitcoin-backed token is not a cosmetic patch. It is a bet that the burn-and-mint habit can become a multi-asset habit. Circle’s current product language still frames CCTP as infrastructure that moves supported assets one-for-one between chains. For Circle-issued instruments, that still means destroy here, create there.
The useful part is not the slogan. It is the refusal to force every transfer through a liquidity pool that can gap, freeze, or quietly reprice the asset mid-route.
EURC arrived in the CCTP family earlier in September, first on a tighter pair of networks, then across a wider set once Arc launched. cirBTC followed a different path. Interop documentation currently ties the bitcoin-backed token to Arc and Ethereum. That is enough to matter. It is not enough to call the coverage complete.
In my experience, the first week after a multi-asset announcement is when teams over-promise internally. A payments lead hears “EURC is live” and assumes every corridor works. A lending desk hears “cirBTC can move” and assumes Gateway balances are already unified. Both assumptions are wrong today. Precision is the only adult response.
The Route Map Is Uneven On Purpose
USDC remains the most traveled asset in this stack. If a route exists in the current Arc interoperability design, the dollar token is usually the one that can use it. EURC currently sits on Arc, Avalanche, Base, Ethereum, and World Chain. cirBTC currently sits on Arc and Ethereum. Three assets. Three different footprints.
| Asset | CCTP Status On Arc Routes | Gateway Status |
| USDC | Broadest live coverage | Live on Arc and Ethereum balances |
| EURC | Arc, Avalanche, Base, Ethereum, World Chain | Listed as coming later |
| cirBTC | Arc and Ethereum | Listed as coming later |
That table is not a knock on the launch. It is a reminder that interoperability is a product surface, not a single switch. Circle can say the protocol now handles more supported assets. Developers still have to check the corridor before they write a transfer flow that looks identical for every ticker.
Perhaps the most interesting aspect is how honest the documentation is about the mismatch. Gateway unifies balances for USDC on Arc and Ethereum. EURC and cirBTC are flagged as future work. Legal language still describes Gateway as USDC-only software infrastructure. That is dull. It is also useful. Dull and useful is how serious rails get built.
Fast Transfers, Prepaid Fees, And The Gas Problem
Circle has been talking about sub-10-second Fast Transfer times on supported Arc routes. I like the number. I also like the caveat sitting next to it. Transfer times and fee estimates are not guaranteed. Chain choice, route choice, and network weather still decide the outcome. Anyone who has watched a “fast” bridge stall at the worst possible minute already knows why that sentence exists.
The Forwarding Service is the quieter piece. After CCTP finishes the asset movement, the service can relay the destination-chain transaction. Users do not always need a pocketful of the destination gas token just to complete a supported action. That sounds small until you remember how many retail and even professional flows die on the last meter because someone forgot the fee asset.
Earlier in September, CCTP also picked up prepaid Fast Transfer fees. Developers can quote and collect certain cross-chain charges on the source network. An application can show the recipient amount before the transfer fires. That is not glamorous. It is how you stop a checkout screen from lying.
- Quote the fee on the source chain instead of surprising the user later.
- Keep the destination amount visible before execution.
- Use forwarding so the last hop does not demand a second wallet ritual.
- Treat Arc pricing as preferential, not as a single published rate for every asset.
Circle has not posted one universal Arc transfer fee that covers USDC, EURC, and cirBTC together. Rates still depend on the asset and the route. I would rather see that honesty than a fake flat number that collapses the first time bitcoin-backed volume spikes.
Gateway Is The Unfinished Half Of The Story
Gateway is the product people confuse with CCTP because both live under the interop umbrella. They are not the same tool. CCTP moves a native asset from chain A to chain B. Gateway tries to present supported balances across networks as one available pile. On Arc at launch, that pile is USDC on Arc and Ethereum.
EURC and cirBTC support for Gateway is planned. No public date. Circle’s disclosures also stress that Gateway is non-custodial software. It does not hold, control, or transfer customer assets by itself. It has not been reviewed or approved by a state banking supervisor as a standalone regulated product, according to the current legal framing. That last point will matter to compliance teams even if builders shrug.
I’ve sat through enough product meetings to know how this conversation goes. Someone asks whether the app can treat euro balances the same way it treats dollars. The honest answer today is no. Someone asks whether bitcoin-backed inventory can sit in one virtual balance across Arc and Ethereum. Same answer. CCTP can move the tokens. Gateway cannot yet pretend they are one wallet line.
Confusing a live transfer protocol with a live unified-balance product is how integrations get rewritten three months later.
The April roadmap already pointed in this direction. CCTP had processed a very large cumulative volume of dollar transfers across more than twenty chains, and the next versions were meant to stretch the same model toward EURC and cirBTC. The late-September release turns part of that map into production. The Gateway half remains a promise with a “coming soon” sticker.
cirBTC Is Not Just Another Ticker On The Menu
Circle brought cirBTC to Arc shortly before the interop announcement. The company describes each token as backed one-for-one by native bitcoin held for holders, with reserve information available for on-chain checks. The issuer is Circle International Bermuda Limited, operating under a Bermuda digital-asset business license. That structure will not satisfy every critic of wrapped bitcoin. It does give institutions a named issuer and a documented reserve story instead of an anonymous wrapper.
There is also a credit angle. Eligible Circle Mint institutions can post cirBTC into third-party lending markets and borrow USDC. Morpho was first when that workflow went live. Supported Aave and Morpho applications on Arc are already in the conversation as places where the bitcoin-backed token can work as collateral. Deposit native bitcoin, mint cirBTC, post it, borrow dollars. That loop is the point.
Why pair that with CCTP between Arc and Ethereum? Because collateral that cannot move is half-useful. A desk that wants bitcoin exposure on one venue and dollar liquidity on another still needs a native path, not a pool that can wobble when both sides of the market get nervous at once.
Is wrapped bitcoin ever a perfect substitute for holding the coin itself? No. Anyone who says otherwise is selling something. The practical question is narrower. Can a regulated issuer create a transferable claim that lending markets will accept and that a burn-and-mint bridge can move without inventing a second credit risk? Circle is trying to answer that in production, not in a white paper.
EURC Turns Arc Into More Than A Dollar Island
Dollar stablecoins still dominate on-chain settlement. That is not news. What is news is a euro token getting the same native transfer treatment across a short list of serious networks, including a new institutional Layer 1 that uses USDC for gas. The combination is a little strange and a little smart. Gas stays in dollars. Value can move in euros. The chain does not have to pretend Europe does not exist.
Cross-border desks have wanted this shape for years. Invoice in euros. Settle without dragging a nostro account through a weekend. Keep the destination asset native instead of wrapping it into a dollar-shaped lookalike. CCTP does not magically solve banking hours, sanctions screening, or local licensing. It does remove one excuse that used to sound technical and was really just operational friction.
I do not think EURC becomes the default unit of account on Arc next month. Dollar gravity is still dollar gravity. But a payments network that can only speak one fiat language will keep losing conversations that start in Frankfurt, Milan, or Paris. Giving EURC a native corridor is how you stay in those conversations.
Third-Party Tokens Get A Different Door
Circle’s interop stack is not a private club for Circle-issued assets. Third-party tokens can move through wrapping and a Crosschain Token Standard. Issuers who need allowlists, transfer caps, pause switches, upgrades, and governance hooks can use that standard instead of maintaining a different contract and a different bridge on every chain.
Circle says it does not keep override power over those custom contracts. Issuers stay responsible for structure, operating rules, and regulatory duties. That sentence is doing a lot of work. It tells developers the standard is a kit, not a custody relationship. It also tells supervisors that Circle is not volunteering to be the hidden administrator of somebody else’s token.
CCTP’s updated architecture can support burn-and-mint for native supported assets and lock-and-mint where wrapping is the better fit. Bridge Kit packages the flows into an SDK. Arc Studio sits next to that as an AI-assisted build environment for teams that do not want to wire every service by hand. The examples floating around the launch range from cross-border payments to software billing to machine-to-machine settlement. Some of those demos will be fluff. A few will not.
Arc’s First Week Was Not A Soft Opening
Public mainnet arrived on September 16 with deterministic sub-second finality, USDC fees, and a founding validator list that reads like a roll call of market infrastructure. Names from asset management, market utilities, exchanges, card networks, remittances, and global banking all sat in that first set. Circle talked about more than one hundred institutional and ecosystem builders and more than one hundred applications at launch. Those figures are launch theater until they produce durable volume. They still signal who the chain is for.
Interop across more than twenty blockchain ecosystems was part of the opening pitch through CCTP and Gateway. Then the asset layer sprinted. cirBTC on September 21. A stablecoin FX product on September 22. Integrated interop on September 23. That FX product uses Arc for around-the-clock stablecoin foreign-exchange settlement, request-for-quote pricing, and atomic payment-versus-payment. If that design holds, the chain is not only a transfer rail. It is a settlement clock that does not close.
Circle minted a 10 billion ARC genesis supply before launch and has talked about exploring a move from Proof of Authority toward Proof of Stake in 2027. The company also says the genesis mint is not a promise to float a public token. Treat that as a live option, not a calendar invite.
What Builders Should Actually Ship First
If I were sitting with an integration team this week, I would not start with a grand multi-asset wallet vision. I would start with the routes that exist.
- Map USDC, EURC, and cirBTC separately. Do not write one abstract “Circle asset” object and hope the corridors match.
- Use CCTP where native movement is the requirement. Do not wait for Gateway if the user only needs the token on the other chain.
- Keep Gateway features behind a USDC-only flag until euro and bitcoin-backed balances are truly live.
- Surface prepaid fees and destination amounts before the user confirms.
- Assume forwarding will save some flows and fail others when a destination action is outside the supported set.
That list looks conservative. Good. Conservative is how you avoid a support queue full of people who thought “coming soon” meant “already in production on Friday.”
There is a temptation to market this as the death of traditional bridges. Resist it. Pool-based bridges still exist because they carry assets Circle will never issue. Lock-and-mint still exists because third-party issuers want control knobs. Burn-and-mint is better when the issuer and the protocol are aligned. It is not a religion.
The Institutional Read Of The Validator Set
Permissioned founding validators make crypto natives uneasy. Fair. Open validator sets are part of the original myth. They are also not how DTCC-shaped institutions usually join a network on day one. Arc chose the boring door. Known operators. Named brands. A chain that looks less like a campus experiment and more like market plumbing.
Does that make the network “decentralized enough”? That fight will run for years. The nearer question is whether those validators create a coordination surface that payments, custody, and market utilities can trust at 2 a.m. on a Sunday. Sub-second finality plus dollar gas plus named operators is a package designed for that hour, not for a conference panel.
I’ve found that institutions care less about the purity debate than about failure modes. Who can halt a contract? Who publishes reserves? Who stands behind a wrapped bitcoin claim? Who prices the FX ticket? Circle is answering those with issuer entities, licenses, product disclosures, and a validator roster. Critics will still want more. They should. The answers are still more complete than most wrap-and-pray designs.
Risks That Do Not Belong In The Fine Print Alone
Smart teams will keep a short risk list next to the integration checklist. Transfer times can slip. Fees can move with route conditions. Gateway language can lag the marketing. Wrapped bitcoin always carries issuer and reserve-process risk, even with on-chain attestations. A euro token still lives inside a regulatory weather system that is not identical to the dollar token’s weather system. Proof-of-Authority now and Proof-of-Stake later is a governance path, not a finished constitution.
There is also concentration risk hiding in plain sight. If too many applications treat Arc as the only place where these three assets feel native together, a disruption on that chain becomes a multi-asset event instead of a single-token event. Interoperability reduces some silos. It can create a new one if everyone piles onto the same preferred routes.
None of that makes the launch unserious. It makes the launch adult. Adult products publish the limits. Childish products hide them under a word like “seamless.”
Where The Roadmap Still Has Blank Squares
Gateway for EURC. Gateway for cirBTC. Broader cirBTC corridors beyond the Arc-Ethereum pair. A public, durable fee schedule that does not force every desk to discover pricing in production. A clearer timeline for any token associated with the genesis mint. Those are the blank squares.
Circle does not need to fill them this quarter to make the September work count. Native multi-asset CCTP on a new institutional chain is already a real increment. The mistake would be to sell the increment as the finished city.
Live today:
  CCTP for USDC, EURC, cirBTC on specified routes
  Gateway for USDC balances on Arc and Ethereum
  Forwarding on supported destination actions

Still queued:
  Unified EURC balances
  Unified cirBTC balances
  Wider bitcoin-backed corridors
  Any public ARC token decision
If you only remember one frame from this launch, remember that list. It keeps the excitement honest.
A Practical View For Treasurers And Product Leads
Treasurers should ask a blunt question. Does this reduce the number of accounts, wrappers, and weekend gaps in a flow we already run? If the answer is yes for dollar movement across Arc and Ethereum, the feature is usable now. If the answer depends on a single euro balance across five chains, wait. If the answer depends on bitcoin-backed inventory behaving like cash in a unified dashboard, wait longer.
Product leads should ask a different blunt question. Can we explain the asset differences in the interface without a footnote novel? Users will not study route matrices. They will tap send. If the app implies that every Circle asset travels the same highways, the app is lying. Better to show fewer buttons that work than a beautiful map with closed roads.
Market makers and lending teams have the most immediate toy. cirBTC as collateral, USDC as borrowable cash, CCTP as the truck between Arc and Ethereum. That triangle can generate real inventory movement. It can also concentrate liquidation risk if the wrapper, the lending pool, and the bridge route all lean on the same issuer complex. Diversify the venues even when the token looks native.
Why The Tone Of This Launch Feels Different
Crypto product news often sounds like a festival. This one sounds like operations. Preferential pricing. Prepaid fees. Forwarding. Coming soon labels. Named validators. Reserve pages. That tone is not an accident. Circle is trying to sell reliability to people who get fired when a settlement fails.
I happen to think that tone is the right one. Not because markets should be joyless. Because money movement is allowed to be slightly boring if it is correct. The industry spent years making bridges exciting. Excitement is a terrible attribute in a pipe.
A good transfer protocol should disappear into the application. The user should notice the money, not the machinery.
Arc is not invisible yet. The brand is loud. The validator list is loud. The asset drops are loud. Give it a year of quiet transfers and the volume will tell us whether the machinery learned to vanish.
The Human Layer Behind All This Machinery
It is easy to write about burn-and-mint as if nobody lives at the ends of the transfer. Somebody does. A payments operator trying to pay a supplier before a cutoff. A fund moving collateral between a lending market and a trading venue. A fintech that cannot ask a customer in another country to buy a gas token they will never use again. Those people do not care that CCTP expanded. They care that the amount that left is the amount that arrived, on time, in the unit they booked.
That is why the prepaid fee work and the forwarding service may matter more than the ticker list. Tickers get applause. Arrival amounts get trust. Trust is the scarce asset in this market, and it does not mint itself.
Will EURC corridors change how European firms treat on-chain cash? Maybe, if banking partners accept the operational story. Will cirBTC become standard collateral instead of a niche wrapper? Only if reserves stay boring and liquidations stay orderly. Will Gateway’s multi-asset future arrive before teams build their own balance logic? That depends on Circle’s calendar, which is still unpublished.
I would not bet the firm on a date that does not exist. I would bet a sprint on the routes that do.
Closing The Loop Without Pretending The Map Is Finished
Circle expanded CCTP on Arc beyond a single dollar token. That sentence is true. Native EURC transfers now sit on a defined set of chains. Native cirBTC transfers now sit between Arc and Ethereum. Gateway still speaks dollar first. Third-party issuers have a standard if they want control. Bridge Kit and Arc Studio try to make the stack usable for teams that are tired of assembling bridges like furniture with missing screws.
The launch week around Arc compressed a lot of roadmap into a few calendar days. Compression creates energy. It also creates blur. Stay with the details and the blur clears. Three assets. Uneven routes. One unified-balance product that has not caught up. A chain built for institutions that still has to prove volume the unfashionable way: by moving money when nobody is watching the announcement thread.
If you came here hoping for a simple verdict, here is mine. This is a real step in multi-asset native transfer design. It is not the finished interop layer some decks will now claim. Use what is live. Label what is not. And keep a little skepticism handy, the friendly kind, the kind that asks whether the euro and the bitcoin-backed token will still look first-class when the next status page is yellow instead of green.
Bitcoin will be to money what the internet was to information and communication.


Social Media Firm Sues Ex Partner Over Casino Fund Claims

US Overseas Stablecoin Push And Treasury Demand
Related Articles

Global Payments’ $24B Worldpay Deal Shakes Markets
Global Payments’ $24B Worldpay deal sent its stock plummeting 17%. What does this mean for the payment industry and your portfolio? Click to find out...
Embracing Solitude After Heartbreak: A Guide
Feeling lost after a breakup? Learn how to embrace solitude, rebuild your confidence, and rediscover yourself. Ready to heal? Click to find out how...
Midday Movers: Apple, Nvidia, Instacart Shine
Which stocks are soaring or sinking today? From Apple’s dip to Instacart’s rally, dive into the midday market moves that matter. Curious about what’s next?