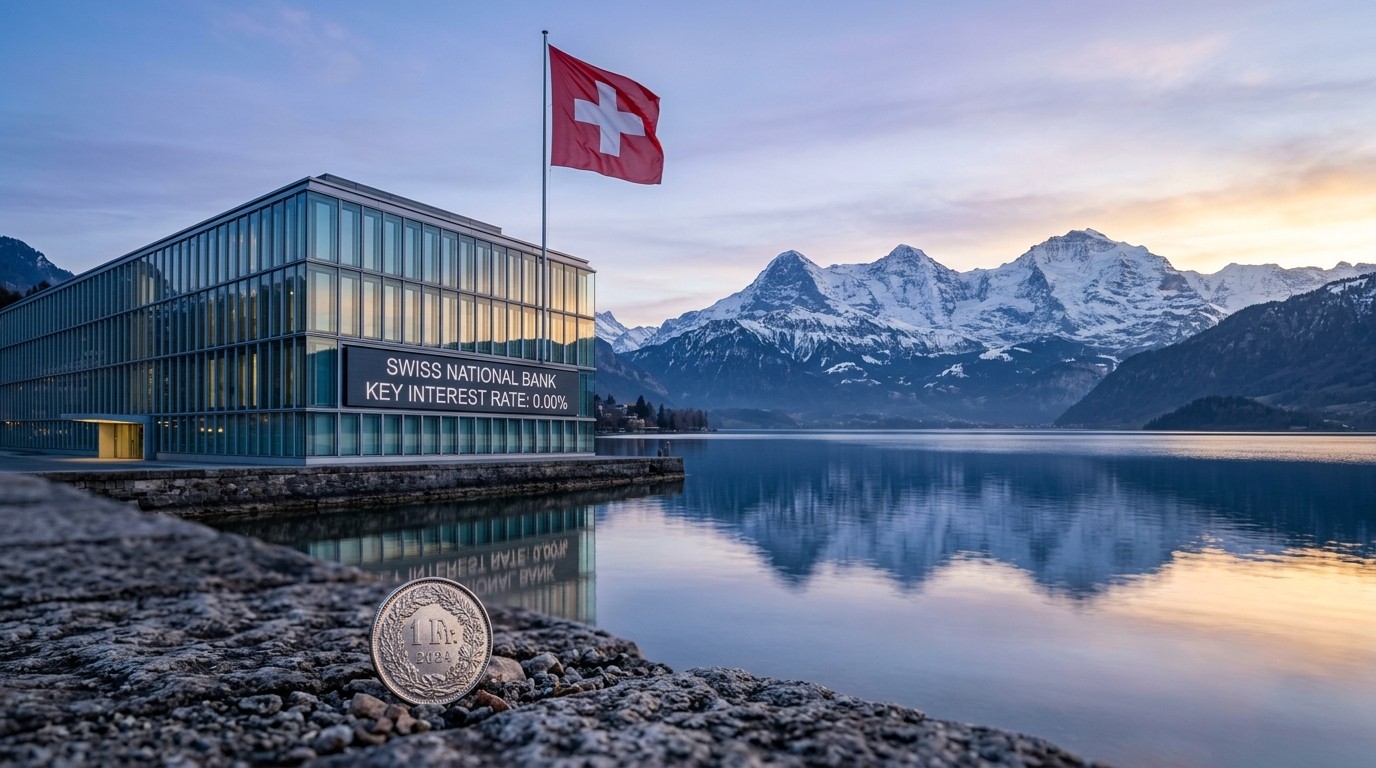

Have you ever watched a country sit still while almost everyone else starts moving? That is the feeling around Swiss policy this week. The Swiss National Bank held its key rate at 0% even as several major peers have already started tightening. Inflation is still low. The franc is still doing a lot of quiet work. And yet markets are not treating this pause as a permanent state of mind. I have found that the most interesting rate decisions are rarely the ones that shout. They are the ones that look calm on the surface and restless underneath.
Why A Zero Rate Still Makes Sense Right Now
Thursday’s hold was not a surprise in the narrow sense. Price growth remains well inside the official band. August inflation printed at 0.8%, lifted a little by gasoline, diesel and heating oil, but nowhere near the heat seen in the United States, the United Kingdom or the euro area. The Swiss objective is not a single 2% point. It is a range from 0% to 2%. That difference matters more than people admit.
When your target is a corridor rather than a bullseye, you can live with small moves in energy without treating them as a regime change. In my experience, that flexibility is one reason Swiss policy often looks “late” to outsiders and “careful” to people who actually watch the local data. The bank is not ignoring the world. It is measuring a different kind of pressure.
A Quiet Inflation Story That Still Bites At The Edges
Low inflation is not the same as frozen inflation. Fuel costs did push the latest reading higher. Imports still matter. Households still notice the pump. The difference is scale. Energy is a thinner slice of the Swiss basket than it is next door. Hydropower and nuclear capacity also take some of the sting out of regional energy shocks. That mix does not make Switzerland magic. It just changes the speed at which a global price wave arrives.
Perhaps the most interesting aspect is how little of the debate is about domestic wage spirals. Expectations have stayed anchored for years. When people already believe prices will stay modest, a central bank does not have to prove itself with a dramatic first hike. It can wait, watch the franc, and keep the door open.
When a shock hits, a central bank that can rely on low inflation expectations will have an easier time keeping inflation low.
– Economics professor and policy adviser
That line is simple and a little unfashionable. It also explains a lot. Switzerland has lived with modest price growth for so long that firms, unions and households do not immediately rewrite their plans after one noisy month of oil. Japan has a similar memory, even if the policy tools look different. Memory is a policy instrument. People forget that.
The Franc Is Still Doing Half The Job
Talk about Swiss rates without talking about the franc and you are missing the plot. A strong currency cheapens imports. Imports are not a side note here. They are a large part of daily life. When the franc rises, it leans against inflation the way a rate hike would, only faster and sometimes more bluntly.
Last year, as investors hunted for shelter in a messy market, the franc climbed more than 12% against the dollar. This year the dollar has clawed back around 4%. That reversal is small compared with the earlier surge, but it is not nothing. A softer franc means imported goods are a bit less of a free lunch. If that drift continues, the case for an earlier hike gets louder even if headline inflation is still under 1%.
The bank also watches the exchange rate because a sudden jump in the franc can choke activity. That is why officials talk about appropriate monetary conditions rather than a single number on a board. Rate, currency, and credit conditions travel together. I still think too many market notes treat the policy rate as if it lives alone.
- A firmer franc cools imported prices and can delay a hike.
- A weaker franc can pull inflation forward and bring the first move closer.
- Officials have used foreign-exchange intervention before and have not ruled it out.
- Energy and commodity spikes are partly absorbed by currency strength.
Markets Are Already Pricing A Turn
Here is where the calm story gets twitchy. Traders see roughly even odds of a December hike. They also see more than a 90% chance that lifting starts by early 2027. Pricing points to a key rate of at least 0.75% by next September. That is not a panic path. It is a slow staircase. Still, it is a staircase, not a flat line.
Some bank economists had been thinking about a first move as late as mid-2027. Then the franc slipped more than 2% against the euro and more than 1% against the dollar after the June meeting. Oil stayed firm. The United States and the euro area looked more resilient than the gloomiest forecasts. Those three facts together changed the tone. Nobody is screaming that inflation will blow through 2% in the next year and a half. They are saying the risk of an earlier surprise is no longer tiny.
And yes, this institution has a habit of surprising people. That reputation is earned. If you only look at the latest print and assume path dependence, you will get caught. I have learned to treat Swiss communication as spare on purpose. Spare language leaves room to move.
What The So-Called Safe Haven Dividend Actually Means
There is a useful phrase floating around finance classrooms in Switzerland: the safe haven dividend. It sounds like marketing. It is not, not entirely. Capital flows in when the world feels ugly. Those flows support the franc. The stronger franc then dampens imported inflation. Low inflation then gives the central bank cover to keep rates below those of larger peers. It is a loop, not a slogan.
Unlike some larger economies, Switzerland imports credibility as much as it imports goods. Foreign capital supports the franc, the franc curbs imported inflation, and low inflation supports lower rates.
That loop can break. If the franc slides for long enough, imported prices stop helping. If global risk appetite stays hot, the safe-haven bid thins out. If energy stays expensive while the currency softens, the 0.8% print will not look as sleepy. None of that is happening in a dramatic way today. It is happening at the margin. Policy is made at the margin.
Fiscal rules play a quieter role. A strict debt brake and a culture of balanced budgets mean the government is not constantly bidding up yields to fund a wide deficit. Lower public borrowing pressure is one more reason Swiss rates can sit below those in countries that must keep bond investors interested every week. It is not the whole story. It is part of the furniture.
Real Rates Tell A Less Exotic Tale
People love to say Switzerland is an outlier. Look at the real rate and the romance fades a little. A 0% policy rate with inflation near 0.8% gives a real rate of about -0.8%. In the euro area, a 2.5% policy rate with inflation near 3.2% gives a real rate close to -0.7%. The United Kingdom and the United States are in a similar neighborhood, even if a bit less negative. Different nominal numbers. Similar real stance.
| Area | Policy Rate Snapshot | Inflation Snapshot | Rough Real Rate |
| Switzerland | 0.0% | About 0.8% | About -0.8% |
| Euro area | About 2.5% | About 3.2% | About -0.7% |
| United States and United Kingdom | Higher nominal levels | Higher inflation | Slightly less negative |
So the Swiss story is less “zero forever” and more “low inflation that refuses to leave.” Once expectations sit there, every other number looks unusual until you adjust for prices. That is why I get impatient with headlines that treat 0% as a museum piece. It is a number that fits a long local history.
Peers Are Hiking. Switzerland Is Watching The Distance Grow
The European Central Bank, the Federal Reserve and the Bank of Japan have already started raising rates to deal with firmer prices. Canada and the United Kingdom are widely expected to follow later this year. That is a lot of gravity on one side of the table. Rate gaps affect currencies. Currency gaps feed back into inflation. You can hold at zero for a while in that environment. You cannot pretend the gap is costless.
If Swiss rates stay at the floor while others climb, the franc can come under pressure simply because yield hunters have somewhere else to go. A softer franc then imports a little more inflation. At some point the hold stops looking prudent and starts looking stubborn. Markets are betting that point arrives before early 2027, and maybe as soon as December.
Would a December hike be a shock? Only if you have not been watching the currency. If you have, it looks like a close call. Close calls are where this bank likes to live.
Energy, The Basket, And Why Oil Matters Less Here
Energy is about 3.5% of the Swiss inflation basket, versus something closer to 7% in the euro area. That single fact does a lot of work. A spike that rattles households in neighboring countries shows up as a nudge in Swiss data. Add hydropower and nuclear into the mix and you get a system that is not fully sealed off, but is better insulated than the region around it.
Insulation is not immunity. Diesel and heating oil still moved the August number. Winter demand still matters. A weaker franc plus firm oil is the combination that would make me most nervous if I were sitting in that meeting. One of those two is already flickering. That is enough to keep December alive as a live date rather than a curiosity.
- Watch the franc against both the euro and the dollar, not just one pair.
- Watch oil and heating costs into the colder months.
- Watch whether imported goods prices start to firm after the recent currency dip.
- Watch whether market odds for December stay near a coin flip or drift higher.
Intervention Is The Unspoken Tool In The Drawer
Swiss policy is not only about the policy rate. Officials have stepped into foreign-exchange markets before to steady the currency, and they have said they can do it again. That option changes the hiking calculus. If the franc surges too hard, they can lean against it without slamming the domestic economy with a surprise tightening. If the franc slumps, a rate hike and verbal guidance can travel together.
Flexibility sounds vague until you remember how often rigid frameworks get embarrassed by a currency swing. I would rather have a toolkit that looks messy on a slide deck and useful on a bad Tuesday. That is the Swiss habit. It frustrates model builders. It has also kept inflation inside a narrow band for a long time.
What A Hiking Cycle Would Look Like If It Starts
Do not picture an emergency sprint. Picture small steps. Markets already sketch a path toward at least 0.75% by next September. That implies more than one move, not a single heroic jump. The first hike would be a signal as much as a squeeze. It would tell households and firms that the floor is no longer a philosophy. It would also tell currency traders that yield differentials will not stay this wide forever.
Would mortgages and corporate credit feel it immediately? A little. Switzerland has lived with cheap money for so long that even a quarter-point can change the mood. But the bigger effect may be through the franc. A modestly higher rate can support the currency just enough to keep import prices from accelerating. That is the neat version. The messy version is a hike that arrives after the franc has already slipped, which means officials would be chasing prices rather than pre-empting them.
Timing is the whole argument. Hike too soon and you tighten into an economy that did not need the extra brake. Hike too late and you let a soft currency plus firm oil rewrite the inflation story you spent years protecting. That is why December is interesting. It sits right on the fault line.
How Households And Firms Should Read A Hold That May Not Last
If you live in Switzerland, a 0% headline can feel like background noise. It should not. Funding costs, lease negotiations, and import-heavy businesses all sit downstream of this decision. A hold today is still cheap money. It is not a promise that cheap money is a lifestyle.
Exporters feel the other side. A strong franc is a headwind for sales abroad even as it helps consumers at home. A milder franc is the reverse. Policy that tries to keep conditions “appropriate” is trying to avoid picking one side too hard. That balancing act is why statements often sound cautious to the point of boredom. Boredom can be a feature.
For investors, the lesson is not “Switzerland never hikes.” The lesson is “Switzerland hikes when the currency stops doing the work.” That is a different trigger from the ones used in larger economies. If you apply a standard global playbook without that filter, you will keep calling Swiss officials sleepy right up until they move.
Simple watchlist:
  Inflation still inside 0%–2%
  Franc direction since the last meeting
  Oil and heating costs
  Market odds for December versus early 2027
  Real-rate gap versus major peers
The Credibility Loop And Why It Can Fade
Low inflation expectations are an asset. Assets can be spent. If people start to believe that a softer franc plus global prices will push Swiss inflation toward the top of the band and beyond, the old loop weakens. Then the bank would have to spend more of its reputation on action rather than patience. That is the risk hiding inside an otherwise gentle 0.8% print.
I do not think that break is imminent. I do think it is the right risk to keep on the desk. Credibility is easier to keep than to rebuild. Swiss history is full of moments when officials moved earlier than the consensus because they wanted to protect that asset. Markets remember those moments even when they pretend not to.
Overall this is a story of low inflation that persists through the years and anchors the expectations of all economic players.
That sentence is the cleanest summary I have heard in a while. It is also a warning. Persistence is not a law of nature. It is a habit that policy, currency and fiscal restraint keep feeding. Remove one of those feeds and the habit can change.
What I Will Be Watching Into Year-End
First, the franc. Not a one-week wobble. A trend. Second, whether energy stays firm as heating demand rises. Third, whether imported goods prices stop falling. Fourth, whether December pricing stays near 50-50 or marches toward a done deal. Fifth, the tone of official language around exchange-rate conditions. When that language gets sharper, the hold is living on borrowed time.
None of this requires a crisis. It only requires a few more months in which the currency is a little weaker and the world is a little firmer than the last forecast. That is a very ordinary set of conditions. Ordinary conditions have a way of ending extraordinary rate floors.
So yes, Switzerland kept the key rate at zero. The decision fits the inflation print, the energy mix, the fiscal rules and a long reputation for patience. It does not freeze the future. Markets are already sketching the first steps off the floor. The only real argument left is the calendar. December or later. That is a narrower debate than it looks, and it will be settled by the franc as much as by the next inflation release.
If you came here hoping for a simple story about a stubborn central bank, you will leave with something less tidy. A zero rate can be both justified today and temporary tomorrow. That tension is the point. Watch the currency. Watch the oil bill. Watch whether patience starts to look expensive. The hold is real. The hiking cycle, according to the people who price it every day, is already on the calendar. The only open question is how long Switzerland can keep asking the franc to do the work that a higher rate would otherwise do.