
Have you noticed how many people talk about their cats the way they used to talk about their dogs? I have. In my own circle, the last three pets people brought home were cats, and two of those households had previously sworn they were “dog people.” That small shift at the dinner table now shows up in quarterly numbers. Shoppers are still careful with fuel and groceries, yet they keep reaching for cat food, cat treats, bedding, and furniture. Dog products, by contrast, look softer. The contrast is not a rumor. It is showing up in earnings conversations, store mix, and adoption patterns, and it is forcing pet retailers to rethink what “the pet aisle” even means.
Why Cat Spending Is Outpacing The Dog Aisle
Industry groups recently estimated that cat ownership rose about 5% in 2025, after a much sharper jump the year before. Roughly 53 million households now keep cats. That is not a fashion wave. It is a living arrangement story. Cats fit smaller homes. They cost less to board. They do not need a yard. They tolerate a renter’s schedule. When money feels tight, those details matter more than a cute slogan on a bag of kibble.
I have found that people rarely admit they chose a pet for logistics. They talk about personality. Fine. Personality counts. But logistics is what shows up at the register. A cat can live well in a one-bedroom. A large dog in that same space becomes a daily negotiation. If you rent, the negotiation gets louder. That is why cat food sales can rise even while households watch every other line item.
Dog seems to be worsening; cat seems to be strengthening.
– Retail executive, recent earnings remarks
That blunt split is the heart of the story. Packaged-food companies with both cat and dog brands have described double-digit growth in cat food and high-single-digit declines in dog food in the same period. Net sales for an entire North American pet segment can look almost flat because one side offsets the other. Flat is not failure. Flat with a rotating mix is a warning light. The customer is still spending. The customer is just spending on a different animal.
The Ownership Shift Behind The Shelf
Adoption numbers tell a quieter version of the same tale. Dog adoptions have eased. Cat placements have held up better. Executives keep repeating a simple line: households are taking in more cats and fewer dogs. You can argue about why. You cannot argue with the direction.
Perhaps the most interesting aspect is how ordinary the reasons sound. Apartments. Hybrid work that still includes long days away. Higher vet bills for large breeds. Breed restrictions in leases. A younger renter who wants a companion without a 90-minute walk after a late shift. None of that is glamorous. All of it is durable.
- Cats generally need less outdoor time and less boarding.
- Many leases are simpler for cats than for medium or large dogs.
- Treats, furniture, and specialty wet food create repeat trips.
- Smaller living spaces favor animals that use vertical room.
- Care routines can fit irregular work hours more easily.
Does that mean dogs are going away? Of course not. It means the growth engine moved. If you run a pet chain, you do not get to wait for the engine to move back. You stock what walks out the door.
What Retailers Are Actually Saying
On recent calls, a major packaged-food company pointed to strong cat brands while conceding that dog recipes, packs, and messaging need a reset. One operator said the firm had already lived through a similar slump in a cat line a few years ago. The fix took 18 to 24 months. Product, pack, marketing, the whole proposition. That timeline matters. Soft dog sales are not a one-quarter weather event if the brand itself feels tired.
An online pet retailer described the same split in plain language. Dog was worsening. Cat was strengthening. A national specialty chain said second-quarter gains came after it leaned into cat parents with new treat lines, supplements, bedding, and furniture. The chain also stressed diversification: services, companion animals beyond dogs, and a cat mix that can carry the store when the dog side is quiet.
It just shows why it is so important to be diversified. Great trends in cat, growing companion animal, services growing. You cannot rely solely on dog.
In my experience, that last sentence is the one investors should underline. A pet retailer that still thinks of itself as a dog company with a cat corner is late. The shopper already reordered the house.
Price Pressure Did Not Kill Premium Cat Food
Households are not pretending inflation disappeared. Fuel and groceries still sting. Yet cat parents keep trading into better wet food, functional treats, and furniture that looks like it belongs in a living room rather than a garage. That is not irrational. A cat’s food bowl is a daily ritual. The spend is frequent and visible. People cut elsewhere first.
I keep coming back to frequency. Dog food bags can be large and infrequent. Cat feeding often looks like a small, premium, repeat purchase. Pouches. Cans. Toppers. Dental treats. That basket is easier to dress up. It is also easier to defend when a shopper is trying to feel like a good caretaker on a tight week.
| Category | Recent Direction | What It Signals |
| Cat food and treats | Stronger | Ownership plus premium mix |
| Dog food | Softer | Fewer adoptions and brand fatigue |
| Cat furniture and bedding | Improving | Home setup spend, not just calories |
| Services | Resilient at diversified chains | Less tied to one species |
Look at that table long enough and the strategy writes itself. You do not abandon dogs. You stop treating dogs as the only growth story.
Apartments, Renters, And The Quiet Economics Of Space
Space is the underrated character in this plot. A cat uses shelves, windowsills, and a tree in the corner. A dog uses floor, hallway, and the sidewalk outside. Cities keep adding renters. Renters keep adding pets that fit the lease. I am not saying every new cat lives in a studio. I am saying the studio is no longer a barrier.
There is also the time budget. A tired professional can scoop a box and refill a puzzle feeder. A tired professional cannot always offer a long, consistent walk. Guilt is a powerful shopper. Cat parents often convert that guilt into better food and better indoor enrichment. Dog parents facing the same crunch may delay a new bed or trade down on food. Different coping styles. Same economic pressure.
Is that fair to dogs? Not really. Dogs did not change. Housing did. Work did. The cost of veterinary care did. When those three move together, the “easier” companion wins more first-time homes.
Brand Work Still Matters On The Dog Side
It would be lazy to blame every soft dog number on adoption. One operating chief said as much. The company has to relook at product, packaging, marketing, and communication. That is a brand problem wearing an industry costume. I have seen this movie in other aisles. When a category cools, weak brands get exposed first. Strong brands still hold price and shelf.
- Audit whether the recipe still matches what owners say they want.
- Fix packs that look dated next to newer cat pouches.
- Talk to the owner about health outcomes, not just protein percentages.
- Give the dog line a distinct reason to exist besides “we have always sold it.”
- Measure repeat, not just launch noise.
Eighteen to twenty-four months is a long wait if you are a public company. It is a short wait if you are rebuilding trust. The cat line that recovered after that kind of work is the proof point sitting inside the same earnings script.
How Chains Are Rewriting The Store
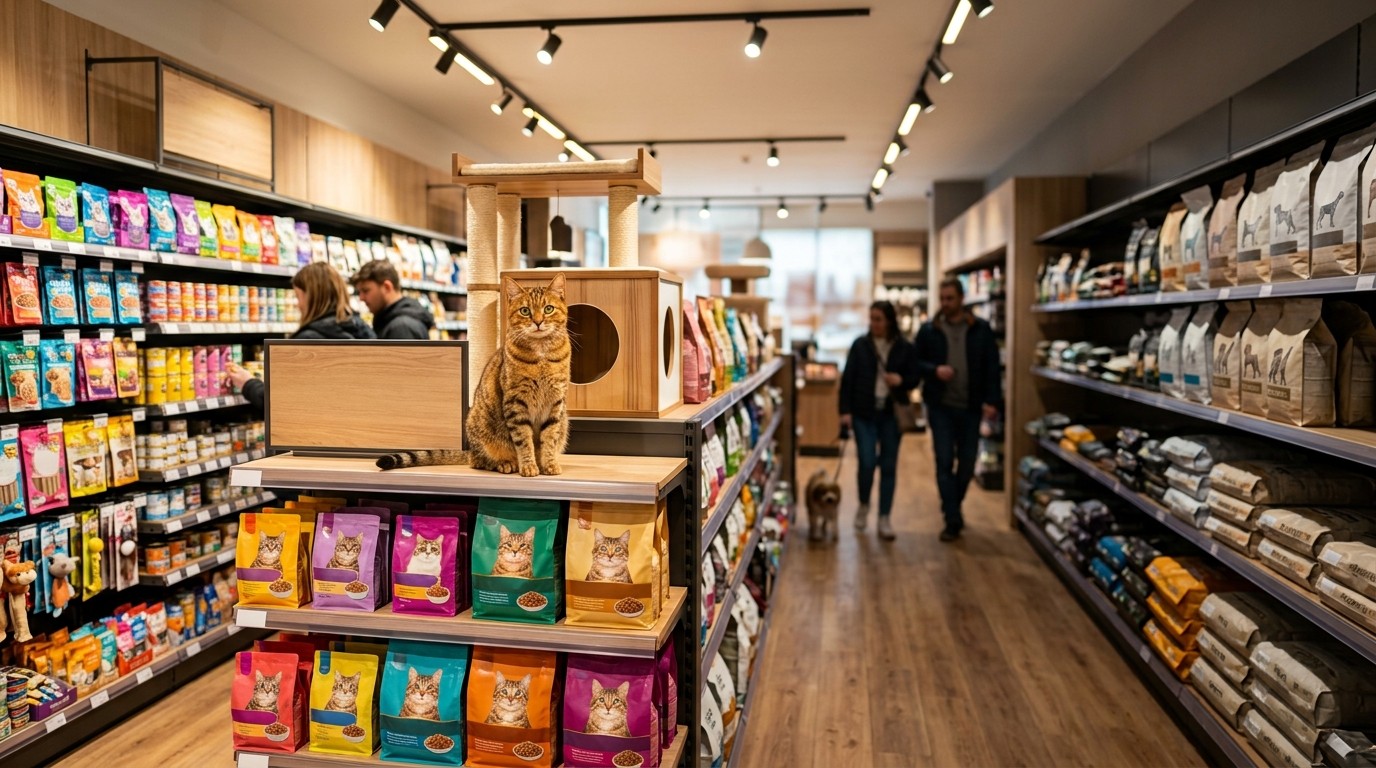
Walk a well-run pet store this year and the merchandising tells on itself. Cat trees nearer the front. Treat walls with more feline SKUs. Endcaps that look like living rooms. Dog aisles still large, still essential, just less electric. That is merchandising as confession.
New treat brands aimed at cat parents are not a side project. They are a bet that the shopper wants small pleasures that feel specific. Candy-shop framing for cat treats sounds playful. The inventory logic is serious. High-impact brands that “resonate with cat parents” showed up in consumables, supplements, bedding, and furniture in the same quarter. That is a full-room strategy, not a kibble strategy.
Services help too. Grooming, vet clinics, training, and adoption partnerships spread risk. If dog adoptions dip slightly, the building can still hum. Diversification is a dull word until you need it. Then it is the only word.
What This Means For Investors Watching Pet Names
If you follow pet-linked stocks, the headline is not “pets are over.” The headline is mix. A flat pet segment with rising cat and falling dog is a different business than a booming dog franchise. Valuation stories that assumed endless puppy demand need a rewrite. Valuation stories that treat cats as a footnote need one too.
Watch three things. First, same-store mix by species, if management will give it. Second, private-label and owned-brand traction in cat treats and furniture. Third, services growth as a shock absorber. Companies that only narrate volume without species mix are hiding the plot.
Simple watchlist for pet retail:
  Mix by species
  Repeat rate on cat consumables
  Services as percent of sales
  Dog brand renovation timeline
  Housing and rental commentary
None of that requires a crystal ball. It requires listening when an executive says the quiet part. Dog is soft. Cat is not. Act like you heard it.
The Human Side Of A “Category Rotation”
Numbers can make this sound cold. It is not cold in the home. A cat on a windowsill is still a companion. A dog on a waiting list is still wanted. The rotation is about constraints, not affection. I would rather say that out loud than pretend shoppers became less loving.
There is a tenderness in the way cat parents describe indoor life. They buy towers so the animal can climb. They buy puzzles so the animal can hunt a little. They buy better food because the bowl is the main event. That is care expressed as SKUs. Retailers who mock that instinct will miss the ticket.
Dog parents are not going anywhere. Many will spend more per animal, not less, because fewer households own dogs. Concentration can support premium dog food even if unit volume slips. That is a different math problem. It is still a business.
Risks That Could Flip The Story
Stories like this get over-extended. A few risks sit in plain view. If housing eases and yards become cheaper, dog demand can stabilize. If a cat food scare hits wet pouches, the growth engine sputters. If retailers over-index on novelty treats and forget nutrition, shoppers will punish them. If services labor stays scarce, the diversified model wobbles.
- Housing thaw that favors larger pets again
- Input-cost spikes in meat and cans
- Private-label wars that crush brand price
- Veterinary inflation that suppresses all pet spend
- Overbuilding cat furniture that does not sell twice
I do not think those risks cancel the trend this year. I do think they keep anyone honest who wants to call cats a permanent winner and dogs a permanent loser. Markets hate permanence. Pets are still living animals, not a sector rotation slide.
A Practical Read For Shoppers And Store Teams
If you work the floor, stop treating the cat aisle as the afterthought next to the 40-pound bags. Train staff on wet-food rotation, urinary-care questions, and tower assembly. Those conversations close tickets. If you shop the aisle, notice how much of your cart is ritual rather than bulk. That ritual is why the category held up.
And if you are deciding between pets for a small home, be honest about time and lease rules before you are honest about Instagram. The animal will live with the constraint. The retailer already priced that constraint into the planogram.
We really have to relook at the entire proposition of the product, the packaging, the marketing, the communication. We have work to do.
That is not only a dog-food confession. It is a reminder that ownership trends do not save a sleepy brand. Trends open a door. Product still has to walk through it.
Where The Next Chapters Likely Go
I expect more owned cat brands, more furniture that photographs well, and more functional treats that claim a health job. I expect dog brands to chase “easy urban dog” positioning, smaller packs, and better digestibility stories. I expect services to keep getting mentioned every time dog volume disappoints. That last habit will get old unless the services margin is real.
Will cat ownership keep compounding at last year’s pace? Probably not. A 23% surge is a spike. A 5% follow-through is the more useful number. Spikes fade. Follow-through pays the rent.
The deeper change is cultural enough to last a while. Smaller homes. Cost-aware care. Companions that fit the calendar. If that is the household of the late 2020s, then cat food sales are not a cute footnote. They are the cleanest read on how people actually live.
So yes, the dog aisle can look quieter. That quiet is information. Retailers who treat it as weather will keep posting “in-line” pet segments and wondering why the multiple never expands. Retailers who rebuild the dog proposition and keep feeding the cat boom will look, oddly enough, like they planned this. They did not plan the adoption mix. They can still plan the shelf.
That is the whole job now. Read the kennel. Read the cart. Then stock the life people are already living, not the life the old planogram assumed they wanted.