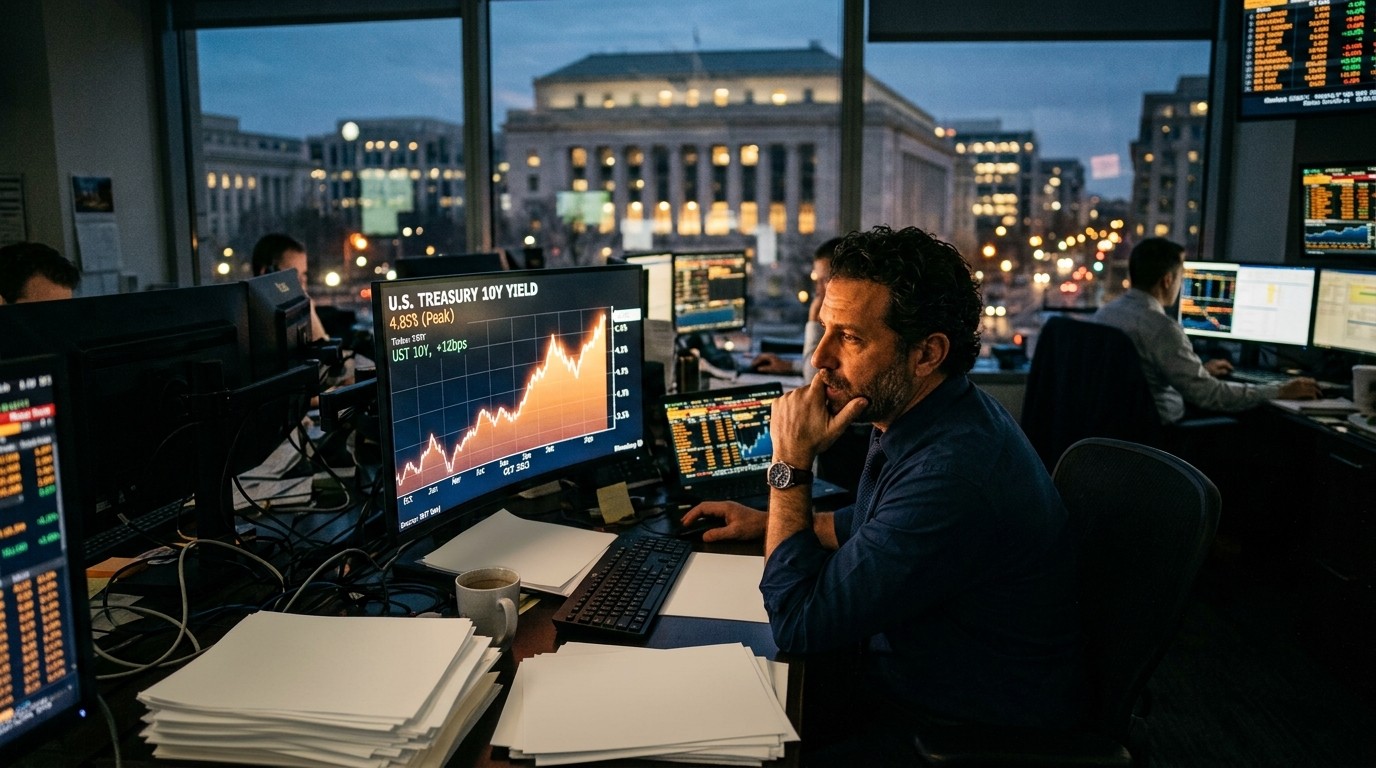

Have you noticed how quickly the mood in rates markets can flip from quiet confidence to something closer to a warning siren? That is the feeling hanging over policy circles right now. Long-term borrowing costs have been climbing again, and the climb is not a polite one. It is the kind of move that forces a new Fed chair to show whether he really means it when he says markets should help steer the ship.
Why Rising Bond Yields Suddenly Matter More
I have covered enough rate cycles to know that a yield spike is never just a number on a screen. It is a verdict. Investors are pricing inflation that refuses to settle near the official target, energy costs that keep poking higher, and a wave of corporate and public borrowing tied to massive technology buildouts. Put those together and you get a bond market that no longer wants to give policymakers the benefit of the doubt.
For a while, the comfortable story was simple. Energy spikes were temporary. Tariffs were a one-off. The artificial intelligence investment boom would eventually add supply and cool prices. That story is fraying. Officials are starting to treat those same forces as more persistent. In my view, that shift in tone is the real story, not any single data print.
Markets have reacted the way markets usually do when they smell a firmer central bank. Traders have lifted the odds of another increase as soon as next month. They are also sketching in a third move later this year or early next, with room for more after that. That is a sharp turn from midyear projections that hinted at one hike and then a long pause.
The Policy Bind Facing The New Chair
Kevin Warsh stepped into the job with a reputation for listening to market prices more closely than many of his predecessors. That sounds refreshing until the market starts shouting two messages at once. One message says inflation risk is still too high. The other says higher long rates can themselves choke growth if officials pile on too fast.
That is the bind. Tighten too little and you look behind the curve. Tighten too much and you risk cutting off an expansion that still has some life in it. I have found that chairs who promise to “let markets speak” often discover that markets speak in riddles. Yields can rise because growth looks stronger. They can also rise because investors doubt the inflation fight. Sorting those two stories apart is the hard part.
The time of looking through the initial supply shock has come to an end. The bias has to be towards restoring price stability.
– Market economist commenting on the policy shift
Some private-sector models now argue that even a 10-year yield near 5.5 percent would slow growth and lift unemployment without dragging core inflation all the way back to 2 percent. If that kind of math is even half right, two or three hikes may not be enough. Five or six starts to enter the conversation, whether officials like that language or not.
What Markets Are Pricing And What They May Be Missing
Not everyone on the Street buys the aggressive path. A few strategists think the yield jump is mostly a real-rate story. In that reading, investors are simply marking in a higher policy rate, not a central bank that has gone soft on inflation. If that is true, the curve is doing part of the tightening work already.
Oil still matters more than people admit. Middle East tension has a habit of leaking into front-month energy prices, and those prices leak into inflation expectations faster than textbooks suggest. I have watched that loop too many times to shrug it off. Still, treating every oil bounce as a reason for an automatic hike can leave policy chasing a noisy series.
- Inflation remains above the 2 percent goal and no longer looks like a brief spike.
- Energy prices have added another layer of pressure at an awkward moment.
- Heavy investment spending and related debt issuance are lifting term premia.
- Officials have pulled back from detailed forward guidance, so markets fill the vacuum.
That last point is easy to underestimate. When a central bank stops sketching the next few meetings in public, traders do the sketching themselves. Sometimes they get it right. Sometimes they overshoot and force officials into a corner. Weak guidance can leave policymakers choosing between a hike they only half want and a skip that looks like a retreat.
Patience Versus A Pre-Set Path
Several officials have tried to cool the temperature without sounding dovish. One senior regional president called another hike by year-end “reasonable” while warning against locking in a mechanical sequence. Another described likely tightening as “modest.” That word is doing a lot of work. Modest is not five or six moves. Modest is also not zero.
Perhaps the most interesting aspect is how quickly Warsh’s public stance appears to have shifted with the bond market. Before taking the chair, he was associated with an easing bias. After the latest meeting, some analysts argued his views now sit closer to the hawkish end of the committee. Markets love a conversion story. They also punish chairs who convert too late.
I do not think this is about personality drama. It is about a framework that treats financial prices as a core input. When the 30-year yield hits levels last seen two decades ago, that framework almost has to produce a firmer committee. The risk is circularity. If the chair follows the market and the market follows the chair, small surprises get amplified.
Growth, Unemployment, And The Inflation Hangover
Here is the uncomfortable arithmetic. Higher long yields can cool demand. They can also leave services inflation sticky if wage growth and housing costs do not roll over cleanly. A slower economy with inflation still a few tenths above target is not a victory lap. It is a slog.
In my experience, committees underestimate how long it takes for rate increases to show up in rents, insurance, and medical services. Goods prices can fall while the boring stuff stays high. That mix invites premature celebration. It also invites markets to keep term premia elevated because they do not trust the last mile.
| Scenario | Likely Growth Effect | Inflation Risk |
| One or two extra hikes | Mild slowdown | Still above target |
| Four to six hikes | Clearer labor cooling | Closer to goal, higher recession odds |
| Pause after latest move | Growth holds up longer | Credibility strain if yields keep rising |
None of those boxes is pretty. That is why the current debate feels sharper than the usual midcycle argument. Officials are not choosing between good and better. They are choosing among versions of imperfect.
The AI Spending Boom Is No Longer A Sideshow
A year ago, the popular line was that huge technology capex would prove disinflationary after a short burst of demand. Build the data centers, add the computing supply, watch costs ease. Nice story. The financing side of that story is messier. Large issuers tapping bond markets at the same time as the Treasury can push term premia higher even if the long-run productivity case is real.
I keep coming back to a simple question. If private investment is running hot and public borrowing is not shrinking, why would long rates behave like they did in a low-investment decade? They should not. Markets are telling policymakers that the investment boom has a price, and part of that price is paid in higher discount rates across the curve.
Some officials now talk about overheating in the investment channel rather than the old consumer-led overheating of past cycles. That is a useful shift. It also complicates the reaction function. You can cool households with mortgage rates. Cooling a global race to build computing capacity is a different animal.
Forward Guidance Lost Its Comfort Blanket
After the financial crisis, the Fed got used to telling markets what came next. That habit reduced volatility. It also trained investors to wait for the script. Warsh’s approach looks closer to the older idea that policy should respond to incoming information and let prices adjust without a detailed map.
Fine in theory. In practice, a committee that just delivered a hike and refuses to sketch the next one can trigger outsized moves in either direction. Deliver another hike without explanation and the curve may reprice as if a long campaign has begun. Skip a meeting that markets treated as live and the curve may ease more than officials want.
Lack of guidance means whatever decision they take risks generating an outsized market response, either substantially further tightening or easing market rates.
That is not an argument for going back to calendar-based promises. It is an argument for clearer principles. Markets can live with uncertainty about the exact meeting. They struggle when they cannot tell which variables actually matter to the chair.
Real Yields Versus Inflation Fear
One camp says the rise in yields is mostly real, not a revolt against a too-soft Fed. If investors believe policy rates will stay higher for longer because the economy can bear it, long yields should rise even if inflation expectations are contained. That reading is less alarming for credibility. It is still painful for housing, leveraged firms, and any budget that rolls a lot of debt.
The other camp says sticky inflation plus heavy issuance plus energy noise equals a term premium that will not fade on its own. In that world, the Fed cannot wait for the bond market to finish the job. It has to validate the warning.
Both can be true in different parts of the curve. Short rates can price the next two meetings. Long rates can price a decade of deficits and investment. Mixing those signals into one “the market is yelling” headline is sloppy. Still, sloppy or not, the political and market pressure lands on the same desk.
Credibility Is The Hidden Constraint
Every chair inherits a stock of credibility. Spend it badly and you pay for years. Warsh has emphasized market signals as an input. That can strengthen credibility if he is seen as facing facts. It can weaken credibility if investors conclude the committee is being led around by the last 20 basis points in the 10-year.
I have always thought credibility is less about sounding tough and more about being predictable in the variables you care about. If inflation stays high, act. If labor demand cracks, stop. If you keep changing the story about energy, tariffs, and technology investment, people stop listening to the story and start watching only the next print.
- Decide whether supply shocks are now persistent enough to demand a systematic response.
- Separate real-rate increases driven by stronger demand from inflation-risk premia.
- Explain how investment-boom borrowing fits into the reaction function.
- Avoid both a locked-in hike path and a vacuum that markets fill with guesswork.
What Households And Investors Should Watch Next
Forget the horse-race chatter about who sits where on the committee. Watch three things. First, the 10-year and 30-year together, not just the funds rate. Second, core services inflation after energy is stripped out. Third, whether private investment plans start to slip when long yields stay high.
Mortgage rates will do more to slow housing than any speech. Corporate refinancing walls will do more to slow hiring in rate-sensitive industries than a single basis-point surprise. That is why this yield move is not a traders-only event. It filters into monthly payments, capex committees, and local tax receipts.
If you hold long-duration assets, you already felt it. If you are waiting to refinance, you are living it. If you run a business that planned around cheaper long money, you are rewriting the plan. Policy debates can sound abstract until the coupon resets.
A More Deliberate Path Still Has A Case
There is a respectable argument for going slower. Back-to-back hikes without a clear interpretive frame can look like panic. A skip that is explained as data dependence can look like discipline. The danger is that markets have already treated the next meeting as live. Disappointing that pricing can ease financial conditions at the exact moment officials want them tighter.
That is the awkward theater of modern policy. You can be right on the economics and still get the market reaction wrong. You can also follow the market and discover later that the market was just trading oil headlines.
My own bias, for what it is worth, leans toward seriousness about inflation without turning every week into a referendum. Price stability is the mandate. Growth is the constraint. Pretending those two never collide is how committees talk themselves into late mistakes.
The Longer Shadow Of High Long Rates
Even if the next hike debate cools, the level of long yields can linger. Pension math changes. Government interest costs rise. Equity valuations that assumed a gentle glide path have to make room for a higher discount rate. None of that requires a crisis. It just requires a different baseline.
I suspect we will look back at this stretch as the moment the post-crisis assumption of cheap long money finally lost its last defenders. That does not make every hawkish call correct. It does mean investors should stop treating 3 percent long yields as the natural resting place of the universe.
Warsh can still choose patience. He can still choose another increase. What he cannot choose is silence about the framework. Markets will keep writing one for him if he leaves the page blank.
Practical Takeaways Without The Drama
If you are trying to translate all of this into a portfolio or a household plan, keep it unglamorous. Duration risk is real again. Cash yields are no longer the only story. Credit spreads can look fine right up until refinancing calendars get crowded. Diversifying across maturities is dull and, right now, useful.
Do not build a life plan around a precise count of hikes. Build it around a range. Two more moves and a pause is one world. A longer campaign is another. Your mortgage, your bond ladder, and your hiring plan should survive both.
Policy watch list:
  Inflation still above target
  Long yields doing tightening work
  Investment boom adding issuance
  Guidance gap amplifying each decision
The bond market is not a referee with a perfect view of the field. It is a crowd that sometimes sees the play early and sometimes overreacts to a sideline scuffle. A chair who says he listens to that crowd still has to decide which shouts count. That decision, more than any single meeting, will define this cycle.
Surging Treasury yields have turned a routine tightening debate into a test of judgment. Move too fast and growth pays. Move too slow and inflation expectations can settle in the wrong neighborhood. There is no neat slogan that solves that. There is only the next data point, the next auction, and a committee that no longer wants to pretend supply shocks are always temporary.
That is why this moment feels different. Not because one chair has a new biography, but because the old excuses for looking through price pressures are wearing thin. Markets noticed first. Policy is now catching up, awkwardly, in public, with less script than anyone in this business has grown used to. The next few meetings will show whether that honesty is a strength or just another source of volatility.