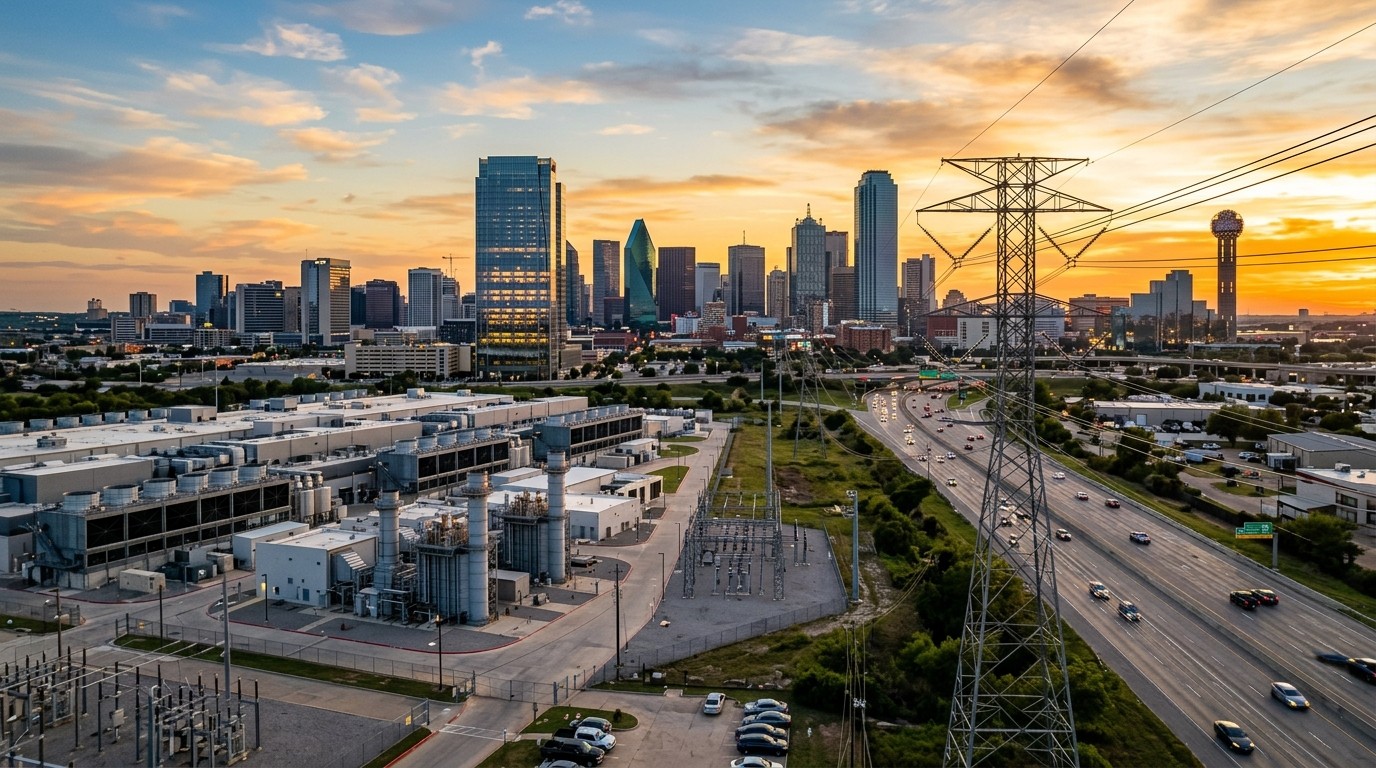

I keep hearing the same question in rooms that used to treat New York as the only serious address for listings and capital. Why would a company even look at Dallas? The short answer is not a slogan. It is a pile of practical details: flights that make both coasts a day trip, courts that are being rewritten for business, a state that now hosts more Fortune 500 headquarters than any other, and a new exchange that already has household names talking about a move. Add one more piece that feels less flashy and more durable. The AI boom is running into physics. Chips can ship. Power plants, substations, water loops, and skilled crews do not appear because a model needs more tokens.
What Yall Street Really Means For Markets
Call it a nickname if you want. Yall Street sticks because it is slightly cheeky and still accurate. Dallas has spent years collecting pledges for large offices and headcount from firms that once treated Texas as a satellite. That is not the whole story. Population growth, industry clustering, and a political-business partnership that actually talks to itself have turned the metro into a place where financial services sit next to energy, logistics, and real estate instead of living in a separate zip code of prestige.
I’ve found that people underestimate how much convenience still matters. You can leave Dallas in the morning, hit a coast, and be back without treating the trip like an expedition. That sounds small until you run a calendar of board meetings, roadshows, and site visits. Location is not romance. It is friction removed from the week.
Why Companies Keep Testing Texas Incorporation
Lower taxes and lighter rules have always been part of the pitch. What changed is the legal product. Texas has been trying to take a slice of the franchise that Delaware long owned by strengthening business courts, writing the business judgment rule into statute, and making incorporation feel cheaper and less theatrical. You can argue about how far that goes. You cannot argue that executives noticed after a string of high-profile fights over how other jurisdictions read fiduciary duty.
In my experience, boards do not relocate a listing because a mayor gave a good speech. They relocate when counsel says the process is clearer, the venue is predictable, and the optics still work with institutions. That is the bar. Anything less is tourism.
It is a combination of factors. Geography helps. Courts and incorporation rules matter more than the slogan on the skyline.
Listings That Already Moved The Conversation
Talk is cheap until a ticker changes venues. Energy midstream names and a major retailer have already said they will shift listings toward the Texas venue after years on a legacy New York board. One of those retailers also reincorporated in Texas the year before. That sequence matters. Domicile first, listing second, is how you know this is not only a press cycle.
Does that mean the old exchanges are finished? Of course not. Liquidity still clusters where it clusters. But competition is no longer theoretical. Once a few large, boring, cash-generating businesses treat a Dallas listing as normal, the next board meeting includes a slide that used to be a joke.
- Midstream energy operators testing a Texas primary listing
- A national retailer pairing reincorporation with an exchange shift
- Global asset managers putting money and prestige behind the venue
- Local managers listing new products on the same board they help capitalize
The First New ETF On A Texas Board
Symbolism is usually overrated. This one is not terrible. A Dallas asset manager with a Houston energy team launched an exchange-traded fund focused on power and infrastructure as the first new ETF on the Texas venue. The same firm already has other products on New York boards and is itself listed there. So this is not a protest listing. It is a product placed where the story lives: Texas capital, Texas energy talent, Texas rails for trading.
The fund is built to sit across the power ecosystem, not a single utility ticker. Traditional generators, grid hardware, and next-generation kit all sit in the same thesis. That is a wider net than “buy the biggest nuclear name and hope.” It is also messier. Infrastructure is contracts, interconnection queues, and multi-year procurement. It is not a product launch keynote.
Why The AI Trade Is Sliding Toward Electrons
For three years the public market story was almost cartoonishly simple. Who ships the fastest accelerator? Who rents the most cloud. Demand looked endless, and in a way it still does. Hyperscalers have pushed planned AI spend into a range that would have sounded fictional in 2021. One chip designer became the face of public-market value because the world decided compute was the scarce input.
Perhaps the most interesting shift is that scarcity is moving. You can design a faster chip. You cannot will a combined-cycle plant, a high-voltage line, or a trained electrical crew into existence on a product cycle. Every extra rack of compute drags turbines, coolers, water systems, transformers, and people behind it. That drag is the investable layer now.
You eventually reach a point where you do not need a faster chip as much as you need power that actually shows up on time.
Managers talking their book will always sound certain. Still, the buildout numbers are large enough to respect. One framing now circulating among energy specialists is a decade-scale program, with hundreds of billions required if data-center load keeps landing the way forecasts suggest. A commonly cited near-term need is on the order of 50 gigawatts of additional power for data centers by 2030. The interconnection queue, meanwhile, is stuffed with a figure in the thousands of gigawatts trying to get a place in line. Queues are not capacity. Queues are a traffic jam with spreadsheets.
What An AI Power Ecosystem Actually Holds
Investors love a clean ticker. The physical system is not clean. It is a stack.
- Fuel and generation, including gas turbines that can be ordered, delayed, and repriced
- Transmission and substations that decide whether a campus is real or a rendering
- Cooling, water, and on-site electrical gear that keep racks from cooking themselves
- Labor and contractors, the part spreadsheets pretend is infinite
Skip any layer and the glossy campus is a warehouse with a PR budget. That is why a basket approach can make more sense than a single-name hero trade, at least for people who do not live inside one equipment maker’s order book.
| Layer | Why It Matters | Time To Build |
| Chips and servers | Sets compute density | Months to a few years |
| On-site power gear | Connects load to the site | One to several years |
| Grid and generation | Makes the campus possible | Many years |
| Skilled labor | Turns plans into steel | Chronic shortage |
Texas As Both Venue And Physical Backdrop
There is a reason this product and this exchange rhyme. Texas already lives inside energy markets, interconnection fights, and industrial siting. Dallas is the financial desk. Houston still holds a huge share of the engineering memory. Putting an energy-infrastructure ETF on a Texas board is not subtle. It is also not fake. The state is trying to be a listing venue while remaining one of the places where turbines and pipelines are not abstract.
I’ve walked enough energy conferences to know the culture clash. Finance wants a narrative that fits on one slide. Operators want a queue position and a transformer that exists. The useful funds sit in the uncomfortable middle. They accept that a 10-year build is not a quarter.
Risks That Do Not Fit The Slogan
A new exchange can still starve for volume. A thematic ETF can still own a bag of names that all sell off together when rates jump or when one hyperscaler pauses a campus. Power markets can overbuild in one region and choke in another. Permitting can slip. Turbine lead times can stretch until the model that justified the plant looks dated.
There is also policy risk dressed as climate debate, reliability debate, or land-use debate depending on the county. None of that is a reason to ignore the theme. It is a reason not to treat “AI power” as a synonym for “up only.”
- Liquidity on a young listing venue can stay thinner than legacy boards for years
- Thematic baskets can concentrate in the same industrial cycle
- Interconnection delays can push cash flows to the right without warning
- Labor tightness can raise costs after the investment case is already public
How I Would Read The Next Chapter
Watch three clocks at once. First, actual listing migrations, not speeches. Second, order books for turbines, transformers, and high-voltage equipment. Third, whether data-center interconnection stays a traffic jam or starts clearing in specific regions. If those three line up, the Texas story and the power story are the same story told in two accents.
If they do not line up, you still have a growing financial center with better air service than its reputation and a legal pitch aimed at Delaware’s old monopoly. That is already a market fact. The ETF is a bet that the unglamorous half of AI — electrons, water, steel, crews — will set returns after the chip poster is tired.
I do not need the nickname to work as poetry. I need the filings, the listings, and the interconnection reports to keep rhyming. So far they do, in a messy, multi-year way that looks a lot more like infrastructure than like a keynote. That is the part worth sitting with.
A Longer Look At Capital, Courts, And Power Demand
Let me slow down, because the short version is easy to skim and easy to misread. Dallas is not replacing New York next Tuesday. Liquidity, research coverage, and habit still favor the old boards. What is changing is optionality. Boards now have a second script. Incorporate here, list here, keep a dual presence if you must, and tell shareholders you did it for process rather than politics. That script did not exist in a credible form a few years ago.
The court reform piece is dry and that is the point. Business judgment, specialized dockets, and a promise of less theater are not campaign lines for most voters. They are catnip for general counsel. When a few famous fights made Delaware feel unpredictable to some executives, Texas offered a product. Whether that product is truly better will be tested in actual cases, not in ribbon cuttings. Fair enough. Markets price process risk all the time.
Meanwhile the energy stack under AI is becoming a planning problem for utilities that spent a decade assuming flat-ish load. Data centers do not behave like residential subdivisions. They want large blocks, high uptime, and they want them in places that also have fiber, land, and friendly local rules. That collision is why “who builds the chip” stopped being the only question that paid.
Think about a campus that needs hundreds of megawatts. The chip vendor can allocate silicon. The cloud vendor can allocate capex. The grid may still say not yet. That “not yet” is where investors who like multi-year compounding should be looking, with eyes open about regulation and execution.
Is every name in a power-and-infrastructure basket a winner? No. Some will miss on contracts. Some will over-earn on a temporary shortage and then face a wall of new supply. That is investing, not a parable. The useful change is the map. Compute pulled energy out of the background and put it on the same slide as semiconductors. Texas, for once, sits on both sides of that slide: the listing experiment and the physical system.
If you only remember one tension, remember this. Software iterates in weeks. High-voltage reality iterates in years. Portfolios that pretend those clocks are the same will keep getting surprised. Portfolios that respect the slower clock might look boring in a melt-up and sturdy when the next constraint shows up on an earnings call as “delayed interconnection.”
That is the unglamorous conclusion. Yall Street is a nickname. The grid is not. The listings are a test. The ETF is a wager that the test and the grid belong in the same sentence. I think they do. I also think anyone who treats either as a finished victory should sit with a queue report until the romance fades. Then the work starts.