
Have you ever watched a market climb on fear, then drop on a rumor that talks might actually happen? That is the strange rhythm around the Strait of Hormuz right now. One week energy desks treat every headline like a siren. The next week a few words from mediators send crude sliding, even while the waterway itself remains tightly constrained. I have covered enough geopolitical shocks to know this pattern rarely stays neat for long.
Why Hormuz Still Dominates Energy Markets
Before the current conflict, roughly a fifth of the world’s seaborne oil moved through that narrow passage. That single fact still sits under almost every price chart. Close the lane, or even threaten to keep it closed, and refiners from Asia to Europe start rewriting supply plans. Open it even partially, and traders immediately try to price the relief. The market is not waiting for a perfect peace. It is waiting for a credible path back to transit.
Iran’s foreign minister has kept the door to indirect talks with Washington slightly ajar. That matters more than the theatrical language surrounding it. Mediators have already carried Tehran’s conditions to the American side. According to recent official remarks, those conditions were explained in detail. What has not arrived, at least not in a form Tehran will acknowledge as formal, is a complete reply.
Only a negotiated solution can break this deadlock.
That sentence is doing a lot of work. It signals that Iran still prefers a deal to an endless standoff. It also leaves room to claim that Washington, not Tehran, is the party delaying the next step. In my experience, that kind of wording is designed for two audiences at once: domestic hardliners and foreign energy buyers who just want tankers moving again.
The Conditions Tehran Refuses To Drop
Iran is not being vague. Progress on reopening the strait, officials say, depends on specific demands. They include a halt to what Tehran calls acts of aggression, an end to the naval blockade and broader economic pressure, and the release of frozen Iranian assets. None of that is small print. Each item touches military posture, sanctions architecture, and cash.
Washington has already rejected the latest conditional package. That rejection landed in public, which usually hardens positions for a few news cycles. Still, the Iranian side insists intermediaries have not brought back a structured answer. That gap between a public no and a private channel is where markets like to invent stories. Sometimes those stories are right. Sometimes they are just hope wearing a suit.
- Reopening the strait is tied to an end of what Iran labels aggression
- Tehran also wants the naval blockade and economic pressure lifted
- Asset release remains part of the same package, not a side request
- Indirect channels are still active even after a public rejection
I find the sequencing interesting. Iran offered a tight timetable in recent days: reopen the waterway and resume nuclear talks within seven days if its terms are accepted. That is a high-tempo proposal. It tries to force a binary choice. Accept the framework and energy flows resume quickly. Reject it and the choke point stays shut while political calendars keep ticking.
Military Signaling Has Not Slowed Down
Diplomacy is only half the picture. Iranian commanders keep saying the war is not finished. The message is blunt. Victory, in their telling, must be consolidated. The other side, they argue, should expect more blows if fighting resumes in force. That kind of language is not accidental. It is meant to show that talks do not equal surrender.
On the water, the tone is even sharper. Iran’s Revolutionary Guard navy claimed it captured an American Remus 600 unmanned underwater vehicle in the strait and handed it to specialists for data recovery. It also repeated that unauthorized traffic through the passage remains blocked. U.S. military authorities did not immediately comment. In situations like this, silence can last hours or days. Markets do not wait that long.
Perhaps the most interesting aspect is how these two tracks run together. One official talks about mediators and negotiated exits. Another talks about captured hardware and a closed sea lane. Both can be true at the same time. States often bargain while they posture. Traders hate that combination because it makes probability charts feel useless.
What Oil Prices Already Told Us This Week
Crude still sits far above where it started the year. West Texas Intermediate has gained close to 61 percent year to date. Brent is up more than 71 percent over the same stretch. Those are not normal investment-cycle moves. They are war-premium moves with an inflation echo attached.
And yet the latest week was not a straight squeeze higher. West Texas Intermediate fell 2.3 percent to close near $92.41 a barrel. Brent slipped 2.1 percent to about $104.32. U.S. crude finished the week almost 8 percent lower. Brent was roughly flat on the week. That split tells you something. American barrels reacted faster to talk of talks. The international benchmark stayed cautious.
| Benchmark | Latest close | Weekly move | Year-to-date |
| West Texas Intermediate | $92.41 | -2.3% on the day, about -7.9% on the week | Nearly +61% |
| Brent | $104.32 | -2.1% on the day, roughly flat on the week | More than +71% |
Why the sudden softness? Sideline conversations around a major diplomatic gathering created a relief bid. Not a peace bid. A relief bid. That distinction matters. Relief fades if the strait stays closed. Peace, or even a durable ceasefire-plus-transit deal, would rewrite the whole forward curve.
I’ve found that energy markets often overreact to the first hint of negotiation and then underreact to the operational details. Ships, insurance, escorts, and inspection regimes decide whether barrels actually move. A speech does not load a tanker. A protocol does.
The Political Calendar Is Now A Price Factor
One sensitive report, based on unnamed officials, said the U.S. president told aides he sees renewed bombing after November’s midterm elections as likely. Treat that as political risk, not as a scheduled event. Still, markets hear calendars. If traders believe military pressure could intensify after a domestic vote, they will keep a risk premium in the curve even while headlines talk about mediation.
That is an ugly setup for anyone who wants clean forecasts. You can model tanker delays. You can model spare capacity in other producers. You cannot easily model a leader’s post-election appetite for escalation. So desks do what they always do. They widen the range and charge more for optionality.
- Watch whether mediators deliver a written reply, not just verbal color.
- Track any verified change in transit through the strait itself.
- Separate campaign-season comments from operational orders.
- Follow insurance and freight costs as early-warning gauges.
- Assume oil can fall on talk and spike on a single maritime incident.
Daily Life At The Water’s Edge
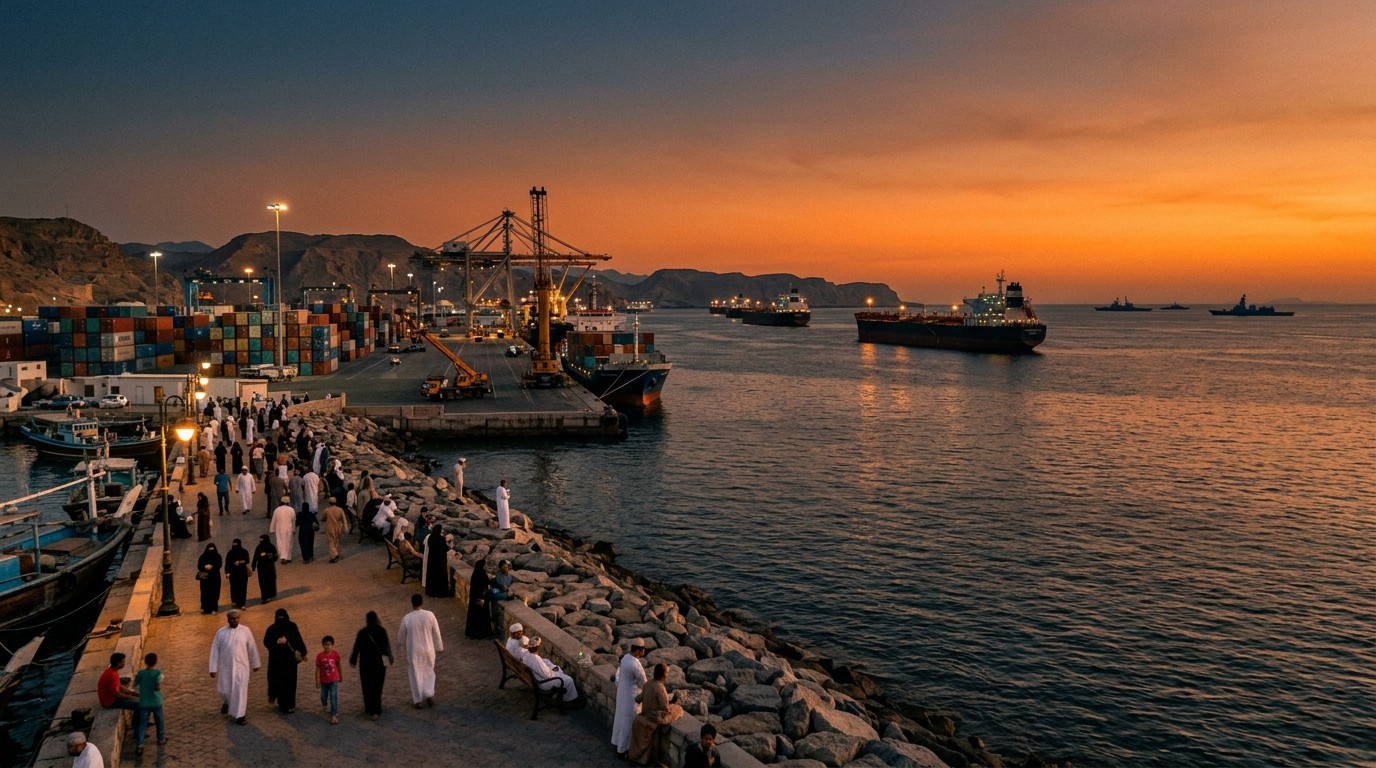
In Bandar Abbas, ordinary evenings still happen. People walk the waterfront at sunset. The port city remains a strategic hinge, but it is also a place where families take the air. That contrast is easy to miss if you only stare at futures boards. Wars compress into tickers. On the ground they stretch across neighborhoods, wages, fuel queues, and rumor.
I keep coming back to that image because it explains the politics. Officials who live beside the waterway talk about dignity and conditions. Officials far from it talk about barrels and inflation. Both groups are describing the same choke point. They are not describing the same stakes.
How A Closed Strait Feeds Global Inflation Fear
Restricted Middle East shipments do more than lift crude. They lift diesel, jet fuel, petrochemical feedstocks, and shipping rates. Those costs seep into food distribution, manufacturing, and household budgets. Central bankers can look through a one-week spike. They cannot look through a multi-month disruption in a corridor that used to carry a huge share of global supply.
That is why a 8 percent weekly drop in U.S. crude does not end the inflation conversation. The base is still much higher than it was in January. A pullback from an elevated plateau is not the same as normalization. If talks stall and military claims multiply, the next move can just as easily be another squeeze.
Our conditions are clear; any progress toward the opening of the Strait of Hormuz is contingent upon the fulfillment of these conditions, and we will not back down from them.
Read that again with a trader’s ear. “Will not back down” is a floor under disruption risk. It tells you Iran wants the market to believe delay is a policy, not a glitch. Whether that stance survives contact with economic pain inside Iran is a different question. Sanctions, asset freezes, and wartime damage cut both ways.
Indirect Talks Are Not The Same As A Deal
Indirect talks can persist for months without producing a signature. Mediators shuttle language. Each side tests whether the other is softening. Leaks appear. Oil dips. Then a drone claim or a rejected proposal snaps prices back. If you are looking for a clean narrative, you will be disappointed. The process is messy because the incentives are messy.
Washington wants leverage and a political win that does not look like a concession under fire. Tehran wants sanctions relief, asset access, and an end to military pressure without appearing to fold. Those goals can overlap in a narrow corridor. They can also miss each other by a mile. I suspect we are still in the mapping phase, not the closing phase.
Market checklist in one glance:
  Diplomacy: indirect, unfinished, conditions still attached
  Military: claims of captured hardware, closed-lane rhetoric
  Oil: lower on the week, still sharply higher on the year
  Risk: political calendar plus maritime incidents
What A Real Reopening Would Need
Even if both capitals accepted a framework tomorrow, ships would not flood the strait the same afternoon. Insurers would want clarity on mines, drones, and rules of engagement. Charterers would want escort assurances. Refiners would want multi-week visibility, not a 48-hour window. Markets price hope quickly. Logistics move slowly.
That lag is where a lot of people get hurt. They buy the rumor of reopening, then discover that “open” means limited daylight transit under heavy inspection. Or they sell the rumor of collapse, then watch a partial corridor reopen just enough to dump the front month. The boring operational annex is usually the document that actually moves barrels.
- Verification of safe passage beats any podium remark
- Insurance premia often turn before official statements do
- A partial lane is not the same as pre-war throughput
- Nuclear-talk language can travel faster than tanker schedules
The Underwater Drone Claim Changes The Texture
A captured unmanned underwater vehicle, if confirmed, is more than a trophy photo. It is a statement about domain awareness. It says the force that claims the capture can find, seize, and exploit hardware in contested water. It also invites denial, technical debate, and counter-claims. Until there is independent confirmation, treat it as a market-moving allegation rather than a settled fact.
Still, allegations of this type rarely land in a vacuum. They arrive when a government wants to show control of the lane. They arrive when talks need a harder backdrop. They arrive when domestic audiences need proof that the navy is not idle. All three motives can coexist. That does not make the claim true. It does make it useful.
Why Energy Desks Are Split Between Relief And Dread
Some traders look at the weekly drop and say the peak premium is in. Others look at the year-to-date surge and say one down week is noise. Both can quote data. The honest position is less glamorous. The distribution of outcomes is still wide. A mediated reopening could send crude materially lower. A post-election escalation scare could send it materially higher. Standing in the middle of that range feels uncomfortable. It is also realistic.
In my view, the tell will not be another colorful quote. It will be freight. When owners start offering more voyages through or around the region at lower war-risk rates, the market will believe transit is returning. Until then, speeches are just speeches.
Investors Outside Oil Are Not Spectators
Equities feel this through inflation expectations, rate-cut odds, airline costs, and chemical margins. Emerging-market importers feel it through currency pressure. Exporters outside the conflict zone can gain share if they can load quickly. That last group is easy to forget. A closed Hormuz is a tax on many consumers and a windfall for some producers who can still deliver.
If you hold a broad portfolio, the question is not only “where is WTI tonight?” It is whether a prolonged disruption forces policymakers back into a more hawkish stance. High oil with sticky services inflation is a nasty mix. Soft oil with a still-closed strait is an unstable mix. Neither is a free lunch.
Reading The Next Forty-Eight Hours Without Getting Fooled
Short windows are dangerous because every leak looks decisive. A mediator dinner becomes a breakthrough. A rejected proposal becomes the end of diplomacy. Rarely is either true by morning. Ask a simpler set of questions. Did any tanker complete a verified transit that was impossible last week? Did any government publish a written framework instead of a spoken condition? Did insurance quotes actually move?
If the answer to those is no, you are still in the same regime: constrained flows, active signaling, and a market that will whip around every sideline conversation. That regime can last. It can also snap. The snap is what people remember. The grind is what pays the bills or wrecks them.
A Practical Way To Follow The Story From Here
Keep the file simple. One page for diplomacy, one for military claims, one for prices and freight. Update them separately. Do not let a hardline speech automatically rewrite your oil balance. Do not let a soft close automatically rewrite your war-risk assumption. The people closest to this crisis are running two ledgers at once. You should too.
And yes, I know that sounds unsatisfying. Readers want a single headline that settles the week. This week does not settle. Iran is keeping indirect talks open. It is also keeping conditions intact and advertising control of the waterway. Washington has rejected the latest package and, according to sensitive reporting, is thinking about later military options. Oil fell on the rumor of conversation and remains expensive on the fact of disruption.
That is the whole shape of it. Not elegant. Not finished. Still capable of moving inflation, elections, and household budgets in the same month. If a formal reply finally travels back through the mediators, the tone can change fast. If another maritime incident lands first, the tone can change faster. Either way, the strait is still the hinge. Everything else is commentary until the ships move again.