
Have you ever opened a card statement, squinted at a $12.99 line you barely recognized, and told yourself you would deal with it later? Most of us have. Later rarely arrives. That small delay is not a personality quirk. It is one of the most profitable habits in modern consumer life, and a new class of personal AI agents is starting to pick it apart.
When An Assistant Starts Reading The Fine Print For You
I have watched friends treat recurring charges like background noise. A streaming plan from a series they finished last winter. A trial that quietly became a membership. A fitness app they opened twice. None of those items feels urgent on its own. Together they add up to real money. That is the weak spot a household AI agent can attack without drama and without a lecture.
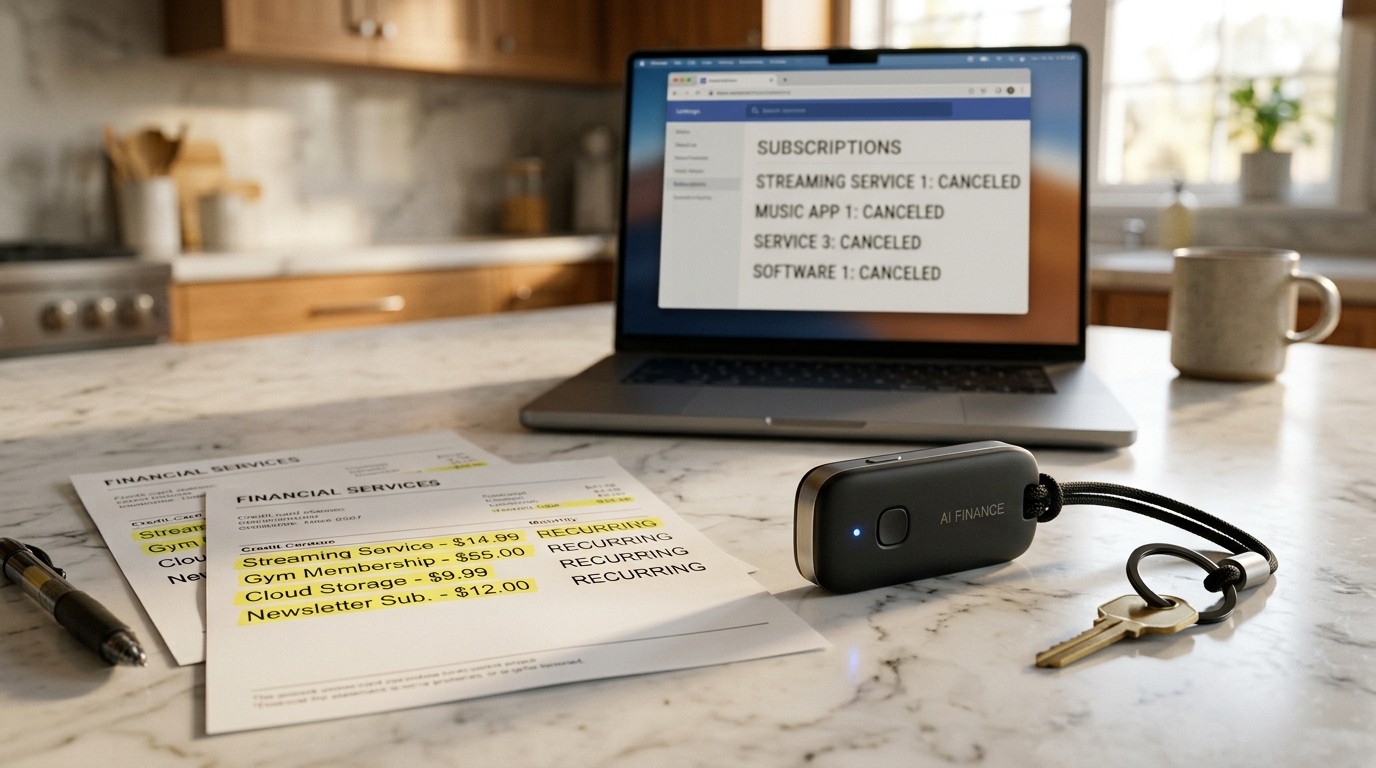
The newest consumer agents are not limited to calendar reminders or draft emails. Once someone grants access to banking and card data, the assistant can scan for patterns that humans miss after a long week. It flags names that look unfamiliar. It groups charges that repeat every thirty days. It asks a blunt question: do you still want this?
That question used to require effort. Login pages. Chat windows. Hold music. A cancellation path designed to make you give up. When the friction drops, behavior changes. People who were “about to cancel” suddenly do cancel. I find that shift more interesting than the gadget itself, because it rewrites the quiet math behind a huge slice of household spending.
The Comfortable Economics Of Forgetting
Signing up is easy. Ending a plan is work. Companies have known this for years. A modest monthly fee can hide in a statement for months, sometimes years, while the product sits unused. The charge is small enough to ignore and large enough, across millions of customers, to matter.
Recent consumer research points to a simple picture. Close to half of households increased what they spend on subscriptions in the last full year. Average annual outlay has climbed toward the high one-thousands, which works out to roughly one hundred fifty dollars a month for many families. Card data has also shown subscription spend growing faster than overall card spend in some months, with entertainment and retail plans taking a large share.
The median user of subscription-tracking tools now juggles more than a dozen recurring payments. One in four carries twenty or more. That is not a hobby. That is a second budget running in the background.
When people are forced to decide, they are about four times more likely to cancel.
– Academic research on selling subscriptions
That finding is the heart of the story. Inertia and cancellation friction let sellers keep revenue that would vanish if every customer had to make a fresh choice each month. Estimates from that same line of research suggest sellers can roughly double revenue because people forget, delay, or get tired of the process. An agent that surfaces the choice and then executes the paperwork weakens both supports at once.
Not Every Recurring Charge Is Equally Fragile
A bag of pet food landing on the porch is hard to ignore. A digital monitoring service that never sends a useful alert is easy to forget. Physical goods create a reminder. Software often does not. That is why credit tools, old cloud lockers, forgotten premium tiers, and idle wellness apps sit in the danger zone.
Price increases sharpen the effect. Trackers that sit inside banking apps say cancellations at a single merchant can jump by as much as half when the bill goes up. Health and fitness plans have seen the steepest rise in exit activity, followed by video, news, and music. People will tolerate a lot until the number on the statement changes. Then the spell breaks.
- Digital services with no physical reminder are the first to go
- Plans the household stopped using months ago are easy targets
- Price hikes turn passive payers into active cancelers
- Bundles that feel vague lose out to tools with a clear weekly use
I have found that the emotional tone matters too. Nobody feels clever paying for a gym they do not visit. They feel mildly foolish. An assistant that names the charge and offers a one-tap exit gives people a clean way to correct the story they tell themselves about their money.
Why Banks Should Pay Attention Too
Subscription cleanup is only the opening move. Once an agent can read cash flow, it can ask a second question that is even more awkward for traditional lenders. Why is idle money sitting in a checking account that pays almost nothing?
National average yields on ordinary checking balances remain tiny. High-yield savings and cash vehicles often sit in a range that looks closer to three to five percent, depending on the cycle. If household agents begin sweeping leftover cash automatically, cheap deposit bases start to look less automatic. Cheap deposits fund loans. If those deposits migrate, funding costs rise. That is not a niche fintech footnote. It is a system-level issue.
Perhaps the most interesting aspect is how ordinary this could feel in two years. No manifesto. No protest. Just a default rule: keep a buffer, move the rest, cancel what you do not use. The household does not need a spreadsheet personality. It needs an assistant that does not get bored.
Consumers Were Already Getting Less Patient
AI did not invent subscription fatigue. It arrived in the middle of it. Members of banking-connected management tools are already far more likely to start a cancellation than they were a year earlier. That shift began before the flashiest agent features landed. Life itself is turning into a stack of recurring bills, and those bills creep upward.
Companies that help people see those bills now track hundreds of thousands of unique recurring payees. Older automation could handle only a few hundred major names with a clean cancel path. Agentic tools widen that net. The average canceled plan in some datasets lands around the high teens per month. Over a year, users who clean house often reclaim a few hundred dollars they did not realize they were still funding.
That number will not change a billionaire’s weekend. It will change a family’s grocery flexibility. It will also change how product teams think about dormant accounts. More than half of surveyed subscription businesses have admitted that at least a tenth of their base is inactive but still paying. Monthly churn around one fifth is already common. If agents make inactivity visible, the inactive slice shrinks.
Retention Has To Grow Up
The old defense was friction. Hide the button. Add a survey. Offer a discount only after the customer is angry. That playbook looks shabby once an assistant can complete the exit for you. The better defense is value that is hard to argue with.
Product leads who work on retention keep making the same point. Treat cancellation as a transition, not a cliff. A viewer who finished a series may want a pause, not a lecture. A fitness user who hit a goal may want a cheaper maintenance tier. A pause-before-cancel option has exploded in usage in recent industry reports, and a large majority of people who pause eventually come back.
The best defense against AI-assisted cancellation is not friction.
Survey work on signup psychology points the same way. Most consumers say they are more willing to subscribe when leaving is easy. Most say they are more willing to come back. About a third say they would stay if they could pause instead of walk away. Ease does not kill the category. Ease changes who deserves to keep the revenue.
In my experience, people do not hate subscriptions. They hate feeling trapped. Once they trust that they can see every recurring charge and shut one off without a scavenger hunt, they often spend more, not less, on the services they actually like. That is a healthier market, even if it is a tougher quarter for firms that lived on forgetfulness.
What A Practical Cleanup Looks Like At Home
You do not need a keychain gadget to start. You do need a method that does not rely on memory. I like a simple pass that takes one evening and then a lighter monthly check.
- Export or review ninety days of card and bank activity and mark every repeating name.
- Sort the list into used weekly, used sometimes, and not used at all.
- Cancel the unused group first, before you negotiate anything.
- Pause or downgrade the “sometimes” group instead of keeping the premium default.
- Set a calendar note for the next billing cycle so a price hike cannot hide.
- Move leftover checking cash above your buffer into a higher-yield account.
If an agent can run that loop for you, fine. If it cannot, the loop still works. The point is to replace vague guilt with a list. Vague guilt does not cancel anything. A list does.
| Charge type | Why it survives | Best first move |
| Unused digital plan | No physical reminder | Cancel immediately |
| Seasonal entertainment | Fear of missing a premiere | Pause between seasons |
| Wellness app | Aspirational identity | Downgrade to maintenance |
| Household delivery | Visible product at the door | Adjust frequency |
| Idle cash in checking | Habit and inertia | Sweep above a set buffer |
Privacy, Platform Pushback, And The Trust Problem
Giving an assistant the keys to your financial life is not a casual decision. Some retailers have already blocked agent shopping on the grounds that the access violates their rules. That fight will spread. Agents that can buy, cancel, and move money sit at the edge of every platform’s terms.
Comfort is mixed. A sizable share of consumers say they are fine with AI managing subscriptions. Another share wants no part of it. Both reactions are rational. Statement data is intimate. It shows doctors, late-night orders, gifts, and debts. A sloppy permission model is not a cute onboarding bug. It is a breach waiting for a headline.
I would rather see narrow, revocable access than a sweeping “manage my life” toggle. Read-only first. Confirm every cancellation. Keep a log. Those are boring requirements. Boring is how you keep this category from becoming a scandal.
Hardware Ambition Versus The Job People Actually Want
The company behind the most discussed consumer agent is wrapping the software in unproven hardware, from glasses to a small charm-like device. Markets have rewarded the larger AI story. Everyday users may care less about the object on the table and more about whether the assistant finds the $17 charge they forgot in March.
That is a useful reminder for anyone building in this space. The profitable weak spot is not science fiction. It is a messy statement and a human who is tired. Solve that with fewer steps than a customer-service maze and you will get usage. Dress it in a futuristic accessory and you still have to earn the permission.
What Happens If Inertia Stops Paying
If forgotten plans disappear, companies must compete on quality and price instead of a locked-in base. That sounds obvious. It is not how a lot of recurring revenue has actually worked. When customers cannot leave without a fight, product teams feel less pressure. When leaving is easy, the product has to be good on Tuesday, not just on signup day.
When people stop paying for something they no longer want and spend that money elsewhere, markets work the way they are supposed to work.
Money that leaves a zombie subscription does not vanish. It moves to groceries, debt payments, a better tool, or cash that finally earns a real yield. Consumers benefit. Firms that earn loyalty the hard way benefit. Firms that rented attention they no longer deserved do not. I am comfortable with that trade.
Will every household hand this job to software? No. Some people enjoy the control of doing it themselves. Some will never connect an account. That is fine. The pressure still rises, because the people who do connect an account become the new baseline for what “normal” cancellation feels like. Support scripts and dark patterns age badly in that world.
A Cleaner Recurring Economy Is Still A Recurring Economy
This is not a eulogy for subscriptions. Recurring billing is a good fit for things people use on purpose. Music you play daily. Software that sits in your workflow. Pet food that should arrive before the bag is empty. The problem was never the model. The problem was the silent tax on inattention.
If agents make the ledger visible, the model can get healthier. People try more services because exit is safe. Companies invest in pauses, tiers, and proof of value instead of maze design. Banks that want deposits may have to pay for them. None of that is gentle. All of it is clearer.
Start with one statement. Circle the names you cannot defend out loud. Cancel those first. Then decide whether you want a piece of software to keep watch so the same names cannot sneak back. That choice, more than any keynote demo, will decide how much of the old inertia premium survives.
And if you still have a charge you cannot explain? Do not wait for a future assistant to grow a conscience. End it this week. The most profitable weak spot in the household budget is still the one you keep meaning to fix tomorrow.