
Have you ever opened a trading week and felt the market already decided the mood before the opening bell? That is the feeling this Monday. Bond yields climbed hard, crude jumped after a rejected peace proposal, and futures leaned lower across the board. I have been watching this mix for years, and it still surprises me how quickly a single yield print can change the way people talk about growth stocks, consumer names, and even cruise lines.
The Market Backdrop That Sets Up The Whole Week
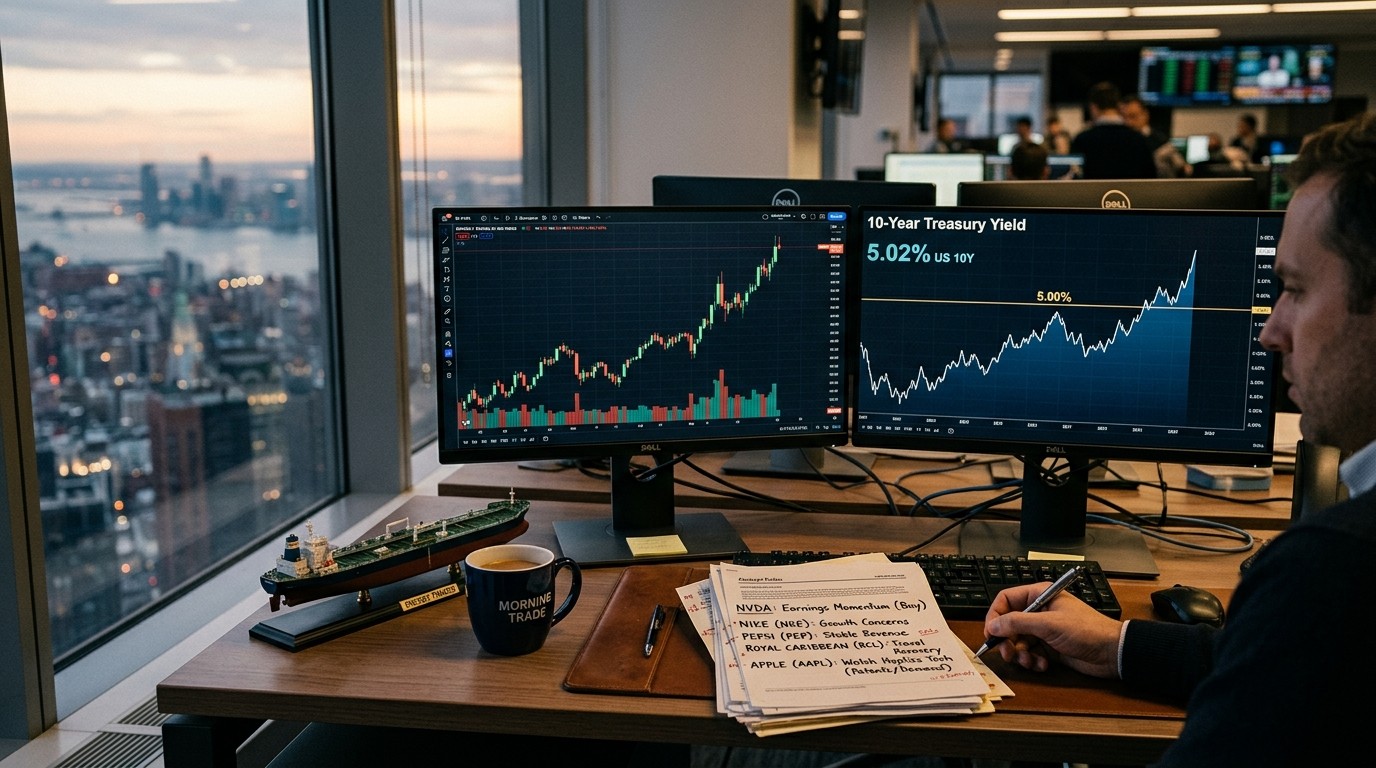
The 10-year Treasury yield traded as high as 5.234% in morning action. That is not a footnote. It is a level last seen in a much later chapter of the cycle, and it immediately raises two old questions. Is inflation still sticky enough to keep policy tight? And can stocks catch a bid when the risk-free rate is this loud?
Stock futures were down across the board as that yield move landed. Nothing dramatic in isolation. Still, the tone matters. When the long bond sells off this fast, valuations get a second look. Multiple expansion becomes harder. Cash starts to look less boring. I have found that Mondays like this are less about one headline and more about whether investors believe the Fed still has room to stay tough.
A rising 10-year yield is not just a number. It is a tax on every discounted cash flow model sitting on a desk this morning.
Why Bond Yields Became The First Story
Yields do not jump in a vacuum. They jump when traders price more inflation risk, more supply, or a central bank that cannot ease as soon as hoped. This morning’s print invoked both inflation worries and the idea of a tough Federal Reserve. That combination is a rough backdrop for equities trying to find a bid.
Perhaps the most interesting aspect is how quickly the conversation shifts from “soft landing” chatter to “how high can the 10-year go.” Short sentences travel faster on a trading floor. Longer ones show up later in research notes. Both are circling the same fear: tighter financial conditions just as a heavy data week begins.
In my experience, the market can live with high yields if earnings keep growing. It struggles when high yields arrive with geopolitics in oil and a calendar packed with inflation and jobs numbers. That is the cocktail on the table today.
Oil Is Feeding The Bond Problem
Oil is not a side story this morning. It is part of the bond problem. Both Brent and WTI were up more than 3% after the president said he rejected a peace proposal from Iran. That sentence alone is enough to reprice risk in energy and rates at the same time.
Both pathways for Mideast oil exports now look at least partly constrained, with no clean sign of a quick change. Stasis in that region often means higher crude. Higher crude often means stickier inflation expectations. Stickier inflation expectations often mean higher yields. You can see the chain. It is not subtle.
I do not pretend to forecast diplomacy. I do watch what crude does to the 10-year. When energy jumps like this, rate-sensitive groups tend to wobble first. Housing-related names, long-duration growth, and anything that needs cheap money all feel the air change. Cruise operators feel it twice, because fuel is a real cost and discretionary travel is a real choice.
- Higher crude can keep inflation expectations from cooling
- Higher inflation expectations can keep policy language hawkish
- Hawkish language can keep the 10-year bidless
- A bidless 10-year makes equity multiples harder to defend
That loop is why oil belongs in the first third of any Monday note, not buried under ticker gossip.
A Heavy Week Of Data And One Chip Report
The calendar is not gentle. The Fed’s preferred inflation gauge arrives Wednesday. The September jobs report lands Friday morning. Between those two prints sits a chip report from a well-known memory name on Wednesday night. That is a lot of information for a market already nervous about yields.
Inflation data still sets the tone for rate expectations. Jobs data still sets the tone for growth and consumer strength. Put them in the same week and you get a market that does not want to get too far ahead of itself on Monday. Futures already hinted at that caution.
There is also a broader debate running under the tape. Some voices keep saying everyday investors should just own index funds and stop picking names. I have pushed back on that idea more than once. There is still room for individual stock work if you pick carefully, size positions with humility, and accept that not every name will cooperate on a high-yield Monday.
Index funds are a fine core. They are not a reason to stop thinking.
The magic, if you want to call it that, is not in trading every headline. It is in finding a handful of businesses that can still compound when the 10-year is loud. That is harder work. It is also the work that makes a week like this useful instead of merely noisy.
A Record Buyback Increase In Chips
One of the largest chip companies added $150 billion to its buyback authorization, bringing the total program to $235 billion. That is being described as the biggest buyback increase on record. Size like that is not a rounding error. It is a statement about cash generation and about management’s view of the share price after a stretch of lackluster performance.
I have been among those arguing the company needed to get more aggressive on its own stock. Authorization is step one. Deployment is step two. The open question this morning is simple: how active will they actually be? A giant number on a slide does not automatically support the shares if the company is slow to use it.
There was also a product note. The same firm released a new software platform meant to protect AI agents from misbehaving. That line sounds abstract until you remember how fast companies are wiring agents into workflows. Safety tooling is not a side hobby anymore. It is becoming part of the infrastructure conversation, which is why a pair of cybersecurity names showed up later in the same morning tape.
Buyback math in plain language:
  Authorization is permission.
  Execution is the bid.
  Timing decides whether the market cares this week or next year.
A Consumer Giant Loses Street Confidence
A major beverage and snack company was cut to hold from buy at a large European bank. The price target dropped to $138 from $155, which implies only about 7% upside from the analyst’s new math. That is not a collapse. It is a shrug. Analysts appear less confident in the North America turnaround.
The stock already trades at a below-market multiple. The question is whether a cheap multiple is enough if the strategy is flawed and the recovery takes longer than hoped. Shares are down about 10% year to date. That kind of grind wears people out. It also creates the classic value trap debate: is the market too gloomy, or is the turnaround simply late?
I tend to give consumer turnarounds more time than growth stories, because brand repair is slow. I also get impatient when volume and mix keep disappointing in the home market. Cheap is not a strategy. Cheap plus a credible plan is a strategy. Right now the Street sounds unsure about the plan.
Cruise Names Get A Pair Of Upgrades After A Hard Slide
Two banks moved a large cruise operator to buy from hold. One of them framed the recent drop as a decent entry in a high-quality name after a 26% pullback since early August. That is a serious drawdown in a short window. The whole cruise group has been hit during the same stretch, weighed down by high oil prices.
Fuel is the obvious link. When crude jumps more than 3% before breakfast, investors remember that ships burn a lot of it. They also remember that a squeezed consumer can delay a vacation faster than they delay a phone bill. Still, upgrades after a washout are how cycles often turn. Not always. Often enough to pay attention.
My preferred way to play the space has been a more differentiated operator rather than the biggest mass-market brand. Different itinerary mix. Different customer. Different pricing power. That is an opinion, not a guarantee. In a high-oil tape, differentiation is not a slogan. It is the difference between a name that can pass through costs and a name that cannot.
| Theme | Why It Matters Monday | Market Mood |
| 10-year yield near 5.23% | Pressures valuations and rate-sensitive groups | Cautious |
| Crude up more than 3% | Feeds inflation worry and cruise fuel costs | Tense |
| Inflation gauge Wednesday | Sets near-term Fed expectations | Watchful |
| Jobs report Friday | Tests the consumer and the landing narrative | Watchful |
| Giant chip buyback | Potential support if actually deployed | Selective |
A Bank Name Gets A Higher Target And A Cautious Note
One research shop raised its target on a large consumer lender to $260 from $254 while saying it is cautious into earnings. That pairing looks odd at first glance. A higher target usually sounds constructive. Caution into earnings usually sounds like a warning. Both can be true at once. The rating stayed at buy.
It is a tough stock to own in a prolonged tightening cycle because the business is heavily tied to the consumer. Credit cards and related lending do well when households are sturdy. They get messy when rates stay high and delinquencies creep. Painting every financial with the same brush is lazy, though. Some banks are more deposit-rich. Some are more capital-markets driven. Some live and die by revolving credit.
We own other financials rather than treating the sector as one trade. That is not a moral statement. It is a reminder that balance sheets differ. In a week with a jobs report on Friday, consumer credit names will be marked to that print whether they like it or not.
A Large Verdict Against A Device Giant
A federal jury in San Diego delivered an onerous $5.7 billion verdict against a major device maker, saying it infringed patents tied to haptics in a popular watch. The company said it does not use that technology and plans to appeal. Haptics, for anyone who does not live in hardware notes, are those small responsive vibrations that make a tap feel like a tap.
It is hard to believe a verdict of that size will stand unchanged. Appeals exist for a reason. Juries can send messages that courts later reshape. Still, a number that large is not ignorable on a Monday morning. Legal overhangs do not always move the stock the same day. They sit in the back of the model and wait.
I would not trade a watch patent case as if it were a product cycle. I would also not pretend $5.7 billion is a rounding error. The honest stance is in the middle: watch the appeal path, do not assume the first verdict is the last word, and keep the core business in view.
An Athletic Brand Gets Another Haircut Before Earnings
Another firm cut its price target on a global athletic brand to $38 from $45 and kept a hold rating. Estimates were tweaked around the edges ahead of Thursday evening results. The risks listed were familiar: a tough athletic shoe market, China challenges, and gross margin pressure.
This turnaround is taking longer than a lot of people wanted. That is why some investors stepped away during the summer. Brand love is not the same thing as brand momentum. You can respect the logo and still admit the product cycle and the regional mix are not doing the work yet.
Thursday night will not settle every argument. One print rarely does. It can tell you whether inventory is cleaner, whether full-price selling is improving, and whether China is still a drag. Those are the three questions I would keep on a sticky note.
- Listen for inventory language, not just sales growth.
- Watch gross margin more closely than a single regional beat.
- Ask whether the turnaround timeline just stretched again.
Cybersecurity Gets A Higher Target And A Safety Tie-In
A research firm raised its target on a major cybersecurity platform to $425 from $404 and kept a buy rating. The note pointed to optimism after a meeting about integrations of a systems-monitoring piece and an identity platform now operating under a new brand. That is a lot of integration talk. Integration talk only matters if customers feel one platform instead of three invoices.
Cybersecurity is more important than ever. That sentence is almost too ordinary now, which is exactly why the stocks still attract capital when the tape is messy. Another large endpoint and cloud security name sits in the same conversation. Both companies are tied into the chip giant’s new agent-safety program. That link is not accidental. If AI agents spread, the tools that police them become part of the same stack.
I like the sector more when the story is about platform depth, not just threat-of-the-week headlines. Platforms can keep customers. Point products get shopped. In a high-yield world, recurring software with switching costs is one of the few places where duration still feels earned.
How To Read A Monday Like This Without Getting Whipsawed
A list of ten items can look like a jumble. It is not. There is a spine running through it. Rates are rising. Oil is helping them rise. Policy-sensitive data arrives midweek and Friday. Meanwhile, single-stock news is splitting into two piles: companies buying their own shares or getting upgraded after pain, and companies facing slower turnarounds, legal noise, or consumer credit risk.
That split is useful. It keeps you from treating the S&P as one organism. I have sat through too many Mondays where the index barely moved and the internals were a street fight. Today has the ingredients for that kind of session if yields stay elevated into the cash open.
Here is a simple way I sort the tape when the 10-year is the loudest voice in the room.
- Respect duration. Long-growth names feel a rising discount rate first.
- Respect energy. Crude is not just a sector. It is an inflation input.
- Respect the consumer. Jobs Friday will reprice that debate in hours.
- Respect cash return. A huge buyback only matters if it is used.
- Respect legal headlines without letting them hijack a thesis.
None of that is fancy. Fancy is how people lose Mondays. Clear is how people survive them.
What The Yield Spike Does To Valuation Math
When the 10-year was lower, investors could argue that a rich multiple was just the present value of distant profits. At 5.2% and change, distant profits get smaller in today’s dollars. That is basic discounting. It is also why software and other long-duration stories can look heavy even when their last quarter was fine.
Does that mean you dump every growth name? Of course not. It means you ask whether earnings power can outrun the rate. A company that can still expand operating margin and buy back a mountain of stock has a better chance of winning that argument than a company that only has a narrative.
The chip buyback authorization is the cleanest example on the board this morning. If management spends, the share count falls and the multiple has a mechanical helper. If management waits, the market will treat the authorization as theater. I have seen both outcomes. Theater does not last long in a 5% yield world.
Oil, Travel, And The Discretionary Line
Cruise upgrades after a 26% slide are a bet that the market overshot. Maybe it did. High oil is still a real cost. A rejected peace proposal is still a real geopolitical input. Travel demand has been resilient in recent years, which is why the group ran so hard before this pullback. Resilience is not immunity.
I keep coming back to differentiation. A brand that sells a distinct trip can raise prices when fuel bites. A brand that sells a commodity trip has to eat more of the fuel bill or watch bookings wobble. That is why I have preferred the more specialized name in the group. It is also why a broad cruise rebound is not automatic just because two banks found a buy rating again.
Watch booking commentary, onboard spend, and net yield language more than the upgrade itself. Upgrades are opinions. Operating metrics are the business.
Consumer Staples And The Slow Repair Problem
The beverage downgrade is a reminder that staples are not a hiding place when the home market is the problem. People still drink and snack. They do not automatically drink and snack in the mix that supports last year’s margin. Promotions, healthier-for-you shifts, and retailer pressure can eat a turnaround one quarter at a time.
A below-market multiple can be a gift. It can also be a warning label. I lean toward the warning label when analysts start talking about waning confidence in the North America plan. That phrase is polite. It usually means the model is slipping to the right.
If you still like the name, the work is in unit trends and pricing power, not in calling the stock cheap. Cheap is the starting slide. It is not the conclusion.
Financials Are Not One Trade
The small target hike on the consumer lender with a cautious earnings stance is a useful little puzzle. Research can be constructive on a twelve-month view and still nervous about the next print. Markets often hear only one of those two sentences. Hear both.
A long tightening cycle tests underwriting. It tests marketing spend. It tests how quickly a lender can reprice assets versus deposits. Not every financial fails that test the same way. That is why a same-brush take on the sector is sloppy. Own the ones whose credit box and funding mix you can explain in two sentences. If you need a paragraph, you do not know it well enough for a week like this.
Legal Overhangs And Product Reality
Patent verdicts make loud headlines because the numbers are huge and the product is sitting on millions of wrists. The company’s denial and planned appeal matter. So does the fact that haptics are now a core part of how devices feel, not a gimmick. That combination keeps the story alive even if the final check is much smaller than $5.7 billion.
Investors should separate three layers. One is the legal process. One is the cash risk if the verdict survives in some form. One is whether customers care. Customers rarely care about a patent fight unless the product changes in their hand. So far this is a courtroom story more than a product story. Keep it there until facts move it.
What Thursday Night In Athletic Wear Could Change
The lower target into earnings is not a shock. The brand has been working through a longer rebuild than bulls wanted. China remains a swing factor. Gross margin remains the tell. The shoe market remains crowded. Those three lines have been in every note for months. Repeating them does not make them less true.
What would change my mind is evidence that full-price selling is healing and that the product pipeline is landing with younger buyers, not just nostalgia buyers. What would confirm the cautious stance is another quarter of “progress, but.” Progress-but is how turnarounds age into value traps.
Agent Safety And Why Cyber Still Has A Seat
The software platform meant to keep AI agents from misbehaving sounds like a niche line until you picture agents sending mail, moving files, and touching customer data. Then it sounds like a control plane. Control planes get budget. That is why the cybersecurity meeting notes matter this morning. Integrations only work if identity, monitoring, and enforcement sit in one operating picture.
I remain constructive on the better platforms in this group, with the usual caution about valuation after long runs. High yields punish rich multiples. Strong demand and high retention can offset that. The next few quarters will show which vendors are selling a suite and which are still selling a logo.
A Practical Checklist Before The Open
If you only have five minutes before the bell, skip the noise and run a short list. Yields first. Crude second. Futures third. Then the single-stock pile: buyback authorization versus actual buying, cruise upgrades versus fuel, consumer turnaround versus multiple, lender caution versus target hike, patent verdict versus appeal, athletic wear versus Thursday night, cyber versus integration proof.
That is enough. You do not need seventeen frameworks. You need to know which stories are rate stories, which are oil stories, and which are company-specific. Mix those three buckets and you get the week.
The market is allowed to be two things at once: weak at the index level and full of names that still have work to do on their own.
I keep coming back to that idea because it is the one that saves people from all-or-nothing thinking. You can dislike the yield tape and still like a buyback that is large enough to matter. You can dislike high oil and still study a cruise name that already fell 26%. You can dislike a consumer turnaround and still admit the multiple is no longer heroic. Holding two thoughts is part of the job.
Risks That Can Flip The Script By Friday
Wednesday’s inflation gauge can cool the yield panic if it lands soft. It can also add fuel if it stays firm. Friday’s jobs number can revive the soft-landing camp or revive the too-hot camp. Either print can overpower a patent headline or a target change. That is the hierarchy. Macro first this week. Tickers second.
Geopolitics can override both. A rejected proposal is already in the price of oil this morning. Further headlines can push crude again. If that happens, cruise names and rate-sensitive growth will not wait for your thesis to catch up.
Position sizing is the unglamorous answer. Smaller bets survive loud weeks. Large bets on a single narrative do not.
A Closing Read On The Tape
Monday is not asking you to solve the year. It is asking you to respect a 10-year yield above 5.2%, a three-percent jump in crude, and a calendar that can reprice both by Friday. Around that core sit a historic buyback increase, a staples downgrade, cruise upgrades after a sharp drop, a curious bank target hike, a huge haptics verdict, a lower athletic target into earnings, and a cyber target raise tied to agent safety.
That is a full plate. Treat it like a plate, not a buffet you have to finish. Pick the two or three threads that actually touch your holdings. Leave the rest for the people who get paid to have a take on everything.
I will be watching whether the 10-year stays elevated into the afternoon and whether oil holds its gain. If both cool, the single-stock tape gets more room to breathe. If both stay hot, even good news on buybacks and upgrades will have to work harder. That is the week in one line. Everything else is detail, and detail still matters, just not first.