
I keep hearing the same question in conversations with people who actually have money at risk: if the 10-year is already sitting at levels we have not lived with for years, why has the equity market not folded? It is a fair question. Higher Treasury yields raise the hurdle for stocks. They offer a cleaner return without earnings risk. They also shrink the present value of distant cash flows, which is supposed to hurt growth names first. And yet the tape has been stubborn. The benchmark 10-year has traded above 5.21 percent. The long bond has printed above 5.5 percent. The S&P 500, meanwhile, has sat only about 1.4 percent under an August intraday peak near 7,816. That gap is the whole puzzle.
Why Higher Yields Have Not Broken Equities Yet
People treat the 10-year as a switch. Cross some round number and stocks must fall. Markets do not work like that. They work in ranges, in multiples, and in messy comparisons between what you can earn in a government note and what you can earn in a business. I have found that the pain threshold is usually higher than the commentary suggests. Not infinite. Just higher.
Think about what a rising 10-year actually does. First, it competes with equities for capital. A locked-in coupon with no default risk starts to look decent when it clears 5 percent. Second, it changes discount rates. Future profits get marked down in today’s dollars. That math is brutal for companies whose story lives a decade out. Third, it tightens financial conditions without the central bank needing a press conference. Mortgage rates follow. Corporate borrowing costs follow. Buybacks funded with cheap debt get less cute.
So why the shrug from stocks? Because the economy has not cracked, earnings estimates have not collapsed, and the multiple compression that everyone expected at 4 percent, then 4.5 percent, then 5 percent simply has not arrived in size. Perhaps the most interesting aspect is how stable forward price-to-earnings ratios have been across a huge band of yields. That is not a rumor. That is the historical pattern that keeps getting ignored in the daily panic.
The Valuation Band That History Actually Shows
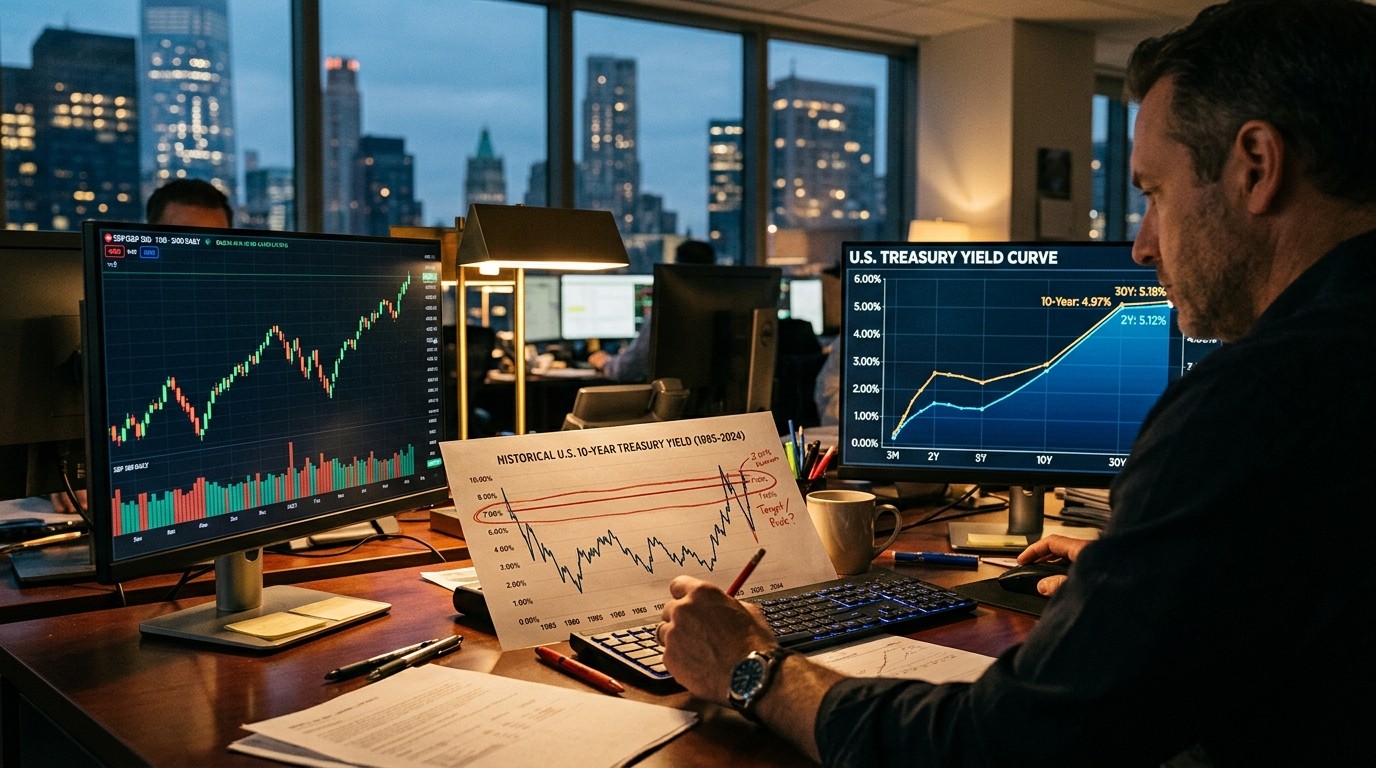
Go back to the mid-1980s and look at how the S&P 500 forward multiple behaved as the 10-year moved around. Between a yield of roughly zero and 7 percent, that multiple clustered near 16. Not perfectly flat. Not immune to recessions or bubbles. Relatively stable, though. Once the 10-year pushed through 7 percent, the median multiple dropped toward 12.1. That is the cliff, not 5 percent and not the first print with a five-handle.
Let that sink in. Investors have been treating 5 percent as a crisis level. History treats 5 percent as still inside the zone where equities can keep a mid-teens multiple if earnings hold up. The last time the 10-year closed with a seven-handle was July 8, 1996, at 7.06 percent. That is almost a generation ago. A lot of active managers have never traded a market where the risk-free rate sat there for long.
We continue to see higher rates ahead. While supply-demand dynamics may add pressure, we do not see rates as restrictive enough yet to halt the move.
– Rates strategist, base-case note
That line matches what I keep seeing in the data. The base case from serious rates desks is not a sprint to 7 percent. It is more grind: firmer growth, stickier inflation than the last cycle, and a market that still wants more term premium. They remain short the front end and underweight duration. In plain English, they do not think the bond selloff is finished, and they do not think 7 percent is the default destination either.
How The Discount Rate Really Hits Growth Stocks
Discounting is not abstract. Take a company that is expected to earn the bulk of its value after year five. Raise the discount rate by 100 or 150 basis points and the present value drops hard. That is why software, biotech platforms, and anything sold as a long-duration cash-flow story twitch first when yields jump. It is also why profitable cash generators with near-term free cash flow often look oddly calm.
In my experience, the market does not punish all equities equally when the 10-year rises. It re-ranks them. High-quality compounders with pricing power can live with a higher hurdle. Speculative stories that needed free money cannot. That sorting process can look like a “stock market that will not fall” even while leadership quietly rotates. Indexes hide that rotation until it becomes obvious.
There is another wrinkle. If nominal growth is strong, earnings can rise fast enough to offset a lower multiple. That is the optimistic path. If growth slows while yields stay high, you get the ugly mix: weaker profits and a tighter discount rate at the same time. History’s 7 percent line is about the multiple. The earnings path still decides whether the index actually breaks.
Why Five Percent Feels Worse Than It Looks On A Chart
Psychology matters. A generation of investors learned markets in a world of zero rates and quantitative easing. Five percent on the 10-year feels violent because the reference point was 1 percent, not 6 percent. Mortgage payments jump. Housing activity cools. Private equity models that assumed cheap leverage look worse. None of that requires the S&P multiple to collapse tomorrow.
I still watch the 10-year every morning. I just refuse to treat every uptick as a verdict on equities. The comparison that matters is the equity risk premium after you subtract a realistic risk-free rate. When the 10-year was near 1 percent, stocks could look expensive and still “win” the allocation debate. At 5 percent, the debate is tighter. At 7 percent, history says the multiple itself usually gives way.
- Yields between 0 percent and 7 percent: forward P/E clustered near 16
- Yields above 7 percent: median forward P/E nearer 12.1
- Last 7-handle close on the 10-year: July 1996
- Current tape: yields at multi-decade highs, index still close to record territory
Those four bullets are the skeleton. Everything else is interpretation. Interpretation is where people get sloppy.
Supply, Demand, And The Quiet Pressure Under Bonds
It is not only the policy rate. The Treasury has to fund a large deficit. Foreign official buyers are less mechanical than they used to be. Banks have balance-sheet limits. Money market funds can absorb bills. They are less eager to swallow long duration when inflation risk is still live. That mix can lift term premium even if the central bank is done hiking.
I have found that investors obsess over the next meeting statement and underweight the simple arithmetic of issuance. When supply is heavy and duration demand is polite rather than desperate, the 10-year can drift higher without a dramatic inflation surprise. That drift is what unnerves equity desks. It is slow. It is persistent. It does not need a crisis headline.
Does that mean 7 percent is coming? Not in the base case I find most credible. It does mean the old habit of fading every yield spike because “the Fed will save duration” is a weaker trade than it was in the 2010s. Restrictive is a feeling until it shows up in credit stress, labor demand, or capex. A lot of the real economy has not sent that signal in a clean way.
What Actually Transmits From Bonds Into Stocks
Transmission is the unglamorous part. Higher 10-year yields feed into 30-year mortgage quotes. Households delay purchases. Housing-related employment cools with a lag. Corporate treasurers refinance less. Interest expense rises for floating-rate borrowers. Pension discount rates move. All of that can be true while the S&P still prints strong sessions on mega-cap earnings.
The index is not the economy. That sentence is overused and still under-applied. A handful of cash-rich firms can carry a cap-weighted benchmark while rate-sensitive sectors quietly de-rate. If you only watch the headline level, you miss the internal fracture. If you only watch the 10-year print, you miss the earnings shield that has kept multiples from collapsing so far.
| 10-Year Zone | Typical Multiple Behavior | What Investors Feel |
| 0% to 3% | Multiples can expand if growth is intact | Duration assets look scarce |
| 3% to 7% | Forward P/E often holds near the mid-teens | Competition with bonds rises, stocks can still win |
| Above 7% | Median multiple historically closer to 12 | Risk-free becomes a real alternative |
Tables flatten a messy world. Recessions, oil shocks, and policy errors can smash multiples inside the “safe” yield band. The 7 percent line is a historical median, not a law. Still, it is a better anchor than a round number that happens to scare people on television.
The Fed Path Versus The Bond Market Path
Equity investors want a clean story: the central bank cuts, yields fall, multiples expand. Bond investors keep ruining that story with supply, term premium, and sticky services inflation. You can have a policy rate that stops rising and a 10-year that still grinds higher. That combination is awkward for models that treat the funds rate as the only input that matters.
In my view, the more useful question is not “will they cut.” It is “are real rates high enough to slow nominal demand without a crash.” If the answer is no, bonds can keep cheapening while stocks argue that earnings will be fine. That argument can last longer than shorts expect. It can also end in a hurry if inflation re-accelerates or if credit finally gaps wider.
Stay underweight duration if you believe the move has further to run. That is the rates desk recommendation in the material that started this whole debate. Stay selective in equities if you believe the multiple only breaks much higher from here. Those two stances can live in the same portfolio. They usually should.
Growth, Inflation, And The Case For Still-Higher Yields
Robust growth plus higher inflation is a nasty cocktail for bonds and a mixed one for stocks. Revenues can hold up. Input costs and wage bills can squeeze margins. Discount rates rise. The winners are firms that can pass through prices without losing volume. The losers are volume stories with thin buffers.
I do not buy the idea that we have already seen the peak in the 10-year just because a prior cycle peaked lower. The inflation regime is different. Labor markets tightened in a different way. Fiscal policy is not running the same script. You can dislike that conclusion and still respect the direction of travel: higher-for-longer is not a slogan when the 10-year is already printing multi-decade highs and the economy has not rolled over.
Expectations of firmer policy, solid growth, and livelier inflation can keep pressure on the long end even if a 7 percent print is not the central forecast.
That is the uncomfortable middle. Not crash. Not relief rally in duration. Just a market that has to relearn how to price capital when cash actually yields something.
What Investors Should Watch Instead Of One Magic Number
If you only wait for 7 percent, you will miss the damage that happens earlier in rate-sensitive corners. Watch credit spreads, not just the Treasury. Watch refinancing calendars for weaker issuers. Watch housing turnover and the gap between listed mortgage rates and what buyers will actually pay. Watch earnings revisions for the bottom two-thirds of the index, not only the giants.
- Track the 10-year against forward earnings, not against last week’s close.
- Separate mega-cap cash machines from long-duration stories that need cheap money.
- Treat 5 percent as competition, not as a guaranteed equity peak.
- Treat 7 percent as the historical zone where multiples usually compress hard.
- Keep duration light if issuance and inflation risk still lean against bonds.
None of that is a trading signal by itself. It is a checklist so you do not outsource your entire framework to a single headline yield.
Portfolio Choices When The Hurdle Rate Keeps Rising
I would rather own businesses that generate cash now than stories that promise cash later, at least while the 10-year is exploring the high-4s and low-5s with an open door to more. That is not a permanent religion. It is a relative call. If yields slump because growth dies, the long-duration names can rip. If yields slump because inflation calmly fades and earnings stay firm, almost everything works. The hard regime is the one we have been living: yields up, index near highs, internals uneven.
Quality still matters. Balance sheets still matter. The ability to fund capex without begging the bond market still matters. Those sentences sound boring because they are the part that survives when the discount rate stops being a free gift.
Some readers will want a single target. Fine. History’s blunt answer is that a meaningful, sustained hit to the market multiple has tended to show up nearer 7 percent on the 10-year, not at the first multi-decade high above 5. That does not give anyone permission to be reckless. It does give context. Context is what the daily tape refuses to provide.
A Closer Look At Multiples, Earnings, And Patience
Let me slow this down, because this is where people talk past each other. A stable multiple around 16 with the 10-year anywhere under 7 percent does not mean stocks are cheap. It means the market has historically been willing to pay that multiple across a wide interest-rate landscape. Cheapness is a different question. It depends on the earnings you believe and the cycle you think you are in.
If forward earnings are too optimistic, a 16 multiple is a trap even at a 4 percent 10-year. If forward earnings are conservative and nominal growth is firm, a 16 multiple at a 5.2 percent 10-year can still be a hold. I keep coming back to that because yield-only analysis is lazy. It treats the numerator as fixed. The numerator is not fixed.
Have you noticed how often commentary skips the earnings path and jumps straight to “rates up, stocks down”? That shortcut worked in some windows. It failed in others. The 1990s eventually saw both higher yields at times and a massive equity boom, until valuation and narrative overran the fundamentals. Different decade, different drivers. The lesson is not that 7 percent is harmless. The lesson is that the market can digest a lot of yield if profits keep showing up.
Mortgages, Households, And The Slow Bleed
The 10-year is the reference a lot of people use for mortgage pricing. When it jumps, payment shock is real for anyone who is not sitting on an old cheap loan. Housing then becomes the lagging indicator that equity bulls prefer to ignore and equity bears prefer to overplay. Activity can slump without taking the whole labor market with it, at least for a while. That “for a while” is doing a lot of work.
I have sat through enough cycles to distrust instant conclusions from one housing print. Locked-in homeowners do not sell. Inventory stays tight. Prices get sticky even as volumes fall. That mix can keep wealth effects from collapsing even as affordability looks terrible for new buyers. Stocks tied to existing-home ecosystems suffer. Stocks tied to high-income services can look fine. Again: the index can hide the bruise.
If you want an early warning that yields are finally “hitting stocks” in a broad way, do not wait for the 10-year to tag 7. Watch whether the consumer that supports the upper end of spending starts to pull back because asset markets wobble and borrowing costs bite at the same time. That combination is nastier than a lone Treasury spike.
Duration, Positioning, And Why Bonds Can Stay Heavy
Staying short 2-year rates and underweight duration is a way of saying the front end still prices too much relief and the long end still does not compensate you enough for inflation and supply risk. You can disagree with the sizing and still accept the logic. The 2-year is a policy bet. The 10-year is a soup of policy, growth, inflation, and how much paper the market must digest.
When those ingredients all lean one way, yields rise even if every talking head is exhausted by the subject. Exhaustion is not a catalyst. Positioning can be. If too many accounts are still reaching for duration because last decade trained them to do it, the path of least resistance can stay higher for longer than comfort allows.
Simple yield-to-equity map:
  Under 3%: bonds rarely compete
  3% to 7%: stocks can keep mid-teen multiples
  Through 7%: history says the multiple usually cracks
  Wildcard: earnings revisions can override the map
I like crude maps. They keep you from inventing a new theory every session. They also remind you where the exceptions live. Earnings revisions are the exception that can save or sink the whole framework.
What “Meaningful Hit” Should Mean For You
Define the term or you will argue in circles. A meaningful hit is not a two-day dip. It is a sustained de-rating of the market multiple, broad leadership failure, or an earnings recession that the index cannot ignore. By that standard, multi-decade highs in the 10-year have not yet delivered the event people keep previewing.
Could they still? Of course. 7 percent is not a force field that protects 5.5 percent. Credit can break first. A policy mistake can break first. A growth scare can break first. History’s median is a guide for the multiple, not a shield against every other risk in the system.
If I am honest, the part that surprises me is not that stocks have held up. It is how little humility the 5 percent narrative showed when the first five-handle prints arrived. Markets had already told us, over decades, that the scary number sat higher. We just did not want to hear it because the last fifteen years trained everyone to treat any yield increase as an emergency.
A Practical Way To Live With The Uncertainty
Build a portfolio that can survive two stories. Story one: yields grind toward the mid-5s or higher, growth holds, multiples stay in the historical mid-teens band, and leadership stays with cash-rich compounders. Story two: yields keep rising or stay high, growth slips, and the multiple finally does the thing people have been calling for since 4 percent. Those stories need different shock absorbers. Cash and short duration help in both. Blind long-duration bets help in neither unless you have a precise view on disinflation.
I would not mortgage the house to short the index just because the 10-year looks ugly on a long chart. I also would not pretend a 5-handle yield is irrelevant. It is relevant. It is simply not the historical tripwire for a full valuation reset.
Ask a sharper question than “when do yields kill stocks.” Ask “at what yield does the average buyer refuse to pay 16 times forward earnings.” The record since the mid-1980s points near 7 percent. Until the 10-year lives there, or until earnings crack, the market can keep doing this irritating thing where it refuses to crash on schedule.
That refusal is not a promise. It is a reminder. The hurdle is higher than the first scare. The work is in earnings, credit, and whether this cycle’s inflation really settles. The 10-year will keep talking. The multiple will answer later, and probably later than the loudest voices want.