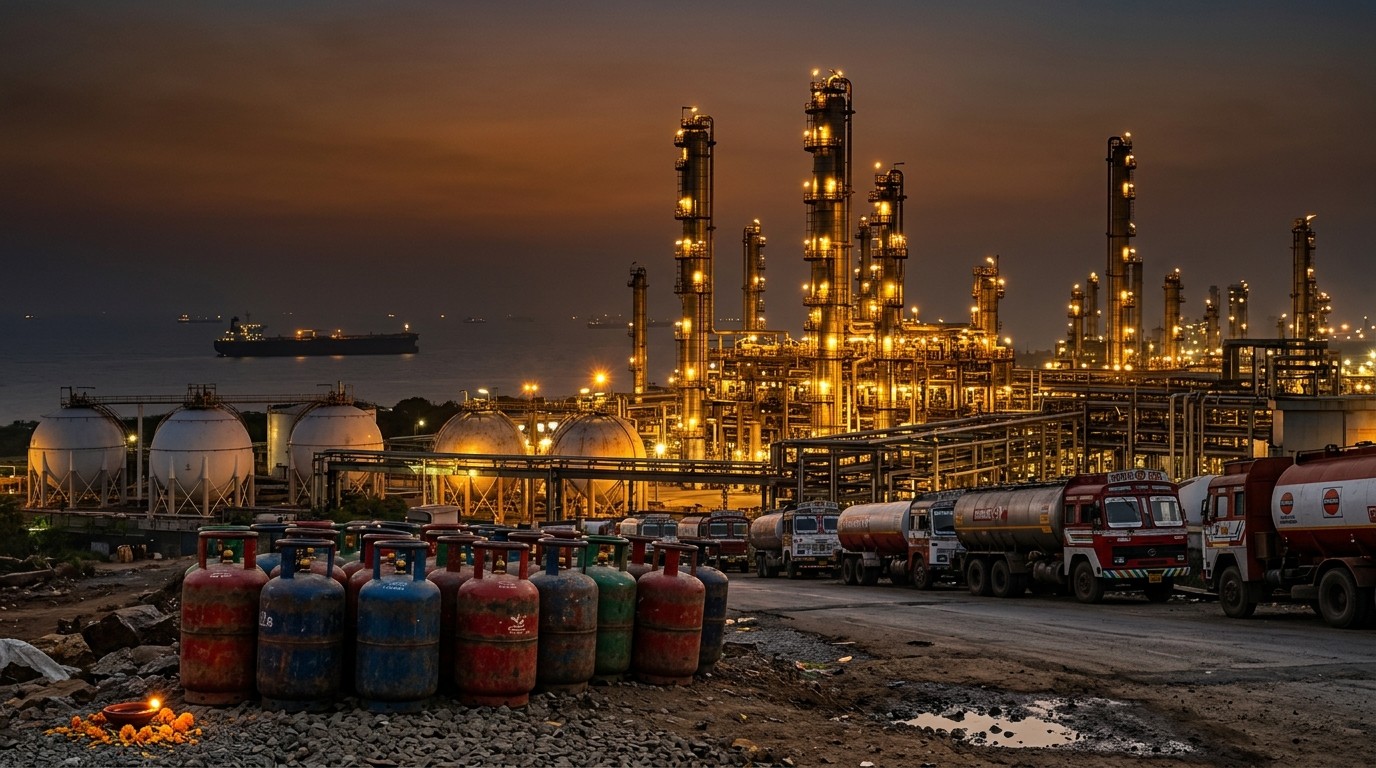

Have you ever noticed how a cooking-gas cylinder can suddenly become a national story? That is where India sits right now. Households are heading into the festive stretch, kitchens are running hotter, and the usual Middle East cargoes are not sliding through as freely as they once did. I have been watching energy markets long enough to know that when a chokepoint tightens, the first thing a big importer does is look inward. Indian state refiners did exactly that. Local liquefied petroleum gas output has jumped close to twenty percent in September compared with the August average, and the number is not a rounding error. It is a policy reflex wrapped in steel tanks and daily production logs.
Why Local LPG Production Became The Immediate Lever
Roughly three in five Indian homes still treat bottled gas as the main cooking fuel. That fact alone turns a shipping delay into a kitchen-table problem. When the strait that once carried about ninety percent of the country’s LPG imports grew congested, consumers felt it quickly. Some cut back. Industry cut back harder. Demand destruction is an ugly phrase, but it is the honest one. Prices and availability both did the talking.
So far this month, domestic output has averaged about forty-four thousand tons a day. That is nearly a fifth above the August pace. In my experience, refiners do not flick a switch that large unless the commercial case is obvious and the political case is louder. Festive buying was already climbing. Import optionality was narrower than planners wanted. The answer was more molecules from Indian units, even while cargoes from other basins were being lined up.
Energy security is not a slogan when sixty percent of households cook on the same molecule you are trying to replace at the dock.
The Import Map That Suddenly Looked Too Narrow
For years the supply picture looked tidy. Middle East volumes dominated. The route was short, the contracts were familiar, and the logistics teams knew every berth. Then the waterway that funnels those cargoes became a bottleneck. That is not a metaphor. It is a physical constraint. Ships wait. Insurance tightens. Schedules slip. You can diversify on a slide deck overnight. You cannot move a very large gas carrier through a contested lane by wishing.
India did not sit still. Cargoes from the United States and African producers have been added to the mix. Volumes from the United Arab Emirates have also been pushed higher in recent months. The Emirates still sit at the top of the supplier list. That matters because one large producer has publicly stressed that contracted October volumes for Indian buyers will be delivered. Reliability language like that is not poetry. It is a signal to procurement desks and to households that the cylinder truck should still show up.
There is a practical wrinkle worth lingering on. Crude and product flows out of that Gulf producer have kept moving by using a pipeline path to a more open loading point and by shuttling smaller vessels to deeper water, then topping up bigger tankers. It is messy. It is expensive. It also explains why the largest supplier can still talk about meeting contracted LPG even while the headline strait looks blocked on a map.
Festive Demand Meets A Quieter Industrial Floor
Seasonality in India is not a soft variable. Festivals pull LPG into homes, catering kitchens, and small commercial users. You can almost set a calendar by the extra cylinders. That pull arrived on schedule. What did not arrive on schedule was last year’s industrial appetite. Several market watchers now expect overall LPG demand this year to land below last year’s print, even with the festive bump, because factories and process users have already throttled back.
I find that split fascinating. Households still need dinner. Industry can postpone a batch. When prices jump or trucks run late, the factory is the first to blink. That is demand destruction in plain clothes. It also gives refiners a little room. They can raise output for the kitchen market without immediately flooding a roaring industrial bid that is no longer there.
- Household cooking still anchors the bulk of visible consumption.
- Festive weeks add a sharp, short-lived lift in packaged cylinders.
- Industrial users have already reduced offtake after the first supply scare.
- Net demand may still undershoot last year even if kitchens stay busy.
What A Twenty Percent Output Lift Actually Requires
Raising LPG yield is not magic. Refineries choose cuts. They change operating severity. They pull more propane and butane from streams that might otherwise go into other products. They also run units harder when crude slates allow it. None of that is free. Opportunity cost shows up in gasoline, naphtha, or fuel oil balances. Plant managers know the trade. When the bottled-gas market is tight and politically sensitive, the trade tilts toward LPG.
State-owned complexes have an extra mandate that private plants feel less sharply. Keeping cylinder racks full is part of the social contract around cooking fuel. That does not mean economics disappear. It means the constraint set is different. If you have ever sat in a planning meeting during a supply scare, you know the tone. Nobody wants to explain an empty depot in a dense urban belt during festival week.
Perhaps the most interesting aspect is how fast the daily average moved. A near twenty percent step-up versus the prior month is not a gentle optimization. It looks like a coordinated push. Throughput, cut points, and offtake logistics all had to line up. Trucks, bottling plants, and dealer networks had to absorb the extra tons. That last mile is where pretty production charts meet potholes.
Diversification Is Real, But It Is Not Instant Insurance
American and African barrels and products help. They also travel farther. Longer voyages mean more working capital on the water and more exposure to freight spikes. Quality specs can differ. Discharge windows can bunch up at Indian ports that were designed around a shorter-haul pattern. Diversification reduces single-point failure. It does not erase basis risk or timing risk.
The Emirates route still does a lot of heavy lifting. That concentration is both a comfort and a residual worry. Comfort, because the supplier has said contracted October volumes are on track. Worry, because any further operational snag in the Gulf still hits the same corridor. I would not call the current mix fragile. I would call it better than last month and not yet boring.
We continue to provide reliable and secure LPG supplies to our customers and work closely with them to meet their requirements.
– Supplier statement on contracted Indian volumes
How Households Absorbed The First Shock
When imports snarl, the household does not read a tanker tracker. The household notices a late delivery, a higher refill price, or a dealer who suddenly has a story. Some families stretch a cylinder. Some switch a burner to an electric coil for part of the day. Some simply cook less elaborately during the crunch. That is quiet rationing. It does not show up as a protest. It shows up as a flatter demand curve.
Sixty percent of homes on LPG is a huge installed base. It is also a reminder that energy transition slogans and daily cooking are not the same conversation. Piped gas and electrified cooking are growing, sure. They have not retired the cylinder. Until they do, a maritime chokepoint remains a kitchen risk. That is the unglamorous truth behind the production spike.
The Price And Policy Overlay Nobody Should Ignore
Cooking fuel in India is never only a free-market story. Subsidies, administered prices, and political sensitivity sit on top of the physical balance. When wholesale costs jump because freight and risk premia jump, someone eats the difference. Sometimes it is the budget. Sometimes it is the oil marketing company. Sometimes it leaks into the retail price and households eat it. The allocation of pain changes with the season and the electoral calendar. I will not pretend that is elegant. It is how the system has worked for years.
A domestic production surge helps the optics and the physics at the same time. More local tons mean fewer emergency cargoes at panic freight. They also give policymakers a talking point that sounds like competence. Both matter. Markets trade the tons. Voters remember the cylinder.
| Pressure Point | Near-Term Effect | Who Feels It First |
| Strait congestion | Delayed Middle East cargoes | Importers and coastal terminals |
| Festive cooking | Higher packed-cylinder offtake | Households and dealers |
| Industrial caution | Softer process demand | Factories and bulk buyers |
| Refinery yield shift | More LPG, other cuts adjust | Plant slates and product balances |
| Longer-haul imports | Higher freight and working capital | Procurement teams |
Logistics After The Gate: Bottling, Trucks, And Dealers
Producing extra tons at a refinery is only half the job. LPG has to be stored, moved, bottled, and sold. Bottling plants have rated capacity. Truck fleets have driver limits and road rules. Dealers have working capital. When output jumps twenty percent in a month, those layers get tested. If one layer wheezes, you get local shortages even while the national average looks healthy. That mismatch is common and under-discussed.
Coastal plants can push product by pipeline or coastal tanker to inland packing units. Inland plants lean on road. Festival weeks already crowd highways. Add extra LPG movements and you get congestion on the same corridors that carry sugar, textiles, and parcel vans. It is not dramatic until a cluster of cities reports thin inventories on the same weekend. Then it is very dramatic.
What The Demand Destruction Signal Is Really Saying
Industrial users are price and reliability sensitive in a way households are not. A ceramics kiln or a chemical unit can delay a run. A family still needs to boil milk. When the first import shock hit, process demand cracked first. That is why full-year consumption can lag even as kitchens stay busy. The festive lift is real. It may not be large enough to offset the industrial hole.
I have found that people over-read household anecdotes and under-read factory run rates. Both matter. If you only watch cylinder queues, you miss the quieter bid that disappeared from bulk terminals. If you only watch factories, you miss why politicians care about this molecule more than almost any other petroleum product.
Refinery Slates, Opportunity Cost, And The Quiet Trade-Off
Every extra ton of LPG is a ton that did not stay in another stream. Depending on the crude and the configuration, that can mean less naphtha for petrochemicals or a different gasoline blendstock balance. In a tight LPG week, that trade is easy to defend. In a balanced week, traders argue about it. Right now the argument is short. Cooking fuel wins.
Complexes with flexible coking or cracking capacity have more room to maneuver. Simpler topping plants have less. That is why a national average can hide a lopsided effort. A few large state sites may be doing the heavy lifting while others run closer to normal. I would love a plant-by-plant yield table. We rarely get one in real time. We get the blended daily average and have to infer the rest.
Why The Emirates Still Sit At The Center Of The Story
Even with new flags on the import board, the largest supplier remains the same. That is not inertia for its own sake. It is proximity, contract history, and a demonstrated ability to keep product moving through workarounds. A pipeline bypass for crude and a shuttle system for products is not pretty. It is effective enough to support a public assurance on October LPG.
For Indian buyers, that assurance is worth more than a generic diversification headline. You can buy a spot cargo from farther away. You cannot always replace a baseload relationship in a single quarter. The smart posture is both: keep the core supplier close and keep the alternative routes warm. That is what the recent pattern looks like, at least from the outside.
Energy Security Without The Brochure Language
People love to print the phrase energy security on a cover slide. The working definition here is simpler. Can a family light a burner in October without a scavenger hunt? Can a bottling plant plan next week’s shifts? Can a refinery raise a yield without breaking another product market? If the answers stay yes, the system is holding. If any answer flips, the production spike was only a first patch.
Security also means not pretending a chokepoint is theoretical. When ninety percent of a fuel’s imports used to travel one lane, that lane is part of the national energy system whether diplomats like the wording or not. Building domestic output, adding Atlantic and African options, and keeping Gulf contracts alive are three different tools. Using only one of them would be careless. Using all three is how grown-up importers behave.
- Raise domestic LPG yield where plants can do it without wrecking other balances.
- Keep contracted Gulf volumes moving through whatever operational workaround exists.
- Book longer-haul cargoes early enough that freight does not become the story.
- Watch inland logistics so extra tons do not stall between plant and dealer.
- Accept that industrial demand may stay soft and plan inventories accordingly.
What Could Still Go Sideways From Here
A further tightening of the waterway would test the workarounds again. Freight could spike just as festive offtake peaks. A refinery outage at a key LPG-producing site would punch a hole in the new domestic cushion. A bottleneck at a handful of bottling plants could create city-level shortages that national averages will not show. None of that is prediction. It is a checklist.
On the other side, a smoother October delivery month from the main supplier plus a few well-timed Atlantic cargoes could take the drama out of the tape. Soft industrial demand would help inventories look comfortable even if household use stays firm. Comfort is possible. It is not guaranteed. That is the honest middle.
Reading The Signal For Broader Product Markets
When refiners chase LPG, other light-end balances can shift. Naphtha availability for crackers, gasoline blendstock quality, and even some fuel oil math can move at the margin. Those knock-ons rarely make the same headlines as a cooking-gas shortage, yet traders live in those margins. If the yield push lasts beyond the festival window, watch those adjacent markets. If it fades in November, treat it as a seasonal patch.
Crude slates matter too. Some grades naturally throw more LPG. A forced change in crude mix because of the same maritime stress can either help or hurt the LPG push. That second-order effect is easy to miss if you only track the finished-product import list.
A Note On Communication And Public Confidence
Households do not need a lecture on distillation curves. They need a dealer who answers the phone and a price that does not lurch without warning. Clear talk about inventories and expected arrivals does more for confidence than a glossy campaign. The supplier comment about meeting contracted October volumes is the right kind of sentence. Short. Specific. Tied to a month people can mark on a calendar.
I have a soft spot for that style. Markets drown in adjectives. A delivery commitment with a date beats a paragraph about resilience. Indian buyers and the main Gulf supplier both seem to understand that, at least in the latest public remarks.
The Human Scale Behind The Daily Tonnage
Forty-four thousand tons a day is an abstract figure until you unpack it. It is millions of meals. It is tea stalls, wedding caterers, and apartment kitchens. It is also a reminder that modern urban life still leans on a nineteenth-century idea: a portable fuel in a steel bottle. We can talk about heat pumps and induction plates all afternoon. Tonight, a lot of dinners will still come off a blue flame.
That is why a shipping lane thousands of kilometers away can rearrange a refinery’s yield targets in a matter of weeks. The chain is long. The consequence is local. If that tension feels familiar, it should. Food, fertilizer, and fuel all travel the same vulnerable geometry. LPG is simply the molecule that shows up in the kitchen first.
How To Watch The Next Few Weeks Without Getting Lost
Ignore the loudest social posts. Track four things. Domestic daily output versus the new September run rate. Arrival windows for Gulf and longer-haul cargoes. Packed-cylinder dealer inventories in a handful of big cities. Industrial offtake at bulk terminals. If those four stay orderly, the story cools. If one breaks, the production headline will get a sequel.
Watch list, plain version:
  Domestic LPG run rate
  Contracted Gulf arrivals
  City dealer stocks
  Industrial bulk demand
That is not sophisticated. It is sufficient. Complexity is often an excuse for missing the obvious.
A Longer View After The Festival Lights Dim
Once the seasonal spike passes, the structural question remains. How much LPG does India want to make at home as a standing hedge, not a crisis sprint? How much import capacity should sit outside a single waterway? How fast can cooking electrify in cities without leaving smaller towns stranded on cylinders? Those are multi-year files. The September output jump is a chapter, not the book.
I would not bet that refiners go back to the old yield mix the day after the last festival sweet is served. Some of the extra LPG habit may stick if planners decide the insurance value is worth the opportunity cost. Some of it will fade when freight calms. The split will tell you how much of this episode was panic and how much was learning.
What This Episode Quietly Reveals About Import Dependence
Large importers always live with a gap between comfort and control. India can refine more, store more, and buy from more flags. It cannot relocate geology. The Middle East will remain central to seaborne LPG for a long time. The lesson is not autarky. The lesson is optionality with a core supplier still in the room. That is a less exciting sentence than a blockade headline. It is also closer to how the physical market works.
Optionality costs money in quiet years. It looks cheap in loud years. September was loud. Paying for extra domestic yield and extra long-haul optionality is the premium on a policy that does not want kitchen-line photos on the evening news. You can argue about the size of the premium. Arguing that the premium should be zero is how countries get surprised twice.
Final Thoughts From A Markets Desk, Not A Slogan Factory
The core facts are straightforward. Indian refiners lifted LPG output by nearly a fifth as festive demand arrived and a vital import lane tightened. Alternative cargoes have been added. The largest traditional supplier says October contracts will be honored. Households still lean on cylinders. Industry has already flinched. Full-year demand may still trail last year.
If you need a moral, keep it small. Physical markets punish single points of failure and reward boring redundancy. A twenty percent domestic lift is the opposite of boring to plant operators. To a family lighting a burner in October, boring is the goal. That gap between operational strain and household calm is the whole job.
Watch the run rate. Watch the arrivals. Watch the dealer sheds. And remember that a cooking-gas story is never only about gas. It is about whether a dense, festival-heavy, import-exposed economy can keep a simple flame reliable when the map gets complicated. So far, the system is answering with more local tons. That is the right first move. It will not be the last one if the waterway stays ugly.