
Have you ever watched a transfer sit in limbo for two days, then watched the fee eat a chunk of what was supposed to arrive? That is not a niche complaint. In large parts of Africa and the Gulf, moving value still feels like asking permission. So when Tether and Shiga said they want self-custodial wallets for USD₮, Bitcoin and Tether Gold in those regions, I sat up. Not because another wallet app is exciting. Because the pitch is blunt: keep the keys, fund from local cash or dollars or Bitcoin, and stop treating custody as a default tax on trust.
What This Partnership Is Actually Trying To Build
The announcement is dated September 28. It is a plan, not a live rollout with a public calendar. That distinction matters. Plenty of crypto headlines sell a finished product when the real story is a toolkit and a roadmap. Here the toolkit is Tether’s open-source Wallet Development Kit, often shortened to WDK. Shiga would wrap that kit into two products with different audiences.
ENTA is aimed at people and businesses. Pulse is aimed at banks and fintech firms that want payment corridors, treasury flows and settlement without rebuilding wallet plumbing from scratch. I’ve found that dual-track launches are usually more honest than a single “super app for everyone” slide. Individuals and compliance teams do not want the same interface. They rarely even want the same deployment model.
This is also not a first date. Tether invested in Shiga Digital in June 2025. At that point Shiga already talked about virtual accounts, foreign exchange, treasury work and over-the-counter deals for African firms. The new chapter is less about adding another rail and more about putting self-custody under those rails. Whether that holds up in practice depends on licences, corridors and fees that have not been published yet.
Why Self-Custody Is The Headline, Not The App Name
Custodial products are easier to ship. A company holds the keys, resets passwords, freezes accounts, and answers support tickets. That convenience is real. It is also the reason so many users treat “wallet” as a login screen instead of a set of keys. Self-custody flips the risk. You control the assets. You also own the recovery problem if you lose the device or the seed.
Tether’s chief executive, Paolo Ardoino, framed WDK as infrastructure that lets firms build products where users keep control. The quote that stuck with me was simple rather than theatrical.
Together with Shiga, we are bringing that infrastructure to markets where people and businesses face real challenges protecting savings and moving money across borders.
– Paolo Ardoino
That line works because it names two jobs that official rails often fail at the same time: store value without quiet erosion, and send value without a punishing spread. In my experience, products that try to do both usually get pulled toward one pole. Either they become a savings box with weak payments, or a payment pipe with weak savings. A three-asset wallet is an attempt to sit in the middle.
The Three Assets Inside The Planned Wallets
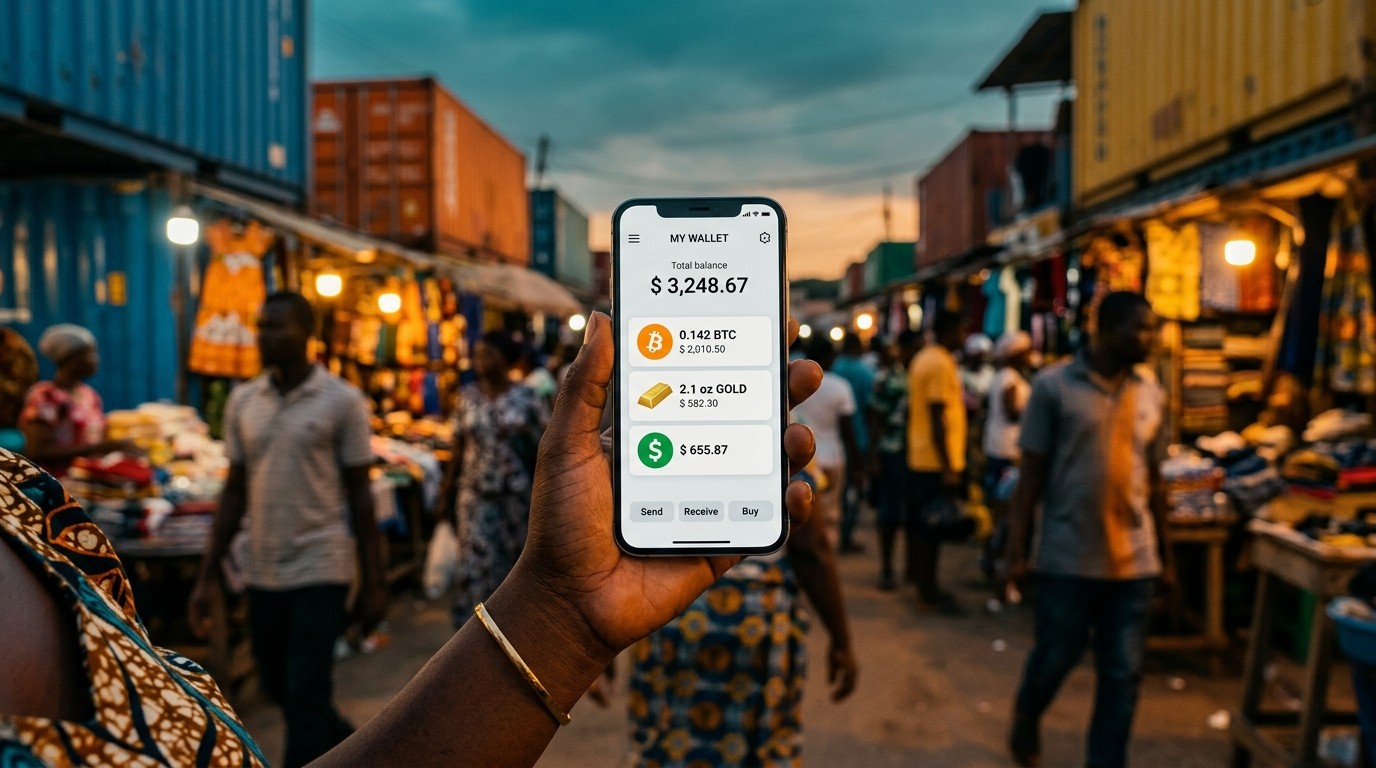
ENTA is described as a place to hold and move three things: a dollar-linked token, Bitcoin, and tokenized gold branded as XAU₮. Funding can come from local currency, U.S. dollars, or Bitcoin. Read that twice. Funding and holding are not the same list.
A customer who adds naira, cedi or dirhams is not necessarily keeping that local unit as a wallet asset. The local cash is a door. The rooms inside are dollar stablecoin, Bitcoin and gold. That design says a lot about what the builders think people want to keep after they convert.
- USD₮ as a working dollar balance for invoices, payroll and cross-border settlement
- Bitcoin as a scarce, network-native asset that does not need a corporate issuer
- XAU₮ as a gold-linked token for users who want a commodity reference instead of a pure dollar peg
I like the mix more than I like any single asset in isolation. Dollars are useful. Gold is familiar in markets where jewelry and bullion already carry social meaning. Bitcoin is the awkward cousin that does not behave like either, which is exactly why some treasurers want a sleeve of it and others want none. A product that forces all three on every user would be clumsy. A product that lets a shop, a trader and a family office pick a blend is more grown-up.
What the announcement does not do is list first countries, fee schedules or a go-live week. That absence is not a scandal. It is a reminder to treat this as intent. If you are writing a budget around ENTA today, you are guessing.
Remittance Reality Is The Quiet Pressure Behind The Pitch
Shiga has long talked about cross-border movement. That focus is not abstract. World Bank remittance pricing for the third quarter of 2025 put the average cost of sending money to Sub-Saharan Africa at 8.46 percent, the highest regional average in that dataset. You do not need a white paper to feel that number. Families feel it. Importers feel it. Freelancers feel it when a client “helps” by using the expensive option because it is the option they already know.
Neither Tether nor Shiga offered a comparable cost for ENTA transfers. I wish they had, even as a range. A wallet story without a fee story is half a story. Still, the direction of travel is obvious. If self-custodial dollar tokens can clear faster and cheaper than traditional corridors, the product does not need poetic branding. It needs reliability on a Tuesday afternoon when someone is trying to pay a supplier.
Perhaps the most interesting aspect is how ordinary that ambition sounds once you strip the jargon. People want to protect savings. People want to move money. The technology is the wrapper. The demand is older than any token.
ENTA For Individuals, High-Net-Worth Users And Firms
Shiga’s consumer-facing product is not framed as a toy for first-time app downloaders only. The language includes high-net-worth users and businesses. That is a wide net. It can also become a mess if one interface tries to serve a student sending a small transfer and a trading desk sweeping inventory at the same time.
The funding options suggest an on-ramp mindset. Local currency in, digital assets held. Dollars in, same assets held. Bitcoin in, same assets held. In other words, ENTA wants to meet people where their money already sits, then slide them into a self-custodial stack. That is harder than it looks. On-ramps live or die on banking partners, cash agents, compliance checks and the unglamorous work of reconciling broken payments.
I’ve watched plenty of “self-custody plus on-ramp” ideas stall at the last mile. The chain part works. The cash part argues with a bank. Users do not care which layer failed. They care that the balance did not move. If ENTA works, it will be because Shiga’s existing operational muscle in African business services actually touches those last miles.
There is a separate self-custodial effort in Tether’s recent history with a browser-linked wallet serving markets that include Africa, later expanded to include USD₮ and tokenized gold. I mention that only to say the company is not discovering Africa as a slogan this week. Parallel products can compete with each other. They can also segment: one lightweight, one more institutional in tone. We do not yet know which lane ENTA wants.
Pulse And The Question Of Where The Software Lives
Pulse is the institutional cousin. Banks, fintech companies and other firms would use it for corridors, treasury and settlement. Chief executive Abiola Shogbeni said the company would tailor the product to each institution instead of handing every client the same wallet skin. That is the correct instinct. A bank’s operations team does not want a consumer home screen with confetti.
Tether described two deployment paths. One: run on WDK infrastructure managed by Shiga. Two: run the software in the institution’s own environment while keeping control of keys, data and funds. The second path exists for a reason. Some clients cannot send signing systems or customer data into someone else’s cloud and call it a day. Data residency rules are not a footnote in the Gulf. They are often the deal.
- Integrate WDK once rather than stitching a new wallet stack per chain.
- Choose hosted infrastructure or a self-hosted environment.
- Map the toolkit to payment corridors, treasury desks and settlement windows.
- Keep signing authority and data location aligned with internal policy.
A single integration that can support the networks available through the kit is the kind of sentence that makes engineers nod and sales teams overpromise. Chain support is never “one and done” in the wild. Upgrades land. Fee markets change. A token contract gets paused or migrated. The kit can reduce duplicate work. It cannot abolish operations.
No bank or fintech was named as a Pulse design partner. No first corridor was named. No volume target was named. I would rather have that silence than a logo dump that falls apart in six months. Still, institutions buy proof. Shiga says ENTA will run on the same platform offered to Pulse clients, so a live consumer product could become a reference implementation. That only helps if ENTA actually goes live in a form outsiders can inspect.
Gold Tokens And A Gulf Regulatory Detail Worth Noticing
Tokenized gold is easy to market and easy to misunderstand. A token that references gold is not the same thing as a bar in your drawer. Custody of the metal, audit cadence, redemption terms and legal claims sit underneath the ticker. XAU₮ already has a specific designation in Abu Dhabi Global Market: Accepted Spot Commodity, recognized in July. That status lets firms with the right approvals offer services involving the token. It does not sprinkle automatic permission on every company in the center, and it does not bless Shiga by name.
Why mention it at all? Because the Africa–GCC corridor is not only a trade story. It is a rules story. A gold-linked token that is merely “interesting” in one jurisdiction and “accepted” in another will not travel the same way. Product teams that ignore that split end up explaining frozen features to customers who thought a token was a token everywhere.
In my view, gold is the emotional asset in this trio. Dollars are practical. Bitcoin is ideological for some and speculative for others. Gold is the thing a parent already understands. If the token keeps a tight link to the metal story people trust, it can sit beside USD₮ without feeling like a gimmick. If the link feels sloppy, users will treat it as another ticker and ignore it.
Nigeria’s Licence Is Still A Gate, Not A Trophy
Shiga’s chief operating officer, Dami Etomi, said the firm is in the final stage of approval for a Digital Asset Intermediary licence in Nigeria. If granted, that licence would cover regulated digital asset dealing, broking and custody for individuals and institutions in the country. The company has not said it already holds the licence. That sentence should stay in every recap of this news.
“Final stage” is a real place in a regulatory process. It is also a phrase that can last longer than outsiders expect. Anyone building distribution plans around a Nigerian licence should wait for the stamp, not the adjective. Etomi also said ENTA would operate on the platform shown to institutional clients. That is smart packaging. A prospect can look at a living product instead of a slide. Timing for that living product is still open.
Nigeria is not the whole map. Africa is not a single market. The GCC is not a single regulator. I keep saying that because launch language loves continents. Operations live in countries. A wallet that works in one licensing perimeter can be unusable next door without new paperwork. Self-custody does not erase that. It can even make the compliance conversation sharper, because the firm may argue it is software while the regulator asks who is facilitating the on-ramp.
What U.S. Readers Should And Should Not Infer
This plan is for Africa and the GCC. It is not a U.S. availability notice. Separate U.S. policy work has been moving around how domestic digital asset service providers may handle foreign-issued payment stablecoins. Tether and Shiga did not map ENTA or Pulse onto that draft. So American readers can study the architecture without assuming an App Store listing is next.
That boundary is useful. Too many market notes collapse every stablecoin headline into a domestic trading story. This one is about corridors, savings behavior and institutional deployment choices in regions where dollar demand and remittance friction already exist. Different movie. Same ticker on the poster.
How WDK Changes The Build Versus Buy Debate
Open-source wallet kits sound dull until you have watched a fintech spend a year reinventing address generation, fee estimation and backup flows. Dull is good. Dull ships. Tether describes WDK as infrastructure for self-custodial wallets with support for Bitcoin, USD₮ and XAU₮ among other assets. Shiga can, in theory, ride that support instead of maintaining a private zoo of chain adapters.
There is a trade. When your wallet brain lives in a shared kit, you inherit the kit’s opinions. Recovery UX, network defaults, how gold and dollars are presented side by side — those choices start to look similar across products. Differentiation then moves up the stack: on-ramps, support, licences, corridor banking, treasury workflows. That may be healthy. It may also make ENTA and other WDK-based wallets feel like cousins at a family reunion.
Rough stack to keep in mind:
  Keys and signing — user or institution
  Wallet software — WDK
  Product skin — ENTA or Pulse
  Money in — local currency, dollars, Bitcoin
  Money held — USD₮, Bitcoin, XAU₮
If that stack stays clean, users get a simple mental model. If product teams blur funding assets and holding assets in the interface, people will think the wallet “holds naira” when it does not. Language discipline is a feature. I would rather see a slightly colder onboarding screen than a pretty one that lies by implication.
The Operational Risks Nobody Puts On The Launch Graphic
Self-custody reduces a certain kind of platform risk. It does not reduce phishing. It does not reduce bad backups. It does not reduce the chance that a user sends tokens to the wrong network. Consumer education is not optional in markets where smartphone wallets may be someone’s first encounter with irreversible transfers.
Institutions face a different list. Key ceremonies. Role separation. Incident response when a signer is compromised. Reporting that satisfies both internal audit and an external supervisor. Pulse’s self-hosted option is attractive on paper precisely because those teams want the blast radius inside their own walls. Attractive is not automatic. Running wallet software well is a discipline, not a checkbox.
Then there is liquidity. A wallet that can display gold and dollars is not the same as a wallet that can exit both at a fair price at 11 p.m. on a public holiday. OTC relationships, market makers and banking hours still decide whether a “treasury tool” is real. Shiga’s older service list included OTC and FX. That background is more important than the new brand names.
| Layer | What users notice | What can still break |
| Self-custody | Control of keys | Lost seed, device theft, phishing |
| On-ramp | Local cash becomes tokens | Bank delays, limits, rejected transfers |
| Assets | Dollars, Bitcoin, gold | Peg stress, liquidity gaps, redemption rules |
| Corridors | Money arriving across borders | Licences, banking partners, holidays |
Why Africa And The GCC In The Same Sentence
Trade, remittances, energy payments, contracting and family networks already bind parts of Africa to Gulf financial centers. Dollar settlement shows up in those flows even when neither side is American. A wallet story that names both regions is trying to sit on existing economic gravity rather than invent a corridor from a conference stage.
That said, “Africa and the GCC” is still a slogan until someone names a first pair of cities, a first banking hours window, and a first compliance packet. I would love a boring appendix: Lagos to Dubai, Accra to Abu Dhabi, Johannesburg to Doha — pick one and show the steps. Until then, treat the corridor as an ambition with a plausible map, not a live timetable.
Currency stress in several African economies also changes the psychology of a dollar token. People do not need a lecture on inflation to want a unit that holds still. The risk is overselling stillness. Stablecoins can wobble. Banking partners can freeze. Gold tokens can trade off the metal story during a panic. A responsible product talks about those tails before a marketing site fills with palm trees and skyline shots.
What Success Would Actually Look Like In Twelve Months
Forget download counts for a moment. I would watch five things, none of them glamorous.
- Whether the Nigerian intermediary licence lands and what activities it truly covers
- Whether ENTA publishes a country list and a fee card instead of atmosphere
- Whether a named institution deploys Pulse in hosted or self-hosted form
- Whether gold and dollar balances can be exited without ugly spreads in size
- Whether support quality matches the seriousness of irreversible transfers
If those boxes start turning green, the partnership becomes more than a press cycle. If they stay foggy, we will have another well-written announcement and a quiet product. Crypto is full of those. I would rather be pleasantly bored by execution than entertained by adjectives.
There is also a softer metric: do small businesses treat the wallet as a treasury drawer or as a speculative toy? The first outcome is the one the quotes keep pointing at. The second is what happens when incentives tilt toward trading. Product design will leak that preference. Watch whether the home screen leads with send, hold and invoice — or with charts.
A Practical Way To Read The Fine Print Mentally
When a company says “self-custodial,” ask who can freeze an on-ramp. When it says “local currency funding,” ask which agents and which banks. When it says “institutions can self-host,” ask who patches the software. When it says “gold,” ask how redemption works on a bad day. These questions are not hostility. They are how you stay a customer instead of a case study.
Control of keys is only half of financial control. The other half is the right to leave at a fair price without begging a ticket queue.
That is my own line, and I will stand on it. Self-custody without an exit is a display case. Payments without custody options can become a trap. The Tether–Shiga plan is interesting because it tries to hold both ideas in one kit. The next year will show whether the kit is a foundation or a brochure.
Where This Fits In A Crowded Wallet Market
The world does not have a shortage of wallet icons. It has a shortage of wallets that survive contact with cash agents, auditors and family group chats. Distribution in Africa and the Gulf is not won by a prettier seed phrase screen. It is won by people who already move money for businesses and can bolt self-custody onto that habit.
That is why the 2025 investment context matters. Shiga was not introduced as a blank consumer brand. It was introduced as a firm already in the unglamorous stack: accounts, FX, treasury, OTC. WDK is the new chassis. The driver is still supposed to know the roads. If that combination holds, ENTA and Pulse can be more than siblings of a dozen other multi-asset apps. If it does not, we will file this under toolkit announcements and move on.
I keep coming back to a small editorial instinct. The strongest part of the news is not the brand pairing. It is the refusal, at least on paper, to make custody the default. Users in these markets have been asked to trust too many intermediaries with savings that already face inflation, delays and fees. Giving them a path to hold dollars, Bitcoin and gold under their own keys is a serious promise. Serious promises deserve serious follow-through.
The Unfinished Sentence At The End Of The Announcement
So here we are. Two products. One kit. Three assets. Two regions. A licence still under review. No public fee card. No named bank on Pulse. No launch morning circled in red. That is not a reason to dismiss the plan. It is a reason to keep the tab open and wait for operations to speak.
If you live in the target markets, the useful move is unromantic. Watch the licence docket. Watch which assets you can actually buy and sell in size. Watch whether customer support answers when a transfer fails. If you are an institution, ask for the self-hosted architecture diagram before you fall in love with the corridor map. If you are just trying to understand the news, remember the core swap being offered: less platform custody, more user control, same old human need to keep value still and send it far.
Will ENTA feel like a bank app with better assets, or like a true key-holding tool that still lets you fund from the cash you already have? That is the suspense the announcement left hanging. I want the second version. I will believe it when the first ordinary user can fund, hold and send without needing a press release to explain what just happened.