
I keep coming back to the same question when a session starts ugly and then quietly repairs itself: is this real risk-taking, or just traders refusing to stay short into a data-heavy week? This morning has that feel. US equity futures shook off earlier losses and drifted into the green, close to session highs, after crude oil slipped and dragged bond yields lower with it. The dollar eased a touch as well. There was no single blockbuster headline that settled the geopolitical file. Instead, the tape did what it often does when energy cools: it exhaled.
Why Futures Flipped After Oil Lost Its Grip
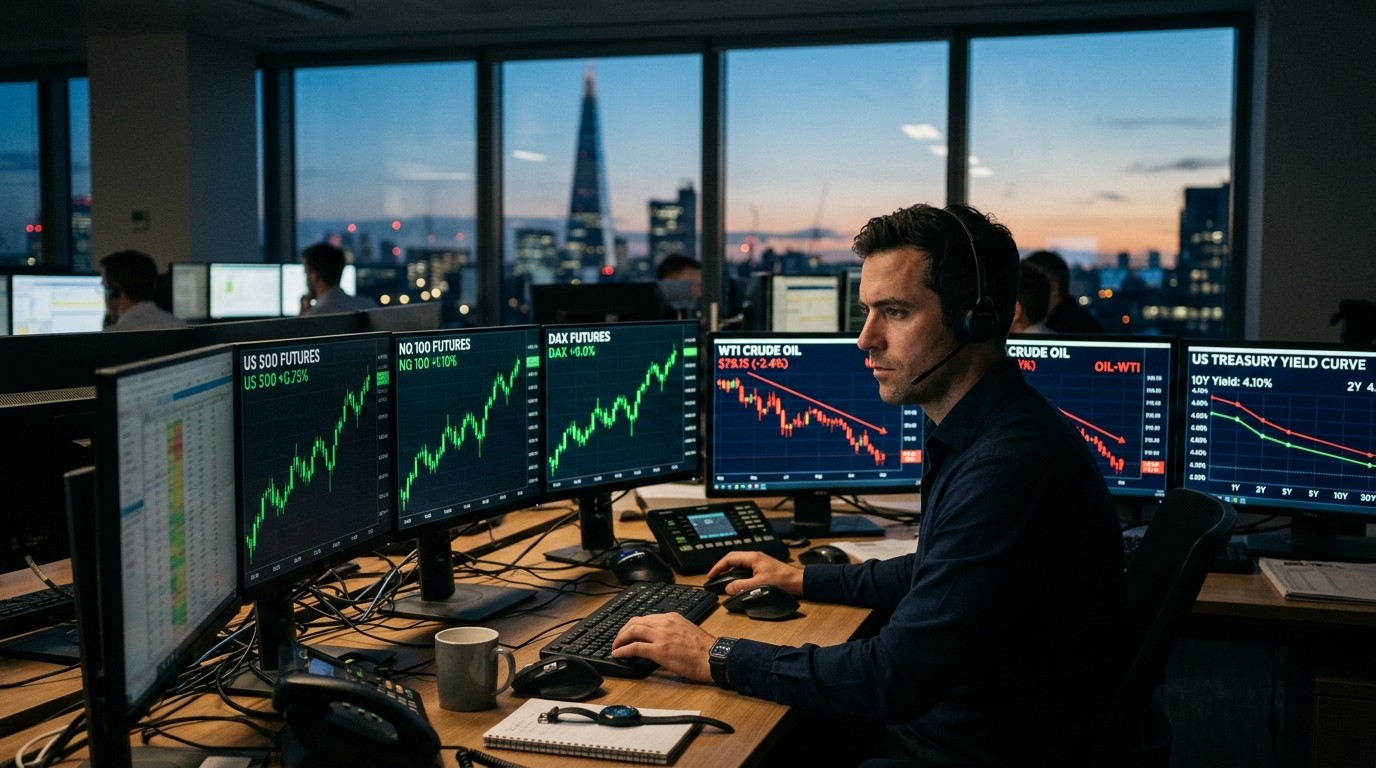
By mid-morning in New York, S&P futures were up about two tenths of a percent and Nasdaq futures were firmer still, nearer four tenths. The usual growth names found a bid. Semiconductors and memory names participated. Software lagged. That split matters. It tells you the market is still treating the AI complex as the engine and treating a lot of traditional software as the caboose. European chip names were even hotter, up more than three percent in places, which often previews a livelier open on this side of the Atlantic.
Energy stocks did the opposite of the index. They followed crude lower. That is the cleanest tell in the whole session. When oil drops two percent and sits on the lows, the inflation impulse in the front of the curve loses some of its heat. Rates follow. Equities, especially duration-sensitive growth names, get room to breathe. I’ve found that this chain reaction is more reliable than any speech about “soft landings.” Price first. Narrative later.
Gold held a modest bid while much of the broader commodity complex looked heavy. A few agricultural contracts firmed. Bitcoin ticked higher by half a percent. None of that screams panic. It looks like a market that wants to re-risk, but only with one hand on the exit.
The Oil Move That Reset The Whole Tape
Crude sat at session lows, down roughly two percent, after reports that a key Saudi pipeline had resumed flows and after comments from Qatari officials about possible diplomatic paths. Traders have heard versions of this story before. That is why the bounce in risk assets still feels guarded. Hope is allowed. Conviction is rationed.
Brent had been knocking on higher levels earlier in the European morning before fading toward the mid-100s. WTI followed the same arc. There was no neat official communique that closed the Strait file. There rarely is. The market simply decided that the immediate supply scare had peaked for a few hours. In my experience, those hours can be enough to squeeze crowded oil longs and force a rethink in rates.
Overall price action looks like cautious re-risking with guarded optimism around a possible easing of energy stress.
That sentence is the whole mood. Not a victory lap. A pause in the selling. If oil snaps higher again on the next contradictory statement, this green open can vanish before lunch. Anyone pretending otherwise has not watched this tape for the last several weeks.
What Premarket Stock Moves Are Really Saying
The mega-cap group was mixed rather than euphoric. One search giant was slightly red. A large online retailer was modestly green. A phone maker slipped. A social platform firmed. A software giant was basically flat. A leading chip designer rose. An electric-vehicle name edged higher. That is not a stampede. That is rotation inside a crowded club.
Away from the household names, the tape was messier and more interesting. An aerospace supplier jumped after beating first-quarter earnings and revenue estimates. A credit-score company plunged after policy comments that could make it easier for lenders to adopt a rival scoring model. Analysts immediately framed that as a hit to pricing power and market share. When a name drops eighteen percent before the open, you do not need a novel thesis. Competition just walked into the room.
A fuel-cell maker rose after a brokerage initiated coverage with an upbeat view and argued that demand could stay ahead of supply as capacity ramps. A biotech lifted guidance and climbed. A software name slipped after a downgrade that pointed to slower annual recurring revenue growth. A streaming company ticked higher after an upgrade arguing that engagement worries were overdone. Another biotech jumped on a large collaboration investment from a major drugmaker. A gene-therapy name collapsed after longer-term trial data looked less impressive than the three-year readout. That last one is a reminder that small-sample medical stories can reprice in a single filing.
- Beats and guidance raises still get paid, even on a geopolitically noisy morning.
- Policy risk can hit a monopolistic franchise faster than a weak quarter.
- Trial updates with fading durability can erase years of optionality in minutes.
- Downgrades tied to growth durability matter more than noise about a single print.
Corporate headlines also included a multi-billion investment into a US biotech to work on a cancer program, a large agreed purchase of an AI startup by a major chip designer, and a ski-resort operator talking about a rebound year if weather cooperates and costs stay contained. Different industries. Same message. Specific news still moves single names more than the index-level geopolitics, at least until oil decides otherwise.
Labor Data, Fed Voices, And A Tricky Calendar
Today’s domestic calendar is not decorative. Job openings, consumer confidence, house-price gauges, and a regional services survey all land before the weekend payrolls report. Six policy officials are scheduled to speak. Two of them are closely watched voters. One has recently argued for additional tightening. Another has said more work is needed on inflation. That is a lot of live microphones for a market that has already been pricing a hawkish path.
Perhaps the most interesting aspect is the contrast between the tape’s short-term relief and the rate path still embedded in futures. Traders have, at times this week, priced a meaningful chance of further hikes over the coming year. Oil going down for a morning does not delete that. It only buys time. If openings stay firm and wages refuse to cool, the bond market can reassert itself quickly.
A senior macro strategist put it in plain language: after large moves, and with payrolls still ahead, it makes sense for books to be squared. Month-end flows add another layer. Passive rebalancing does not care about your thesis. It just trades the calendar. I’ve sat through enough month-ends to treat that as operational fact, not color commentary.
The AI Narrative Is Getting Harder To Trade
For months the easy trade was “more compute, higher multiple.” That still works on many days. It is just no longer automatic. One leading lab delayed a model debut while it built stronger safeguards. Another warned, in offering documents, about severe long-term risks. Executives are heading into conversations with policymakers about safety. A developer conference is on the calendar. The chief executive of a major chatbot firm will have a public microphone. Markets love a keynote. They do not always love the fine print that follows.
Industrials and utilities have started to piggyback the theme because power, cooling, and grid buildout sit underneath the model race. That is rational. It is also how themes get crowded. When cyclicals lead defensives and staples sag, you are watching that crowding in real time. Energy is the exception today because crude is the exception today.
Is the AI trade broken? No. Is it simple? Also no. Open-ended capex stories eventually collide with financing costs, power constraints, and political scrutiny. You can believe the long-term demand case and still admit the path is getting bumpier. I do both.
Flows Hint That Investors Are Less Aggressive
Long-term net asset inflows into US funds cooled last month versus July. Passive money did more of the slowing. Equity inflows dropped from a much larger July figure to a slimmer print. That does not mean households fled stocks. It means the firehose is not running at the same pressure. After a stretch of oil shocks and yield spikes, some allocators simply wait. Waiting is a position.
Credit markets already showed the strain earlier in the week. Investment-grade and high-yield spreads had widened toward levels last seen in the spring. When oil jumps and real yields jump with it, leveraged balance sheets feel it first. Today’s friendlier rates tape is a balm. It is not a cure if crude re-accelerates.
Europe Caught A Bid From Cheaper Crude
The regional benchmark was higher, with cyclicals beating defensives. Lower oil helps the inflation math and trims some of the hawkish edge around the European Central Bank. A Swiss wealth manager surged after a regulator ended an enforcement process and set an extra capital requirement that was less onerous than feared. The firm also sought approval for a buyback. Markets love a clean ending almost as much as they love a beat.
Other European movers told a more ordinary corporate story. A metals-engineering firm jumped on a cash-and-shares bid. A specialist lender rose after earnings and costs beat expectations and loan growth improved in the second half. A container line lifted full-year guidance while freight rates stayed elevated. A listings platform outlined product changes. A discount retailer accelerated like-for-like sales, raised guidance, and announced a buyback. An electrical-equipment group updated long-term targets at a capital markets day and ripped higher.
Not everything worked. A chocolate group cut its organic sales-growth outlook and the participation certificates were hit hard. A pest-control name faded after a downgrade arguing the US story may have peaked. Transport-infrastructure operators dropped on talk of higher taxes in a future budget. A turbocharger maker fell after a brokerage started coverage with a skeptical rating. A biotech slid after an abrupt chief-executive departure. Different countries, same market logic: guidance and policy still dominate single-stock tape when the index is only modestly green.
Asia Had A Harder Night
Regional stocks were headed for a second down session for much of the day as the Hormuz file refused to produce a clean deal and oil stayed elevated into the Asian close. Financials tracked weaker US peers. A large Taiwanese chip-design name slid after a sharp run-up. Most local benchmarks finished lower. Mainland China was the relative exception, ending little changed, while property names bounced after officials said they would study measures to stabilize housing, support jobs, and lift demand. That is not a finished rescue package. It is a signal that policymakers see the bruise.
Notable Asian single names ran the usual range from licensing wins to debut slumps. A drugmaker rose after licensing an obesity and diabetes candidate in a deal that could be worth billions. A new listing in Hong Kong fell on day one. A Japanese drugmaker dropped after discontinuing an obesity program. An Indonesian platform name extended a brutal decline after an exchange removed a price floor. An automaker jumped on plans to take a stake in a joint venture through share issuance. A biotech linked to a partner of a large collaboration target rallied. A humanoid-robot name fell after a downgrade.
Zoom out and the regional benchmark is still down on the month even after a strong year-to-date run. Oil, yields, AI volatility, and a more hawkish US rate path have all taken turns souring the mood. India has had a particularly rough stretch, with the main index breaking long-held supports after weeks of declines and slipping through its weekly 200-day average for the first time in years. Darling markets can become crowded markets. Crowded markets can become unforgiving markets.
Currencies And Bonds Followed The Energy Cue
The dollar index was firmer for much of the session even as yields later eased, which is a slightly awkward combination if you like tidy narratives. The euro drifted toward the lower end of its recent range. The Australian dollar sat near the bottom of the G10 board after a hike that markets expected, followed by a governor who sounded less eager to promise the next one. That combination is familiar: hike the rate, then try not to panic the housing market.
Treasury futures recovered after an early dip. The ten-year yield slipped a couple of basis points toward the low-5.2 percent area. Two-year through ten-year yields were richer by a similar amount, with the long end lagging a touch and the five-to-thirty curve steepening modestly. Bunds and gilts outperformed in the sector. UK paper caught a bid as traders waited on political remarks that could open a conversation about pension-indexation reform. Fiscal stories move duration. They always have.
Primary issuance stayed selective. One grocer had raised a sizable package the prior day. Others stood down. Another media name was expected to come with a dollar tranche after investor meetings. When yields are near multi-year highs, corporate treasurers do not always feel the urge to test the window. That restraint is itself information.
| Market sleeve | Morning tone | Main driver |
| US equity futures | Modestly higher | Lower oil and yields |
| Crude oil | Session lows | Pipeline flows and diplomacy talk |
| Treasuries | Richer across the curve | Softer inflation impulse from energy |
| Dollar | Still bid | Rate-path premium and residual caution |
| Gold | Mild bid | Dip-buying after recent pressure |
What The Geopolitical File Is Actually Doing To Prices
The Strait remains the hinge. Officials on one side talk about proposals, mediators, and conditions set at the top. Officials on the other side deny reports of generous offers. Local lawmakers insist no talks start until prior commitments are met. Shipping incidents and proxy attacks keep the risk premium from fully collapsing. Pipeline repairs and higher regional loadings keep the supply side from looking entirely broken. The market is being asked to price two stories at once. No wonder the range is violent.
Some analysis has argued that the leverage of a full choke point is less complete than it looked a few months ago, which could, paradoxically, raise the odds of other forms of pressure. I do not need to dress that up. Traders already understand the point. If a tactic stops working, actors look for another. That is why a two-percent oil drop does not automatically become a durable downtrend.
Exports from key producers rebounded last month to the strongest pace since the latest regional conflict intensified, helped by higher loadings from large Gulf suppliers. That is the other side of the ledger. Physical barrels still move. Futures still overshoot. The gap between those two facts is where a lot of money has been made and lost this year.
Inflation Abroad Is Not Helping The Dovish Case
Australia raised its policy rate to the highest level in about fifteen years. Fuel prices were part of the story. Capacity pressures were the rest. The statement left the door open to more if needed. Then the governor sounded more hopeful that the tightening already delivered might prove enough if inflation rolls over. Markets sold the currency anyway. Communication gaps do that.
Spanish inflation printed hotter again and stayed above the euro-area target. An economy that outperforms can import the same energy shock and turn it into stickier services inflation. That is not a European sideshow. It is a reminder that the global rate cycle is not neatly synchronized, even when every central banker is staring at the same crude chart.
Japan offered a small counterweight. A long-dated government-bond auction drew the strongest demand in years as elevated yields finally pulled buyers back. Fragile global markets will take any bid they can get in duration. Whether that bid survives the next oil spike is a different question.
How To Think About Positioning Without Overfitting The Morning
There is a temptation to treat a green open as proof that the worst is over. I would not. The better framing is tactical. Lower oil reduces the near-term inflation impulse. Lower yields help growth multiples. Mega-cap and semiconductor leadership can persist if the AI capex story stays intact. Energy equities and some cyclicals tied to fuel costs will lag on days like this. Staples can look dull when investors want beta again.
- Respect the oil-yield-equity transmission. It is still the dominant intra-day machine.
- Do not confuse a diplomacy headline with a settled supply regime.
- Watch labor data for confirmation that the economy can absorb higher rates.
- Treat month-end and pre-payrolls flows as noise that can still move your marks.
- Keep single-name risk sized for gap moves. Policy and trial updates are not gentle.
None of that is heroic. It is just how you stay solvent when the same three variables — crude, the ten-year, and the next jobs print — keep stealing the show.
The Session’s Quiet Tells
Software weakness next to semiconductor strength is one tell. Cyclicals leading defensives is another. Gold’s modest bid while oil falls is a third. The dollar staying relatively firm even as yields dip is a fourth. Put together, they describe a market that wants risk but has not abandoned the hedge. That is healthier than a melt-up on thin news. It is also easier to reverse.
House-price data and consumer confidence will not settle the strategic debate. They can still nudge the short-term rate narrative. Job openings that cool would support the idea that labor demand is no longer red hot. Openings that re-accelerate would feed the camp that says the economy can take more restriction. Six speakers give both camps ammunition. Selective quoting will be intense. It always is.
On the corporate side, the morning already showed that idiosyncratic risk has not taken a holiday. A credit-score franchise can lose a fifth of its value on a policy remark. A gene-therapy name can lose more than half on a durability update. Collaboration checks can add double-digit percentages to a partner. If you only watch the index future, you miss the market’s real personality.
A Longer View Than The First Hour
September has a reputation for being unkind to Treasuries. History is not a trading system, but it is a warning label. Fiscal concerns, a still-hawkish policy path, and an unresolved energy shock are not the ingredients of a gentle duration rally. Today’s two-basis-point dip is welcome. It does not rewrite the month.
Equities face a similar tension. The year-to-date gains in several Asian and global benchmarks remain impressive. The last few weeks have been about whether those gains can survive a world where oil stays structurally higher and real yields stay uncomfortably high. This morning’s answer is a shrug: maybe, if crude keeps fading. That is a thin foundation. Thin foundations can still hold for a while. They just do not invite leverage.
I keep a simple mental model on days like this. Energy is the inflation dial. The inflation dial sets the rate path. The rate path sets the multiple. The multiple sets how far the AI story can run without a funding scare. Everything else — a beat here, a downgrade there, a political speech at a party conference — is texture. Texture moves stocks. The dial moves the market.
We’ve had some rather large moves over the last few days, and the ultimate data trigger is still ahead. Squaring risk into that window is not cowardice. It is arithmetic.
That is the adult version of “wait and see.” It does not mean going to cash and staring at the wall. It means smaller bets, cleaner hedges, and less attachment to yesterday’s narrative. If diplomacy unexpectedly delivers a durable reopening path, oil can fall further and this rebound can grow up. If the next statement lands like a slammed door, the green ticks were just a squeeze.
What I’ll Be Watching Into The Close
First, whether crude holds the lows or stages the familiar afternoon revival. Second, whether the ten-year can stay below the recent highs instead of tagging them again into the data. Third, whether semiconductor leadership survives if the broader tape fades. Fourth, whether credit spreads stop widening now that yields have eased. Fifth, the tone from policy speakers. One hawkish adjective at the wrong moment can undo a two-tenths rally without breaking a sweat.
There is also the developer-conference circuit and the policy lunch on AI risk. Those events are not traditional macro catalysts, yet they sit on top of the most crowded equity theme on earth. A cautious keynote can be spun as maturity. A messy one can be spun as delay. Markets will choose the spin that fits the existing position. That is not cynicism. That is how crowded trades digest news.
For households and longer-horizon investors, the lesson is less dramatic than the futures pit makes it look. A morning rebound after an oil drop does not change a savings plan. It does change the near-term inflation path if it persists. Energy in the grocery basket and in the freight bill is still the political and economic nerve. When that nerve quiets, risk assets usually remember how to climb. When it twitches, they remember how to fall.
So where does that leave the open? Futures are up. Oil is down. Yields are softer. The dollar is not collapsing. Mega-caps are mixed. Semis are bid. Energy stocks are heavy. Labor data is next. Payrolls are still the weekend boss fight. If that sounds unfinished, good. Unfinished is the honest description of this market. Anyone selling certainty this morning is selling something the tape has not paid for yet.