

Trump Denies Iran Sanctions Relief As Oil Prices Climb

Trump says he offered Iran nothing, yet oil still jumped and Qatar kept the back channel open. The next move on Hormuz may decide whether this rally fades or hardens.
Financial market analysis from 30/09/2026. Market conditions may have changed since publication.
Have you ever watched a market twitch because one late-night post landed before the coffee even finished brewing? That is how Wednesday started. Crude ticked higher after a blunt denial about Iran, and traders who thought they had the script figured out had to rip the page and start again. I have covered energy long enough to know this pattern. A headline hits. Someone shouts it is fake. Prices still move. Then the quiet work of mediation continues in another capital while the rest of us stare at the screen.
Why The Denial Hit Oil Before Diplomacy Did
The story was simple on the surface and messy underneath. Reports suggested Washington might ease pressure on Tehran in return for visible steps on the nuclear file. The president rejected that idea in public language that left almost no room for nuance. He said he offered them nothing. He called the report a hoax. Markets, being markets, did not wait for a legal memo. They priced the chance that sanctions stay tight and that the path through the waterway everyone cares about stays uncertain.
Brent, the global marker most cargo desks still treat as gospel, was changing hands near $103.09 a barrel in the early hours. That was a modest lift, not a panic spike. West Texas Intermediate sat close to $89.53. Those numbers look tidy. The feeling behind them was not. A few cents can hide a lot of nervous inventory managers who do not want to be short if a strait becomes a talking point again.
This is untrue. I offered them nothing.
That line matters because energy traders do not trade feelings. They trade optionality. If relief is off the table, the option set shrinks. If relief was never really on the table, then the earlier rumor was just noise. Either way, the tape responded first and asked questions later. In my experience, that is when the real work begins: separating a political performance from the logistics that actually move barrels.
The Waterway That Still Sets The Mood
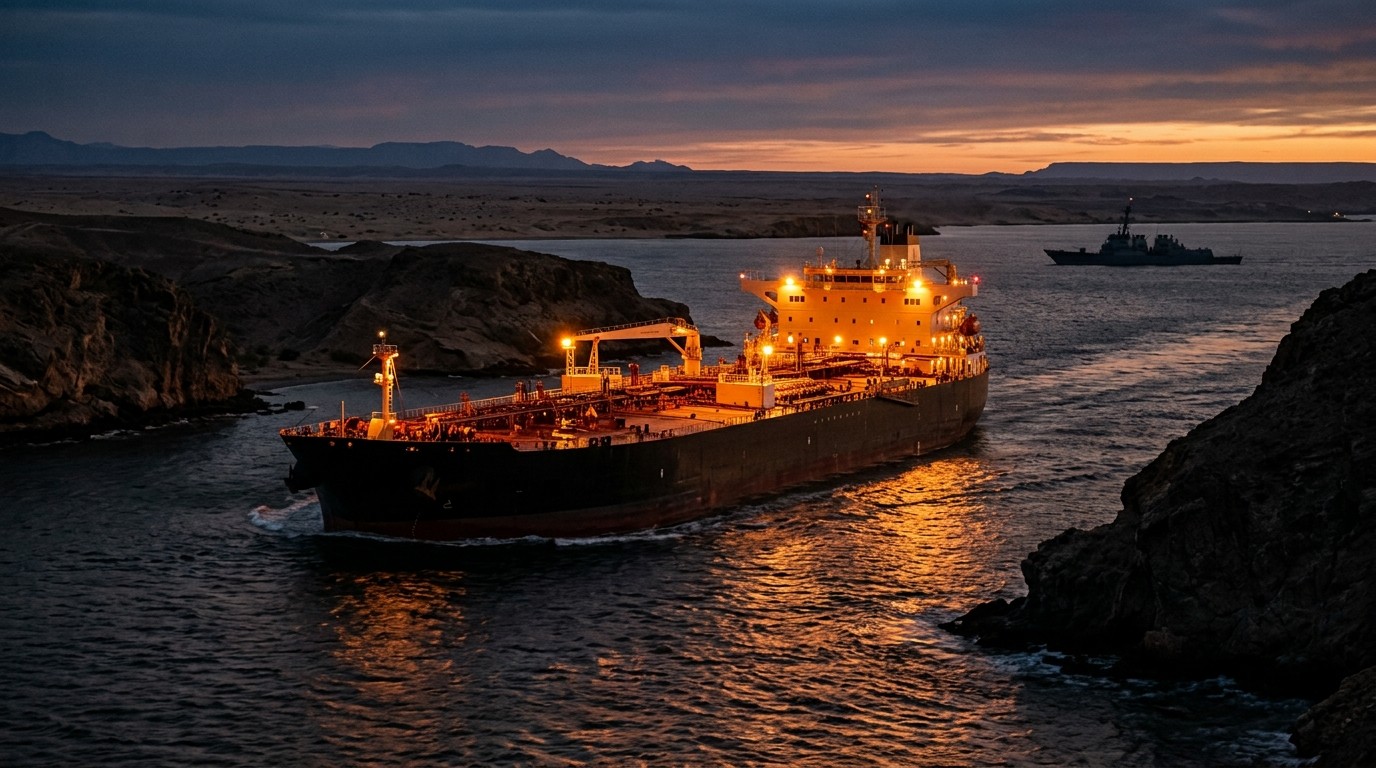
Everyone in this business can recite the same geography lesson. A thin stretch of water carries a huge share of seaborne oil. When that stretch is calm, markets yawn. When someone even mentions a plan to reopen it after tension, desks sit up. Iran put forward a short timetable aimed at unlocking traffic. Qatari mediators passed messages both ways. Tehran’s foreign minister sat with those mediators late Tuesday and was due to take the American response home on Wednesday.
That sequence is the part I find more interesting than the social post. Posts are loud. Mediation is dull until it is not. A seven-day plan sounds neat in a briefing. In practice it is a chain of inspections, insurance clauses, naval posture, and the private fear of a ship owner who has to sign a voyage. I have found that markets respect the dull chain more than the slogan, even when the slogan moves the first print.
Qatar’s public line was careful. Officials said they were still exchanging messages and looking for common ground so a wider clash does not dictate the next quarter for everyone who buys fuel. That is the grown-up version of the story. It does not trend as fast as a denial. It still decides whether tankers keep a normal schedule or start adding war-risk premia that show up in your heating bill six weeks later.
What The Early Price Move Actually Said
A half-percent bounce in Brent is not a crisis. Treat it like a raised eyebrow. The market heard two things at once. First, official Washington does not want to be seen handing Tehran a gift. Second, the diplomatic channel is still open enough that a foreign minister is flying home with notes. Those two facts can live in the same hour. Traders hate that. They prefer a clean binary. Life in the Gulf is rarely binary.
Look at the two benchmarks side by side and you see a familiar split. The international grade reacted a bit more than the U.S. grade. That is not mysterious. More of the world’s seaborne risk sits in the international complex. American shale does not vanish if a strait gets jumpy, though American refiners still feel the global complex through product cracks and import math. I still watch the spread when headlines get theatrical. Spreads tell you who is sweating.
| Benchmark | Early Level | Move | What It Hinted |
| Brent | $103.09 | +0.49% | Global supply nerves |
| WTI | $89.53 | +0.18% | Milder domestic reaction |
| Policy signal | Public denial | Sharp tone | Relief not framed as a gift |
| Diplomacy | Doha channel | Still active | Talks not abandoned |
Numbers that small can still change inventory strategy. A refiners’ buyer who was comfortable running light inventories may add a cargo just to sleep. A hedge fund that faded geopolitical risk last week may cover a sliver. None of that makes a magazine cover. It does keep the bid alive into the London morning.
Sanctions, Frozen Funds, And The Politics Of “Nothing”
Sanctions relief is a phrase that sounds technical until you remember what it includes. Access to money. Easier shipping insurance. Banks willing to clear a payment without a three-week compliance seminar. Release of frozen balances. Those are not abstract. They are the difference between a state that can sell oil quietly and a state that has to invent workarounds.
The reported bargain was classic: concrete nuclear steps in exchange for economic breathing room. The public rejection was also classic. Leaders rarely advertise a concession while talks are live. Sometimes the denial is theater for a domestic audience. Sometimes it is the actual position. Markets cannot audit the difference in real time, so they add a risk premium and wait for deeds.
I am skeptical of anyone who treats a single post as a finished policy. I am equally skeptical of anyone who treats a leak as a signed term sheet. The honest middle is uncomfortable. Washington can refuse to brand a package as a gift and still pass messages through a Gulf capital. Tehran can demand respect and still listen to a timetable that gets tankers moving. That is how these files often work when nobody wants a shooting match and nobody wants to look weak.
Qatar’s Quiet Job Between Two Hard Lines
Mediation is thankless. You host the meeting. You carry the paper. You get blamed if it fails and barely noticed if it works. Qatar has played that role before in regional files that mix energy, security, and pride. The spokesperson’s language was almost deliberately boring, which I take as a good sign. Boring is how you keep a channel alive.
We’re working towards establishing a common ground in order to get into a deal that would save all of us from the repercussions of the conflict.
Read that twice. It is not a victory speech. It is a warning wrapped in courtesy. Repercussions are the part that hits freight rates, insurance, and the price of diesel in places that never think about the Gulf until the pump changes. A mediator talking about “all of us” is reminding both capitals that the audience is bigger than the two governments in the room.
Iran’s envoy receiving feedback and then returning home is a process detail, not a climax. Process details are where deals live or die. If the feedback was a hard no on money and a soft yes on traffic management, that is one path. If it was a demand for nuclear steps first and economics later, that is another. We do not have the memo. We have the price of oil and a schedule of meetings. That is often all the market gets.
How Traders Translate A Denial Into A Position
There is a practical checklist that shows up on desks when this kind of story prints. It is not elegant. It works.
- Check whether the denial kills the rumor or just rebrands it.
- Watch freight and insurance chatter even if official prices barely move.
- Compare Brent and WTI instead of staring at one screen.
- Ask if inventories were already tight before the headline.
- Leave room for a second move when the foreign minister speaks at home.
That last point is the one amateurs skip. The first print is a reflex. The second print is a judgment. If Tehran’s readout sounds furious, you can get another bid. If it sounds procedural, the bounce can fade by the New York open. I have lost count of how many “geopolitical spikes” melted because the follow-up briefing was yawn-worthy. I have also seen the opposite, when a calm morning turned ugly after a press line in the wrong capital.
Position sizing matters more than bravado here. A tiny long in crude because the waterway is in the news is not the same as betting the farm on a blockade that has not happened. Perhaps the most interesting aspect is how quickly some accounts treat a denial as proof that risk is gone. That is sloppy. A denial can raise risk if it means talks lose cover. It can lower risk if it means nobody is about to hand over cash without terms. You need the next data point.
Nuclear Steps Versus Barrel Steps
People mix two clocks. The nuclear clock is inspections, enrichment, and political theater that can last years. The barrel clock is voyage days, storage, and refinery runs that live in weeks. A plan to reopen a strait in seven days belongs to the barrel clock. Sanctions architecture belongs to both. That mismatch is why a president can say “nothing” and a mediator can still talk about traffic.
Concrete steps on a nuclear file are hard to fake in public. Ships moving through a strait are easy to count. That is why energy markets sometimes look past the grand bargain and obsess over whether a lane is open at dawn. I prefer that obsession. It is measurable. You can argue about intent forever. You cannot argue with a tanker that did not sail.
Still, do not pretend the nuclear file is decoration. If talks stall there, economic pressure stays. If pressure stays, export workarounds get riskier and buyers get pickier. Pickier buyers mean discounts, delayed cargoes, and occasional surprise barrels hitting unexpected ports. The paper market hates surprise barrels almost as much as it hates missing barrels. Both wreck a tidy model.
What Households And Companies Should Notice
This is not only a trader story. Airlines watch jet fuel. Trucking firms watch diesel. Emerging-market importers watch the dollar cost of a cargo. A small rise in the international marker can look academic until it shows up in a monthly fuel surcharge. I have found that companies that wait for a “real crisis” to hedge are the ones writing the painful emails later.
- Map how much of your cost base is tied to seaborne crude or products.
- Ask your supplier if war-risk language has changed even slightly.
- Do not treat a one-day bounce as a new price regime.
- Do treat a live mediation as a reason to keep options open.
- Write down your pain level before the next headline, not after.
That last item sounds like a motivational poster. It is bookkeeping. If $110 Brent ruins your quarter, you should know that on a quiet Tuesday. Waiting until a denial hits social media is how amateurs manage risk. Professionals look bored on purpose.
The Temptation To Overread One Night
Every cycle produces the same bad habit. One report. One rejection. One chart. Suddenly the internet is full of people who know exactly what happens next. They do not. Neither do I. I can tell you what the first reaction implied. I cannot tell you whether a back channel produces a traffic arrangement by the weekend. Anyone who claims they can is selling certainty, not analysis.
There is also a habit of treating every Gulf headline as 1973 in miniature. History rhymes. It does not copy and paste. Today’s market has more U.S. supply, more strategic stocks in some places, more financial players, and a public that sees prices on a phone before officials finish a sentence. That mix can mute a shock or amplify a rumor. It rarely behaves like a textbook.
So yes, oil climbed. Yes, the denial was loud. Yes, Qatar kept talking. Hold those three facts without forcing them into a single moral. The useful question is narrower. Does the next official statement make insurance cheaper or dearer? That is the tell.
Scenarios Worth Keeping On One Page
I like simple trees when the news is noisy. Not because they are complete. Because they stop you from inventing a novel.
- Talks stall, tone stays hard: risk premium lingers, dips get bought faster than usual.
- Traffic plan works, politics stay ugly: physical market calms first, paper market argues later.
- Unexpected concession appears after the denial: prices can drop quicker than pride allows anyone to admit.
- Incident at sea, even a small one: the debate about who offered what becomes a footnote.
Notice what is missing. A neat ending. These files do not do neat endings. They do sequences. Sequence is the job.
A Personal Read On The Tone
If I am honest, the wording of the denial felt aimed at a domestic room more than a trading floor. That does not make it fake. It makes it layered. Leaders talk to several audiences at once. Markets hear the volume and miss the layering. I have made that mistake. You hear “nothing” and assume the channel is dead. Then a minister lands in Doha and you realize the channel was never the press conference.
The other layer is pride. Sanctions relief framed as a reward is politically expensive. The same package framed as a temporary technical step to keep oil flowing can be easier to swallow. Watch the adjectives. Reward language kills deals. Technical language keeps them breathing. Qatar’s spokespeople tend to live in technical language. That is not an accident.
Do I think a grand bargain arrives this week? No. Do I think a limited understanding about traffic is possible while everyone denies a grand bargain? Yes. That is the unromantic forecast. Unromantic forecasts keep people employed.
What To Watch After The First Bounce
The useful watchlist is short and a little unglamorous.
- Any official readout from Tehran after the envoy returns.
- Insurance quotes on voyages that actually need the strait.
- Whether product cracks follow crude or ignore it.
- Language from other producers who like higher prices but not chaos.
- Whether the next American comment is shorter, softer, or louder.
If insurance stays sleepy, the oil bounce was mostly headline oxygen. If insurance wakes up, the chart was early, not wrong. I would rather be early and humble than late and certain.
Why This Episode Still Matters Even If Prices Fade
Some stories matter because of the print. This one matters because of the plumbing. A public denial plus a private channel is the operating system of modern energy diplomacy. You will see it again. Different names. Same shape. If you learn to read the shape, you stop treating every post as a regime change in the oil market.
There is a human piece too. Ship crews do not trade futures. They sail. Mediators do not post victory videos when a meeting merely fails to collapse. Officials who deny a rumor may still need a deal that keeps lights on in cities far from the argument. I try to keep that in view when the commentary gets swaggering. Swagger is cheap. Freight is not.
So where does that leave a reader who just wanted to know why crude ticked up before breakfast? It ticked up because a rumor of easier terms met a loud refusal, while the physical risk in a famous waterway stayed on the table. That combination is enough for a bid. It is not enough for a new era. The next conversation in Doha, and the next sentence from either capital, will tell you whether Wednesday was a footnote or the start of a heavier week.
I will be watching the boring parts. The meeting notes. The insurance whisper. The second price move after the first adrenaline fades. That is usually where the truth sits, a little late and a lot less theatrical than the opening line.
A business that makes nothing but money is a poor business.


Binance Pay Japan: Crypto Spending At PayPay Merchants

Fico Stock Crash After Mortgage Score Pricing Shakeup
Related Articles

..
With Trump's address to the nation tonight, oil at $100 a barrel and the Strait of Hormuz nearly closed, what will he announce about ending the Iran war? The markets are watching closely, but one key detail could change everything...
Why State Media Undermines Trust In Relationships
Can state media sabotage your relationships? Discover how controlled narratives erode trust and what you can do to build stronger, authentic connections...
Altcoin Season 2025: Are the Stars Finally Aligning Again?
Bitcoin dominance is kissing a multi-year diagonal resistance. ETH/BTC is hugging historic support. In both 2017 and 2021, this exact setup triggered months of altcoin outperformance. History doesn’t repeat… but it sure rhymes. Is the next altseason quietly loading right under our noses?