
Have you noticed how quickly space stopped sounding like a distant science project and started sounding like a balance-sheet story? That shift hit me again this week while listening to Blue Origin’s chief executive talk about the company’s first outside funding round. He called it oversubscribed. He also said it is not closed. Those two facts together tell you more about the moment than any polished slogan ever could.
Why Blue Origin’s First Outside Raise Matters Now
For more than two decades the company lived on one person’s checkbook. That is unusual even in the private space world. Most firms chase capital early because rockets eat cash and calendars slip. Blue Origin waited. Then it waited some more. Now the door is open, and the line of investors is apparently longer than the room.
I find that timing fascinating. Not because fundraising is glamorous. It rarely is. It matters because the company is trying to grow from a privately bankrolled builder into a scaled operator. Rockets. Satellites. Orbital compute. Talent. All of that costs more than patience.
The chief executive, Dave Limp, spoke at a Washington tech gathering and sounded almost surprised by the appetite. He said the investor community “embraces space this much.” He framed space as infinite in possibility, especially for commercial activity. That line could have been marketing. In context, it felt more like a man watching demand outrun the paperwork.
I’m so amazed the investor community embraces space this much. They know that space is kind of infinite and the possibilities of putting commercial things in space.
– Dave Limp
Reports circulating last week put the raise around ten billion dollars and the valuation near one hundred forty billion. The founder is said to have added another two billion in this round after already putting in tens of billions since 2000. Limp did not confirm those figures. He also did not deny the direction of travel. That silence is its own kind of signal.
A Company That Lived Off One Wallet For 26 Years
Blue Origin was founded in 2000. For most of that stretch it was treated as a long-horizon project rather than a conventional growth company. That model bought freedom. It also delayed the kind of outside scrutiny that forces cleaner milestones and public valuation language.
Bringing in outside money changes the conversation inside a firm. Employees suddenly have a number they can point to. Recruiters have a story that sounds less like a hobby and more like a career. Competitors notice. So do customers who want to know the vendor will still exist in ten years.
In my view, that human piece is underrated. People do not join a rocket company only for the view from the factory floor. They join because they think the thing will last. An external valuation, even if imperfect, is a social proof tool. Limp said as much. Attracting great talent is hard. Showing staff what the company is worth helps.
The Market Backdrop That Made This Raise Possible
Space companies have drawn unusually loud attention this year in both private and public markets. One rival’s listing earlier in the summer acted like a spotlight. Suddenly the commercial space economy stopped being a niche slide in a conference deck and became a category investors could put in a model.
That does not mean every space ticket is a bargain. It means capital is hunting for scale stories with hardware that already flies. Blue Origin can point to a heavy launcher that has reached orbit, landed a booster, and also suffered ugly setbacks. That mix is messy. It is also real. Markets tend to prefer messy reality over perfect vapor.
Limp described the decision to raise as a combination of things. The rocket has flown more than once. Two satellite architectures have been unveiled. The company needs people, and people want to see value. None of those reasons is exotic. Together they explain why now instead of five years ago.
- Hardware that has already left the pad more than once
- Clearer product maps for communications and compute in orbit
- A talent market that rewards visible valuation
- Investor appetite that has widened after other space listings
Perhaps the most interesting aspect is how openly he tied fundraising to culture. Not just steel and engines. Headcount. Retention. The unglamorous grind of keeping specialists from walking across the street.
New Glenn Has To Fly Again Before The Story Holds
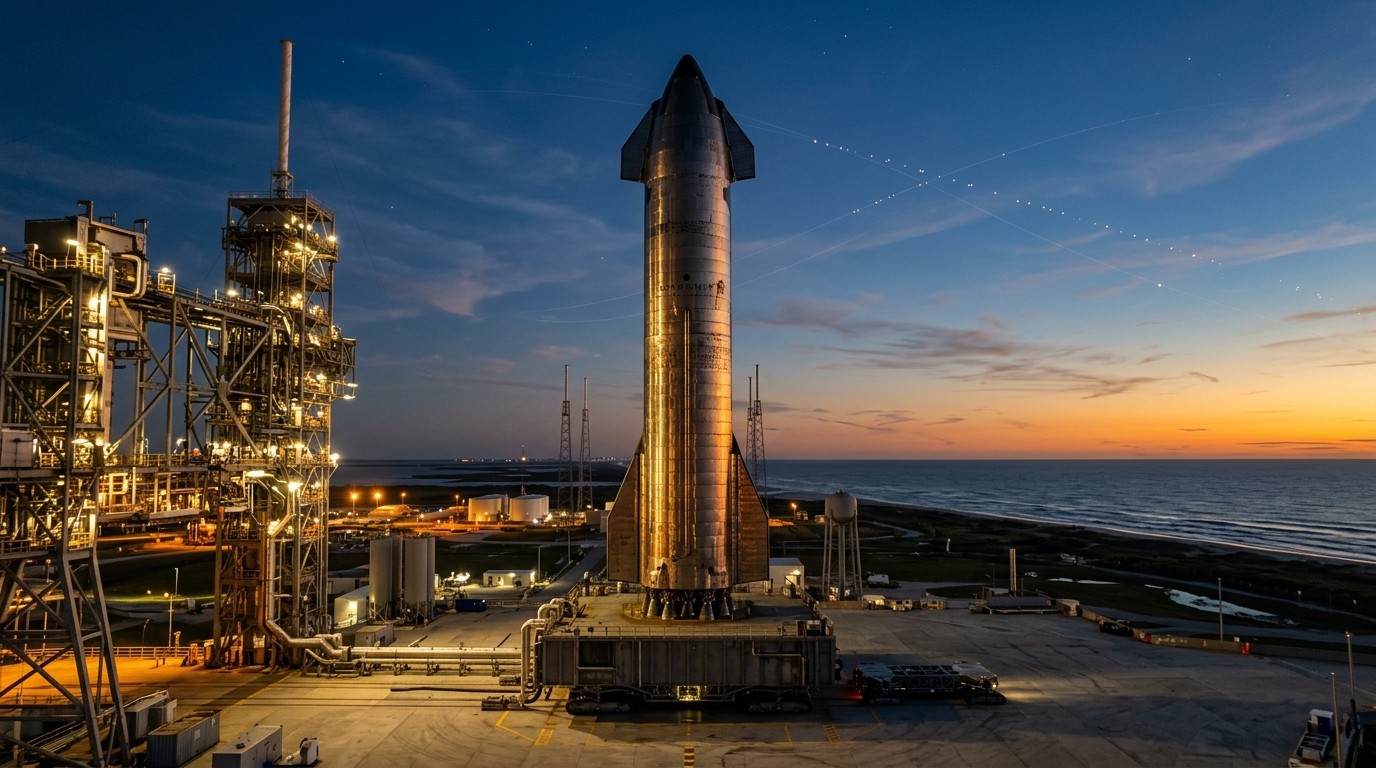
Investors can love a narrative. They still watch the pad. New Glenn reached orbit on its first flight early last year. Last fall the booster came back on the second mission. In April a third flight mixed good and bad: the booster landed, the payload did not end up where it needed to be, and a customer satellite was lost.
Then came the late-May disaster. A catastrophic explosion on the Cape Canaveral pad tore up infrastructure the company has been repairing ever since. That is not a footnote. Pads are scarce. Time on them is money. A blown pad can reset a year.
Limp still says the plan is to return to flight before the end of this year. He described a thousand people on the pad, split between day and night shifts. That image stays with me. Five hundred by sunlight. Five hundred under floodlights. It sounds like a factory that refuses to admit the calendar is optional.
The plan is still for New Glenn to return to flight before the end of this year.
Will they make it? I do not know. Launch schedules slip for boring reasons as often as dramatic ones. Weather. Avionics. A supplier that missed a weld spec. The point is that the funding story and the flight story are now braided. If the rocket sits too long, the valuation story gets heavier to carry.
Two Constellations, Two Bets On What Orbit Is For
Hardware is only half the pitch. The other half is what those rockets will haul. In January the company outlined TeraWave, a communications network aimed at enterprises, data centers, and government users rather than household broadband. The planned fleet is more than 5,400 satellites in low Earth orbit.
In March came Project Sunrise, a far larger idea: tens of thousands of satellites built to handle artificial intelligence computing from space. The figure discussed was about 56,000. That number is so large it almost feels abstract until you remember each unit still has to be built, launched, powered, and replaced.
Limp offered some of his most detailed comments yet on the orbital data-center concept. Many of the heavy compute nodes would go into sun-synchronous orbit, where sunlight is a steadier power source. Those centers would not carry much communications gear of their own. They would hand results to TeraWave for the trip back to Earth. The phrase he used was access to “effectively infinite compute.”
That is a bold sentence. I like bold sentences when a company also admits the plumbing. Rockets have to fly often. Satellites have to talk. Power has to hold. Heat has to leave a box sitting in vacuum. None of that is solved by a slogan.
| Program | Role | Scale Discussed |
| New Glenn | Heavy lift and cadence | Hundreds to thousands of missions a year over time |
| TeraWave | Enterprise and government links | More than 5,400 satellites |
| Project Sunrise | Orbital AI compute | About 56,000 satellites |
The Cadence Problem Nobody Can Hand-Wave Away
Limp said the company wants launch cadence to climb from hundreds of missions a year toward thousands. Read that again. Thousands. That is not a modest operations plan. That is an industrial transformation.
Reusable boosters help. They do not delete physics, range rules, or factory bottlenecks. If you want thousands of flights, you need engines that arrive on time, stages that get refurbished without becoming science projects, and a pad network that does not freeze after one accident.
I’ve found that people outside the industry treat cadence like a software toggle. Flip it and volume appears. Inside the industry it is closer to running a port. Ships, weather, crews, inspections, insurance, neighbors. Miss one piece and the queue backs up.
- Prove the booster can fly, land, and fly again on a tight loop
- Repair and harden the damaged Cape infrastructure
- Build satellites at a rate that matches the rockets
- Connect compute nodes to a communications layer that actually works
- Keep enough skilled people in the building to do all of the above
That list looks simple on a screen. Each line hides a decade of trade-offs.
What “Oversubscribed” Really Signals To Markets
Oversubscribed is a flattering word. It means more money wanted in than the company planned to take, or at least more interest than seats at the table. It does not mean the deal is finished. Limp was careful on that point. The round has not closed.
Why leave it open if demand is strong? Maybe terms are still moving. Maybe the cap table needs shaping. Maybe a strategic name matters as much as the dollars. Companies at this scale often treat a raise as both financing and signaling. Who is in the room can matter as much as how much they write.
There is also the founder question. After funding the firm alone for so long, adding outside capital is a cultural event. Control, board dynamics, disclosure habits, even the tone of internal meetings can shift. That is not drama. That is governance.
Limp went so far as to say he believes this will be the founder’s best investment, and he noted the track record already includes some famous wins. That is a confident claim. Confidence is useful in a raise. It is not a substitute for flight rate.
Talent, Valuation, And The Quiet HR Problem In Space
Aerospace hiring is a contact sport. The same propulsion engineers, avionics leads, and thermal specialists get calls from multiple firms. Equity stories matter. So do mission stories. A company that can show an outside price tag gives employees a language for their own net worth inside the building.
That can cut both ways. A high mark feels great until the next round or the next delay. Still, Limp is right that opacity has a cost. People guess. Guessing usually lands on the pessimistic side when paychecks compete with more liquid options elsewhere.
In my experience, the firms that retain specialists are the ones that pair hard missions with boring operational competence. Cool slides fade. A pad that launches on a rhythm does not.
Orbital Compute Sounds Magical Until You Do The Power Math
Putting AI workloads in orbit is one of those ideas that makes dinner conversation easy and engineering meetings long. The pitch is clean. Constant solar in the right orbit. Distance from terrestrial power grids. Room to grow without fighting a local zoning board.
The frictions are also clean, in a harsh way. Launch cost per kilogram. Thermal rejection. Radiation. Latency if you need a tight loop with Earth. Servicing. Replacement. Software updates on hardware you cannot walk over to and reboot with a key.
Blue Origin’s answer, as described this week, is specialization. Heavy compute in one layer. Communications in another. New Glenn as the truck. That architecture is coherent on a whiteboard. Execution will decide whether it becomes an industry or a case study.
Working mental model:
  Rockets move mass.
  TeraWave moves bits.
  Sunrise burns watts on orbit.
  Earth still wants answers on the ground.
If those four lines stay aligned, the “infinite compute” line starts to sound less like poetry. If one line breaks, the poetry gets expensive.
The 100-Year Vision And The Next 12 Months
Limp repeated the company’s long mission: build an economy in space, get millions of people working and living off Earth, move heavy industry outward, and leave this planet looking more like a park. That is a century-scale sentence. Fundraising rounds are not century-scale events. They are quarters and covenants and close dates.
The tension between those clocks is the real story. Vision pulls talent. Cadence pays bills. Outside investors will live in the short clock even if they nod along to the long one.
So what should a serious reader watch after the applause fades?
- Whether New Glenn actually leaves the repaired pad this year
- Whether the next payloads reach the orbits they were sold for
- How quickly satellite production can look like a factory, not a prototype shop
- Whether the raise closes on terms that match the rumor mill
- Whether hiring stays ahead of burnout on those night shifts
None of that is cynical. It is how industrial stories mature. The romance gets you in the door. The schedule keeps you there.
How This Fits A Broader Commercial Space Wave
Blue Origin is not raising in a vacuum. Launch prices have been under pressure for years. Satellite operators want more capacity. Governments want alternatives. Data-center operators are staring at power constraints on the ground and wondering whether any part of the stack can live elsewhere.
That last point may be the sleeper. Terrestrial compute is running into electricity, water, and permitting walls in more regions than people like to admit. If even a slice of training or inference can move to orbit without wrecking latency or cost, the addressable market stops looking like “space fans” and starts looking like “anyone who buys compute.”
I would not bet the farm that the first generation looks cheap. Early orbital capacity rarely does. I would watch whether the second generation does. That is usually where industries either become utilities or remain boutique.
Risks That Do Not Fit On A Keynote Slide
Let’s be blunt. A pad explosion is not a branding issue. It is an operational scar. Mixed payload outcomes are not trivia. Customers remember lost spacecraft. Constellations of tens of thousands of satellites raise debris, licensing, and coordination questions that no single company can shrug off.
There is also concentration risk. A firm that spent 26 years on one source of capital is now inviting many sources in at once. That can strengthen the balance sheet. It can also create new voices in rooms that used to have one.
And yes, valuation risk sits in the corner. Big marks feel wonderful on the day they print. They become a burden if the next proof point slips. Space is unforgiving that way. The vehicle either flies or it does not. Markets can argue about multiples. They cannot argue with telemetry for long.
Our mission at the company is to make an economy in space, get millions of people working and living in space. That’s the 100-year vision, but it allows us to move heavy industry off the planet, turn this planet into a park.
– Dave Limp
I like that paragraph. I also want the next launch date more than I want another metaphor about parks. Both can exist. Only one pays for the night shift.
What Investors Think They Are Buying
If you strip away the poetry, the buyers in an oversubscribed round are making a stacked bet. They want a heavy launcher that becomes routine. They want satellite product lines that find paying customers beyond demo missions. They want a path from scarce flights to industrial cadence. They want a brand that can hire when the labor market is tight.
They are also buying time. Time for the pad to heal. Time for the next vehicles to stack. Time for regulators and customers to treat the firm as a default option rather than an experiment.
Is that worth a nine-figure or ten-figure check? That depends on your time horizon and your tolerance for hardware risk. Some funds live for this kind of story. Others will wait for a cleaner flight record. Both reactions can be rational.
A Practical Way To Read The Next Headlines
When the next update lands, ignore the adjectives first. Look for verbs. Did the vehicle fly? Did the booster come back? Did the payload reach the intended orbit? Did the raise close? Did production numbers move from “planned” to “delivered”?
Adjectives are cheap in this sector. Verbs are not.
Also watch how the company talks about customers. Enterprise and government communications is a different sales motion than consumer broadband. Orbital compute is a different sales motion still. If those conversations start naming workflows rather than visions, the story is maturing.
Why This Moment Feels Different From Earlier Space Booms
Earlier waves sold tourism, flags, and novelty. This one is selling infrastructure. Trucks. Pipes. Compute. That does not make it safe. It does make it more comparable to other capital-intensive industries that eventually found repeatable unit economics.
Blue Origin arriving late to outside capital is almost an advantage if the hardware is real. The firm did not have to narrate a rocket that had never flown. It has flown. It has also failed in public. Investors who do the work can price both.
That is healthier than a market that only hears success. Ugly data is still data.
The Human Texture Behind The Funding Headlines
It is easy to treat a raise as a spreadsheet event. Stand on that Cape pad at night and it becomes something else. A thousand people rotating through repairs after an explosion is not an abstract “operational update.” It is overtime, logistics, spare parts, and the particular fatigue that shows up when a public deadline is sitting on a damaged structure.
I keep coming back to that split shift. Day crew. Night crew. Same goal. Get the architecture back into a state where a vehicle can leave without turning the facility into wreckage again. If the company hits the year-end window, that grind will deserve as much credit as the pitch deck.
If it misses, the funding will still matter. It just will not feel like a victory lap. It will feel like fuel for a longer repair.
Where The Story Goes From Here
Blue Origin is trying to do several hard things at once: close a first-of-its-kind outside round, restore a wounded launch site, raise flight rate, and sell two satellite architectures that live at very different altitudes of ambition. Any one of those would be a year. Together they are a test of management more than messaging.
The investor rush tells you the market wants the category to work. Oversubscription is applause. Applause is nice. The vehicle on the pad is the review that counts.
I’ll be watching the close of the round, the next New Glenn attempt, and whether TeraWave and Sunrise start to look like programs with factories behind them. Until then, the company has something it did not have for 26 years: a crowd of outsiders with money on the table and opinions to match. That is a new chapter. It is not the last one.
And if you only remember one thing from all this noise, make it this. Space stopped being a spectator sport when the invoices got this large. The firms that treat launch like industry, not theater, are the ones that will still be standing when the next oversubscribed round looks ordinary instead of historic.