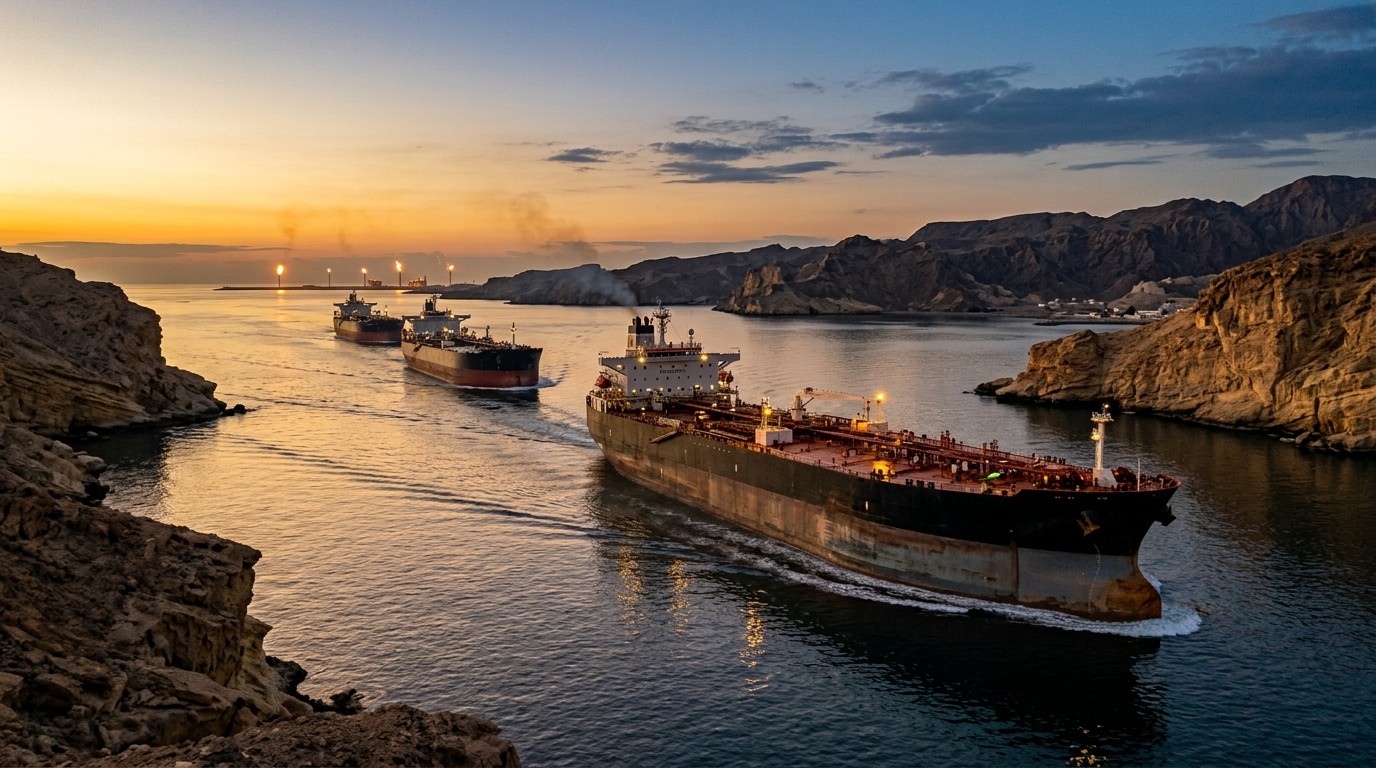

Have you noticed how quickly a headline about tankers can change the mood in a trading room? One week the map looks closed. The next week barrels are moving again, and people start talking as if the whole shock is already behind us. That is the strange place energy markets sit in right now. Crude leaving the Persian Gulf has climbed back toward its prewar rhythm, even after months of disruption around the most famous chokepoint on the planet. I keep coming back to a simple question. If the waterway is effectively open again, why does the oil price still feel so heavy?
What The Latest Gulf Export Rebound Really Shows
Energy desks now estimate that Persian Gulf oil shipments, including so-called dark exports, have recovered to about 23.3 million barrels a day over the past week. That is roughly in line with the 2025 average. After a brutal stretch, September flows roughly doubled. That is not a rounding error. That is a market catching its breath.
Most of the bounce is crude, not finished fuel. Crude made up nearly 90 percent of the September recovery and recently ran near 19 million barrels a day, or about 108 percent of its 2025 average. In my experience, that kind of split matters more than the headline total. The world can cheer tankers leaving port and still struggle to fill diesel tanks at the other end of the voyage.
The remarkable adaptation of both Middle East supply and China import demand supports a base case that Brent prices moderate later this year and ease further into 2027.
That is the optimistic reading. Adaptation is real. Ship-to-ship transfers, longer routes, and extra barrels from regional producers have filled gaps that looked permanent only a few months ago. I find that part almost impressive. Markets hate a vacuum. They invent workarounds faster than official statements admit.
Hormuz Is Open Enough To Change The Power Balance
The fight over the strait is not a classroom debate. It is a contest over who can move molecules and who cannot. Commodity specialists now argue that Washington has the advantage in that specific battle. Crude from regional partners traveling through the waterway and bypass routes has climbed to around 80 percent of prewar levels. Iranian seaborne crude, by contrast, has been described as collapsing toward zero under the combined weight of conflict, sanctions, and enforcement.
That is a sharp divergence. One set of producers is learning to live with risk. Another is watching its main cash crop stall. A couple of months ago, a rebound of this size would have been treated as a clean win. Yet Brent still trades around $103 a barrel. Inside any government that promised cheaper fuel, someone is asking the awkward follow-up. If this is winning, what would losing look like at the pump?
Perhaps the most interesting aspect is how quickly public language can outrun physical reality. Officials can say a strait is closed. Traders watch AIS tracks, dark fleet patterns, and loading data. Right now those two stories do not match. The waterway looks far more usable than the loudest rhetoric suggests.
Why Crude Recovery Is Not The Same As Fuel Relief
Here is the part that does not fit on a bumper sticker. Restoring crude flows only solves one slice of the shock. Diesel, gasoline, and jet fuel exports from the Gulf recently sat at roughly half their 2025 average. That is the quiet crisis. Refineries, not just tankers, decide whether households feel this story.
Russia still faces a damaged refining system and extended limits on product shipments into the fall. Add a Gulf product shortfall and you get a market that can look well supplied in crude while remaining tight in the fuels people actually burn. I have found that this mismatch is where political messaging usually breaks down. Leaders talk barrels. Drivers buy liters.
- Crude loadings can rebound while product yields stay impaired
- Winter demand in the Northern Hemisphere still sits ahead of the calendar
- Strategic stock releases can cap crude spikes without fixing diesel scarcity
- China can absorb extra crude even as Western product balances stay tight
- Insurance, routing, and freight costs keep a risk premium in the curve
Some analysts now warn that the global refining squeeze could linger well into 2027. That timeline is longer than most election cycles and longer than most memory spans on social media. It is also the reason a $103 Brent print can coexist with improving Gulf loadings. The barrel is back. The molecule that comes out of the cracker is not fully back.
How Producers Split After The Shock
Saudi shipments led the recovery. That should surprise no one who watches spare capacity and logistics. Other Gulf producers also raised exports while Iranian volumes fell. The result is a regional map that looks more uneven than the old prewar picture. Allies move more. The isolated producer moves less. The strait still matters, but it no longer functions as a single on-off switch for every barrel in the neighborhood.
A drone strike that stalled a major East-West pipeline complicated the picture for a stretch. The latest reports say that line has restarted. Combined with more Hormuz sailings and ship-to-ship activity, the system found enough slack to push crude back toward normal. Slack is not the same as safety. It is simply enough room to keep the trade alive.
| Flow Type | Recent Signal | Market Implication |
| Total Gulf oil including dark barrels | About 23.3 million b/d | Headline supply scare eases |
| Gulf crude | Near 19 million b/d | Raw feedstock looks healthier |
| Diesel, gasoline, jet | Around half of 2025 average | Fuel prices stay politically painful |
| Iranian seaborne crude | Sharp drop toward zero | Fiscal pressure rises in Tehran |
| Ally crude via Hormuz and bypasses | About 80 percent of prewar | Chokepoint leverage fades |
Look at that table long enough and the contradiction becomes obvious. The world is winning the crude logistics fight and still losing parts of the products fight. That is why forecasts of Brent drifting toward $85 by year-end and $80 in 2027 can sound plausible without feeling cheap at the station.
Dark Exports, Workarounds, And The New Normal
Dark exports is one of those phrases that sounds cinematic and turns out to be bookkeeping. It covers barrels that do not show up cleanly in standard tracking. Ship-to-ship transfers, opaque ownership chains, and quiet rerouting all live in that bucket. Analysts now fold those estimates into the Gulf total because ignoring them would understate how fast the region adapted.
I do not love the romance around shadow fleets. The operational truth is duller and more important. If a cargo can be transferred offshore, insured at a price, and accepted by a refiner who needs feedstock, it will move. China has been part of that demand story. Import appetite there helped absorb barrels that might otherwise have sat in floating storage and kept prices even higher.
Is that a stable equilibrium? Maybe not. It is a workable one. Workable is often all energy markets get after a geopolitical rupture.
The Price Puzzle Above One Hundred Dollars
Brent around $103 after a Gulf export rebound is the detail that should keep policy people awake. Markets are telling you that logistics improved and scarcity did not fully leave the building. Risk premia linger. Product cracks stay firm. Inventories in the right places are not as comforting as a weekly loading print.
There has also been another request for a U.S. strategic reserve release. That is a familiar tool. It can shave the front of the crude curve. It does less when the bottleneck is refining capacity, product quality, or regional diesel balances. Dumping crude into a system that cannot convert it fast enough is a bit like sending more flour to a bakery that lost half its ovens.
Diplomatic signals this week added to the softer tone in futures. Talk of off-ramps always does that. Still, seven months into the conflict, with an eighth month approaching, traders have learned not to treat a quiet news day as peace. They treat it as a pause.
Winter Demand Is The Next Stress Test
Northern Hemisphere winter is not an abstract seasonal footnote. Heating demand, freight, and air travel do not wait for geopolitics to look tidy. A market that has only half-normalized product exports heading into that stretch is a market that can still surprise to the upside on fuel prices even if crude eases.
I’ve found that winter is when the public stops caring about loading statistics and starts caring about invoices. That is also when governments feel pressure to do something visible. Reserve releases, export tweaks, price-talk, moral suasion toward refiners. The toolkit is known. The timing is what matters now.
- Watch Gulf product loadings, not only crude loadings
- Track diesel cracks as a cleaner stress gauge than Brent headlines
- Follow whether bypass pipelines stay online after repairs
- Separate Iranian export collapse from the broader Gulf recovery
- Ask whether China keeps absorbing extra crude at current prices
Those five checks are more useful than another argument about who “won” the strait. Winning a maritime contest and delivering affordable winter fuel are related jobs. They are not the same job.
Sanctions, Blockade Pressure, And Time As A Weapon
The combination of blockade risk and sanctions is approaching what some observers call maximum impact on the isolated producer. Time works differently in that setting. A government can endure a bad month. A string of bad quarters with export receipts near zero is another matter. Fiscal strain does not show up first in a press conference. It shows up in delayed wages, thinner subsidies, and uglier choices.
That does not tell you how a war ends. It tells you how the economic clock is running. One market comment this week put it bluntly: the damaged side can theoretically wait, but the economic pain is now set to accelerate. Imaginations in a capital under that kind of pressure tend to run hot. That is analysis, not a prediction of any particular decision.
What This Means For Investors Who Do Not Trade Tankers
Most readers are not chartering VLCCs. They hold energy stocks, inflation-sensitive bonds, transport names, or just a household budget. For them the useful frame is simple. Crude availability is improving faster than fuel availability. That mix supports a messy middle: lower odds of a fresh super-spike in prompt crude, higher odds that refined product tightness stays politically loud.
Equity investors in integrated majors may like the idea of better feedstock access with still-healthy cracks. Pure upstream names live more with the Brent path. Refiners live with utilization, margins, and whether damaged systems elsewhere stay offline. Airlines and trucking live with jet and diesel. There is no single “oil trade” hiding inside this rebound.
In my view, the sloppy mistake is treating 23.3 million barrels a day as proof that the energy shock is over. It is proof that the region adapted. Adaptation is bullish for supply continuity and still compatible with sticky inflation in fuels.
A More Human Read Of A Cold Market Story
Strip away the jargon and the story is almost physical. Ships found ways around fear. Pipelines got patched. Buyers who needed crude kept buying. A government that relied on oil income watched that income shrink. Another government that wanted cheaper gasoline discovered that opening a strait is not the same as opening a refinery gate.
That last gap is why the mood can feel so split. On a map, the advantage in the Hormuz fight looks clearer than it did in midsummer. On a receipt for diesel, the victory is incomplete. I keep thinking that is the adult way to hold both facts at once. Not triumph. Not panic. A partial repair in a system that still has cracked pipes downstream.
If restoring crude flows is only one part of the shock, then celebrating tankers without watching product yields is how markets talk themselves into the next surprise.
Will Brent really grind toward $85 by December and $80 next year? It could, if adaptation keeps beating disruption and if demand does not reaccelerate too hard. It also might not, if winter is cold, if another piece of infrastructure fails, or if product shortages force crude to stay elevated as a substitute signal. Forecasts are maps. Weather still happens.
For now the evidence says Gulf exports have roared back close to the old baseline. That sentence would have sounded impossible earlier in the conflict. It is also incomplete. The strait looks open enough. The refined barrel still looks scarce enough. And the season that tests both of those claims is only beginning to arrive.
The Details Traders Will Argue About Next
Every recovery invites a fight over measurement. Are dark barrels counted too generously? Are weekly figures being annualized by people who should know better? Is 80 percent of prewar ally flow a victory or a reminder that 20 percent is still missing? Those arguments are healthy. They keep the story from hardening into a slogan.
I would rather see messy data than a clean myth. Messy data is how you notice that crude can print above its 2025 average while gasoline and diesel limp along at half speed. Messy data is how you notice that one producer’s collapse can be offset by another producer’s surge without the global product balance healing on the same timetable.
Professional desks will keep updating those series week by week. Households will keep updating their own series every time they fill a tank. Both datasets are real. Only one of them gets a press conference.
Holding The Two Timelines In Your Head
There is a logistics timeline and a refining timeline. On the first, the news is better. Loadings recovered. Routes reopened. Bypass options mattered. On the second, the news is slower. Product exports remain depressed. Damaged plants elsewhere have not snapped back. Winter has not voted yet.
Policy that only addresses the first timeline will look successful in a loading report and disappointing in a fuel index. That is not a partisan point. It is an industrial one. You cannot speech-write your way around distillation capacity.
So yes, Gulf exports have come back toward prewar levels. Yes, the advantage in the chokepoint fight appears to have shifted. And yes, the price of living with that “win” is still written in diesel, jet, and gasoline. The market is trying to tell a two-part story. The useful habit now is to listen to both parts before deciding the episode is over.