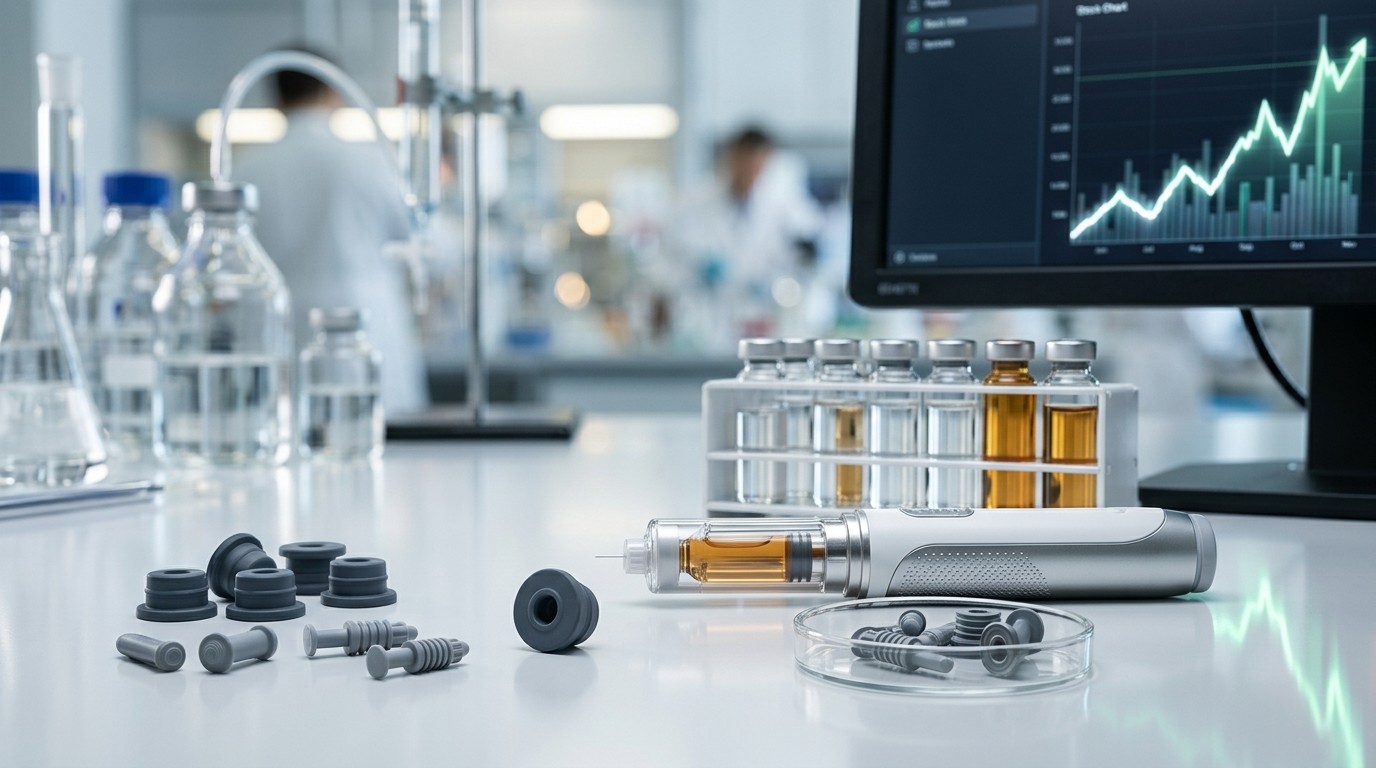

Have you ever wondered who actually makes the tiny rubber stopper on a vaccine vial, or the plunger that pushes a weekly weight-loss shot into someone’s arm? I have, more than once, usually while staring at a chart that looked dead for years and then suddenly refused to stay dead. That quiet supplier is West Pharmaceutical Services, ticker WST, and it sits in that odd corner of the market where patients never see the brand, yet almost every injectable therapy depends on it.
Why A Forgotten Pharma Supplier Is Back In Play
West does not invent the next blockbuster molecule. It builds the packaging those molecules live in. Stoppers. Seals. Syringe plungers. Containment systems. Home-use auto-injectors. If a biologic, a vaccine, insulin, or a GLP-1 needs a sterile path from factory to patient, there is a decent chance West is somewhere in that path. That is the whole pitch, and it is simpler than most investors want it to be.
I like businesses that sell the pickaxes. You do not have to guess which drugmaker wins a crowded race. You just need the race to keep happening. GLP-1 therapies from the usual heavyweights are a tailwind, not the entire story. Biologics were already a long-cycle demand driver before weight-loss ads took over late-night television.
What The Company Actually Sells
Strip away the investor-speak and the product line is almost tactile. High-value components sit at the premium end of the stopper and seal business. Those parts have tighter specs, better materials, and stickier customer relationships. They now account for roughly half of sales. Management has said GLP-1 related demand alone has grown into a meaningful slice of revenue, recently cited around the high teens as a percentage of the mix.
That mix shift matters more than a single quarter of volume. Premium components tend to carry better pricing power. When a drug is already expensive and highly regulated, switching a validated stopper is not something a manufacturer does on a whim. In my experience, that kind of switching cost is the difference between a commodity molder and a franchise.
You do not have to pick the winning molecule if you already sell the package every winner still needs.
West also used to own a larger injector story. It sold the SmartDose 3.5 milliliter injector business to a large drugmaker for about $136 million. That deal cleaned the portfolio a bit and put cash to work elsewhere. Not every product line has to stay in-house forever. Sometimes the smarter move is to harvest a niche and double down on the core containment franchise.
The Hangover After The Covid Spike
The stock once felt unstoppable. Shares peaked near $475 in September 2021, when vaccine campaigns had customers stuffing warehouses with components. Then reality arrived the way it often does in healthcare supply chains: slowly, then all at once. Customers worked through inventory. Revenue barely moved from $2.83 billion in 2021 to $2.89 billion in 2024. Diluted earnings slipped from $8.67 to $6.69. Gross margin compressed from 41.5 percent to 34.5 percent.
Those are ugly numbers if you bought the peak. They are also the kind of numbers that create later opportunity, provided the franchise itself did not break. West did not lose its customers. Demand just went on pause while freezers and warehouses were emptied.
The five-year annualized return still sits in negative territory even after the recent bounce. That fact alone keeps a lot of people away. Fine. Crowds are usually late to destocking stories and even later to restocking stories.
The February Shock That Broke The Chart
The real scar formed on February 13, 2025. Management guided 2025 adjusted earnings to a $6.00 to $6.20 range, far below the $7.44 consensus many models had been carrying. The stock dropped about 38 percent in a single session. That was the worst day in company history and the capstone on a nearly 60 percent peak-to-trough drawdown.
Was the market overreacting? Partly. Guidance resets in quality compounders often look like character assassinations on day one. Still, you cannot shrug off a miss that large. Customers were clearly more cautious than the Street wanted to admit. The inventory work-down lasted longer than the optimistic slide decks suggested.
Here is the part that gets interesting now. That same company later raised the outlook twice. Sales guidance moved from a February range of $3.22 billion to $3.275 billion up toward $3.345 billion to $3.38 billion. Adjusted earnings guidance climbed to $8.85 to $9.05. That is 21 to 24 percent growth, and it sits nearly 50 percent above the range that cracked the stock nineteen months earlier.
The Fundamentals Finally Flipped
Second-quarter sales rose 13.8 percent to $872 million. Adjusted earnings jumped 28.8 percent to $2.37, beating by $0.29. High-value components grew 19.4 percent and reached 49 percent of sales. Gross margin expanded 200 basis points to 37.7 percent. That is not a complete recovery to the old 41 percent-plus days, but it is the right direction after years of squeeze.
GLP-1 demand is the headline everyone wants. Fair enough. Those therapies need reliable containment at industrial scale, and the volumes are not a one-year fad if adherence holds. I would not build the entire thesis on one drug class, though. The healthier setup is a company selling into several injectable categories at once while the mix quietly tilts toward higher-spec parts.
- High-value components now approach half of the sales mix.
- GLP-1 exposure has become a visible, not theoretical, revenue driver.
- Margins are expanding again after a multi-year compression.
- Management has lifted the full-year outlook more than once.
- Capital return has turned aggressive after the destocking scare.
Perhaps the most interesting aspect is how quickly the earnings power reappeared once inventories normalized. That tells you the operating system was bruised, not broken. Companies with real switching costs often look worse than they are during a destock. Then they look better than skeptics expect when orders resume.
Cash, Buybacks, And A New Chief Executive
West bought back $454 million of stock in the first half of 2026 and authorized a fresh $1 billion repurchase program, roughly 4 percent of the then-current market cap. Pair that with the injector sale and you get a management team that is no longer waiting politely for the multiple to recover on its own.
Leadership changed as well. Michel Lagarde became chief executive on August 31, succeeding Eric Green. Lagarde previously served as chief operating officer at a major life-science tools group, where he ran the bulk of the businesses. New CEOs are not magic. Still, a leader who has already managed large, regulated, customer-intimate operations is a better fit than a celebrity outsider with a slide deck and a slogan.
I’ve found that markets give new operators a short grace period if the numbers are already turning. That is the window West is in. The operations are improving first. The leadership story is arriving second. That sequence is healthier than the reverse.
Valuation Is Not A Bargain, And That Is The Point
Around $373, the shares were trading near 42 times the midpoint of 2026 guidance, with earnings growing north of 20 percent. That is not cheap. Anyone calling this a deep-value name is stretching. It is, however, well below the 55 times multiple the stock paid for 2021 earnings at the peak. The difference this time is direction. The multiple now sits on earnings that are rising instead of rolling over.
| Period | What The Market Saw | Why It Mattered |
| 2021 peak | Covid stockpiling and a rich multiple | Demand pulled forward, valuation stretched |
| 2022-2024 | Flat sales, weaker margins, destock | Quality compounder looked ordinary |
| Feb 2025 | Harsh earnings guide and a 38% one-day drop | Trust reset, forced sellers exited |
| 2026 rebound | Raised outlook, mix shift, buybacks | Growth returned with better quality |
Quality suppliers rarely get priced like distressed cyclicals for long. Once the growth rate is credible again, the market starts paying for durability. That can feel expensive in the moment. It also explains why waiting for a 20 times multiple on a franchise like this is often a way to miss the whole move.
How The Chart Has Been Behaving
Price action has been almost stubbornly constructive since the spring. The stock spent about six months going nowhere, chopping between the mid-$220s and the $290s. The February and March lows near $225 marked the last stretch where sellers truly dictated terms. In late April the shares cleared the top of that range. The 50-day average crossed above the 200-day not long after.
The advance carried into the mid-$360s by early July. Late July brought a spike toward $383 that reversed hard. The stock slid to the $325 area and cut through the 50-day. Buyers showed up immediately. The same pattern repeated in early September: a dip toward $330, then another reclaim of the rising 50-day. That is not elegance. It is tenacity.
Near $369, with the 50-day rising around $352 and the 200-day near $302, the summer high is close enough to matter. $383 is the level. A close above it would put the stock at a fresh 52-week high. Relative strength around 59 leaves room before the move looks exhausted. Momentum reset twice over the summer, first into the low 30s after the July reversal and again near 40 in early September. Both times the stock found its feet and marched higher.
Traders can treat $350 as a practical line. That is where the rising 50-day sits and where the August consolidation topped out. Two references landing in the same neighborhood is rarely an accident. A close below that zone would argue the run at the summer high has stalled. Use closing prices. Intraday noise in a name like this will chew up anyone who needs every tick to be meaningful.
Longer-horizon investors can anchor to the $325 to $330 band. It held twice in roughly ninety days, first in late July and again in early September. The 200-day around $302 is rising but sits too far below to be a day-to-day tool. A weekly close under $325 would say the buyers who defended that shelf twice are done, at least for this swing.
Simple map of the setup:
  Breakout watch: close above $383
  Near-term risk line: $350
  Investor support zone: $325-$330
  Background average: rising 200-day near $302
Why The Setup Feels Cleaner Than The Narrative
A lot of market commentary wants a single villain or a single hero. West does not give you that. The bear case after 2021 was inventory. The bear case in early 2025 was guidance. The bull case now is mix, GLP-1 volume, margin repair, and capital return. None of those points require you to become a molecular biologist.
There is still risk. Drug launches slip. Pricing pressure can creep into components if customers get aggressive. A new chief executive can change capital allocation in ways the tape does not like. A rich multiple leaves less room for another guidance accident. I would not pretend otherwise.
That said, the market already punished the company for the last accident. Shares fell 38 percent in a day and spent a long stretch rebuilding trust. Year to date the stock was up about 37 percent. Over the prior year it was up about 45 percent. Off the 52-week low near $223.83, the rebound was about 67 percent. Those are not trivia points. They show that capital has been willing to return once the fundamental tape improved.
The Patient Angle Investors Keep Missing
Most people encounter West without knowing it. A flu shot. A biologic infusion. A weekly pen in a bathroom drawer. The brand on the box belongs to the drugmaker. The humble parts that keep that dose sterile belong to a supplier almost nobody can name at a dinner party.
That anonymity is useful. It keeps expectations quieter than they get around famous drug tickers. It also hides how concentrated the high-spec packaging world can be. Validation cycles are long. Quality systems are unforgiving. A late or dirty component can halt a fill-finish line. Customers remember that.
In my view, the best supplier stocks share three traits. They sit inside a regulated workflow. They benefit when science gets more complex rather than less. And they can raise the mix toward higher-spec products without needing a new invention every year. West checks those boxes more cleanly than the average mid-cap healthcare name.
What Could Go Right From Here
If high-value products keep taking share inside the company, margins can grind higher even if total volume is only decent. If GLP-1 manufacturing stays elevated, utilization stays healthy. If the new repurchase program is executed with any discipline, the share count becomes a quiet tailwind under the earnings line.
- Watch whether high-value components stay near or above half of sales.
- Track gross margin versus the old mid-30s trough.
- Compare each guidance update with the February 2025 low-water mark.
- Respect $383 as the chart’s honesty test for bulls.
- Give the new chief executive a few reporting cycles before judging culture.
None of that is a treasure map. It is a checklist. Checklists keep you from turning a supplier story into a cult.
What Could Still Go Wrong
Destocking can return if customers over-order again. Healthcare systems can delay launches. A stronger dollar can nibble at translation. A quality event, even a small one, would hit this ticker harder than it hits a diversified conglomerate. And 42 times forward earnings leaves little room for a sleepy quarter.
I keep coming back to the February 2025 session as a reminder. The market will not wait politely if the company under-shoots again. That is the cost of being a premium compounder. You get paid when you deliver. You get abandoned in an afternoon when you do not.
A close above the summer high would say buyers are finished negotiating. A close under the $350 shelf would say they want another conversation.
How I Would Frame The Position
This is not a lottery ticket and it is not a bond substitute. It is a high-quality packaging franchise coming out of a multi-year digestion phase, with a richer mix, a repaired growth rate, and a chart that has defended its higher lows. If you need cheap, look elsewhere. If you need a story that does not depend on one press-release molecule, this is more interesting.
Position size should respect the multiple. A name that can drop 38 percent on a guide-down is not a place to get cute with leverage. Use the $350 area as a trading invalidation if you are treating it as a breakout. Use the $325 to $330 zone if you are thinking in quarters rather than weeks. Below that on a weekly close, the repair job is incomplete.
I also would not ignore the human side of the setup. A retiring chief executive, a new operator from a large tools company, a buyback that suddenly looks serious, and a customer base that is shipping more injectables again. Those are ordinary corporate events. Stacked together after a historic down day, they start to look like a regime change.
The Quiet Lesson Inside A Loud Chart
Markets love companies that talk. West mostly makes parts. That mismatch is why so many investors never put the name on a watchlist until the stock had already doubled off the lows. The lesson is almost boring. Follow the mix. Follow the margin. Follow whether customers are still validating the same supplier after a scare.
Will $383 give way cleanly? Maybe. Breakouts fail. Support zones fail too. The cleaner point is that the fundamental argument and the technical argument are no longer fighting each other. For a long stretch after 2021, they were. Sales were stuck while the memory of $475 lingered like a bad souvenir. That tension has eased.
If the next few quarters keep showing high-teen to 20 percent-plus earnings growth, the multiple can stay firm without needing another mania. If they do not, the stock has a well-marked set of floors where the recent buyers will have to make a decision. Either way, you find out reasonably fast. That is a luxury most messy turnarounds do not offer.
So the forgotten supplier is not quite forgotten anymore. It is still invisible in the medicine cabinet. On the screen, it is getting harder to ignore. The next decisive close above the summer high, or back under the rising 50-day cluster, will tell you whether this comeback has another leg or whether the market wants one more apology from a company that already issued a painful one.