
I still remember the first time a ten-year-old asked me, completely serious, why cash “disappears” after a weekend at the mall. That question is the whole point of a kids money app. Parents want a card that works at the store. Kids want a little independence. Everybody wants fewer arguments about who spent what. Greenlight grew up around that tension, and by 2026 it is no longer just a plastic rectangle with parental locks. It is a paid family hub with chores, investing, location tools, and even fraud coverage that can stretch to grandparents.
What Greenlight Looks Like Now
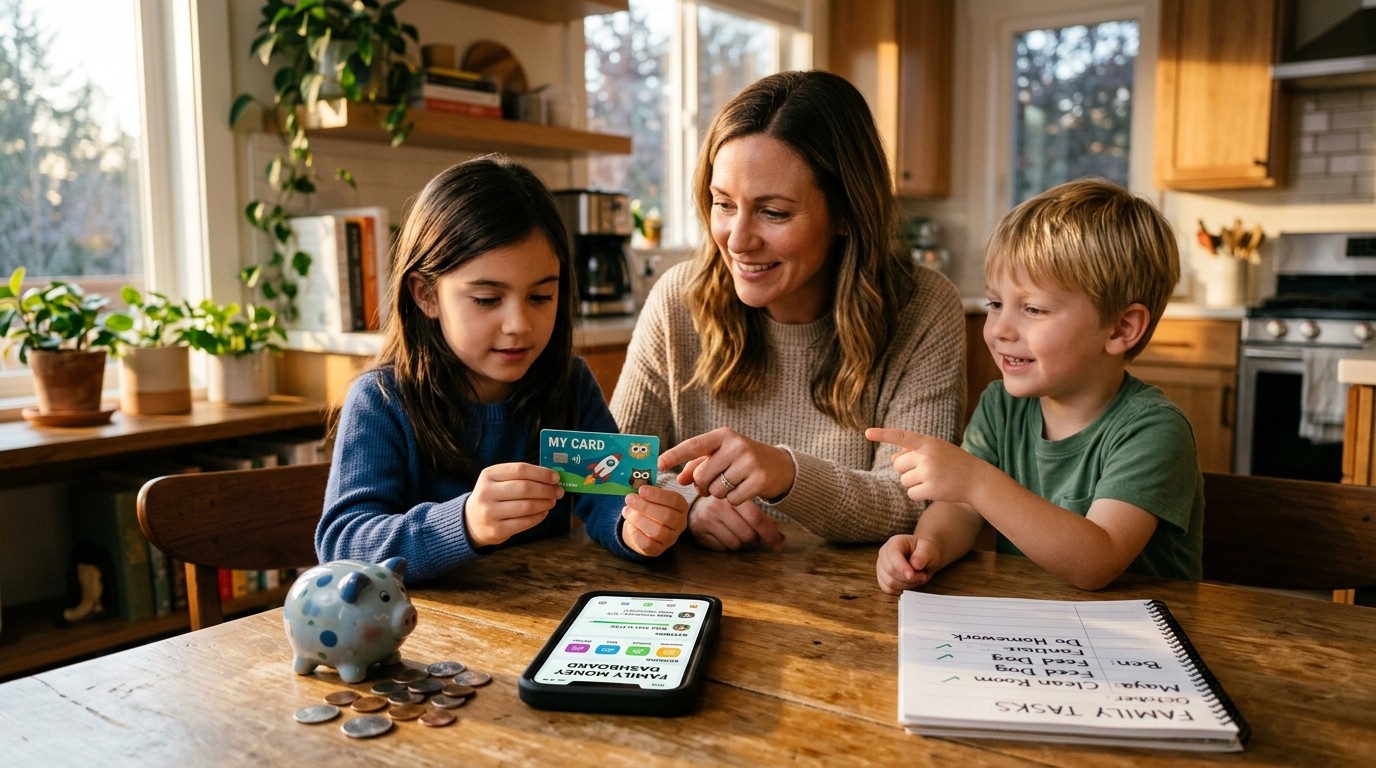
Greenlight is a subscription family finance platform. At the center sits a debit card for kids and teens. Parents load money, set rules, and watch purchases land in real time. Kids open an app, spend what is allowed, and chase savings goals that actually look like something they care about, whether that is a game console or a first concert ticket.
That core idea has not changed. The surrounding product has. Higher plans add cash back, a large menu of stocks and funds, GPS style safety tools, crash alerts for new drivers, and identity monitoring that is no longer limited to the children on the account. There is also a household hub device that showed up in mid-2026 for calendars and chores. Useful if you want one dashboard for family logistics. Expensive if you only needed a card.
I’ve found that most families do not fail at money talks because they lack lectures. They fail because the tools are messy. Cash vanishes. Shared adult accounts get confusing. A dedicated kids card with instant alerts solves a practical problem before it solves a moral one. Greenlight is betting you will pay monthly for that convenience.
The Four Plans And What You Actually Pay
Pricing is the first filter. Every plan covers up to five kids, which is the part I like. You are not punished for having a bigger household. You are charged for features.
| Plan | Monthly price | What stands out |
| Core | $5.99 | Cards, chores, allowance, savings goals |
| Max | $10.98 | Investing, cash back, extra protections |
| Infinity | $15.98 | Location tools, SOS, driving reports |
| Family Shield | $19.98 | Broader identity and fraud coverage |
Core is the no-drama tier. Cards, automated chores, savings goals, and the usual parental switches. Max is where Greenlight starts to feel like more than a wallet. Investing and cash back live here. Infinity leans into safety. Family Shield is the full wrap, including coverage aimed at older relatives. That last jump is a lot of money if you never use credit monitoring.
In my experience, families overbuy the middle tiers because investing sounds impressive at dinner. Then the teen never requests a trade. Be honest about what you will open every week. A tool you ignore is just a bill with a logo.
How The Debit Card Works Day To Day
Parents connect a bank account and move money over. Kids get a card and an app. Purchases show up fast. You can shut the card off if it is lost, block categories such as fast food or online stores, and cap how much can go out. Instant transfers mean allowance does not have to wait for a weekend handshake.
Teens on some plans can receive direct deposit from a part-time job. That matters more than people admit. A first paycheck that lands in a kids wallet, not a parent’s checking account, feels like a real milestone. It also creates a cleaner paper trail when you are teaching budgeting instead of handing over twenties.
- Real-time purchase alerts for parents
- Category blocks and spending limits
- Instant on or off control if a card goes missing
- ATM access at machines that take major debit networks
- No overdraft fee and no minimum balance
The cash back pitch starts on Max: one percent back on purchases. It is not life changing. It is a small loop that makes swiping feel slightly less wasteful. Kids notice little refunds. Adults notice habit formation. Both are useful.
There is a catch with cash machines. Broad ATM access is nice. Fee reimbursement is not part of the deal. Out-of-network withdrawals can nibble at a small balance. If your teen lives on cash for school events, that detail will matter more than the glossy card design.
Chores, Allowance, And The Awkward Money Talk
The chore system is simple on purpose. You assign a task and a payout. When the work is marked done, the money moves. That automation is the quiet hero. I have watched families argue less when the app, not a parent in a bad mood, handles the transfer.
Savings goals sit on every plan, including Core. Kids pick a target and watch the bar fill. Parents can attach an interest rate they choose. That last piece is underrated. You can make saving feel rewarding without pretending a kids balance will beat a market fund. It is a teaching lever, not a wealth engine.
Kids learn faster from a visible goal than from a speech about delayed gratification.
Perhaps the most interesting aspect is how the dashboard treats siblings differently. One subscription, five cards, separate rules. A sixteen-year-old can have more room. A seven-year-old can have tighter limits. That flexibility is why larger families often stick with paid apps even when a free bank account exists.
Investing With Training Wheels
Investing arrives with Max and stays on the two higher plans. The menu is large, thousands of stocks and funds. Kids can research and request trades. A parent still has to approve every order. That approval step is the difference between a classroom and a casino.
I like the friction. Teenagers should feel the delay. Markets punish impulse. A tap that needs a grown-up signature is a better first lesson than a slick “buy now” button. Still, do not confuse access with a complete investing education. The app can show a ticker. It cannot replace a conversation about risk, fees, and time.
If investing is the only reason you are looking at Greenlight, compare the Max price with other kids investing setups that already sit inside a broader adult portfolio. Sometimes the cheaper path is the one that already holds your own retirement money. Sometimes the separate kids interface is worth the extra dollars because your child will actually open it.
Safety Features That Changed The Product
Infinity is where Greenlight stops pretending it is only about money. Real-time location sharing, SOS alerts, crash detection, and driving reports for new drivers live on that tier. Family Shield adds identity monitoring, suspicious activity alerts, and protection that can include parents and grandparents.
Some households will love that bundling. One login for cards and a safety net feels tidy. Other households already pay for a phone plan with location tools and a separate identity service. Stacking another monthly charge on top can get silly fast.
I’ve sat with parents who wanted the driving reports more than the debit card. That is a legitimate use case. Just name it honestly. You are buying a family operations layer, not a free checking account with stickers.
Who This Platform Fits And Who Should Walk Away
Greenlight fits families that want hands-on teaching without handing over an adult checking account. It fits households with more than one child because the per-kid math stays flat through five cards. It fits parents who like approving, blocking, and watching transactions as they happen.
It is a tougher sell for a single child who only needs a simple card. Core is the cheapest door, yet many of the features that make the brand feel special sit on Max and above. If you will never open investing, never use GPS tools, and never care about grandparent fraud coverage, you may be paying for a showroom you do not walk through.
- Choose Core if you want cards, chores, and savings goals only.
- Choose Max if cash back and parent-approved investing matter.
- Choose Infinity if location and driving tools will get weekly use.
- Choose Family Shield if identity coverage for older relatives is part of the plan.
That decision tree sounds neat. Real life is messier. A family can start on Core and upgrade later. That path is saner than signing the top tier because a comparison table looked complete.
Free And Lower Cost Alternatives Worth A Look
Paid apps survive because they are convenient. Free bank products survive because the monthly fee is zero. If you already keep a checking relationship with a major branch bank, a kids account tied to that relationship can cover chores, limits, and alerts without a subscription. The tradeoff is usually less investing theater and fewer safety extras.
Teen checking products from large card issuers can work when a child is old enough to co-own an account. You get real-time notices and a lock switch. You may lose category blocking that feels as granular as a dedicated kids platform. You may gain interest on the balance, which Greenlight’s card itself is not really about.
There are also investing-first kids products that pair a card with an existing portfolio app. Those can cost less than Greenlight’s Max plan if you already pay for the adult subscription. The question is whether your child will use that interface. A beautiful adult dashboard is useless if a twelve-year-old never logs in.
Online banks with joint teen checking sometimes add a little yield and a huge ATM network. Parents can lock a card. They often cannot micromanage categories the way a kids-first app allows. For some teens that extra freedom is the point. For younger kids it can feel sloppy.
The Hidden Cost Is Attention, Not Just The Fee
A $6 or $20 monthly charge is easy to calculate. The harder cost is the time you spend managing rules. If you never update chores, the automation dies. If you approve every snack purchase with a lecture attached, the app becomes another battlefield. Tools do not replace tone.
I have a bias here. I would rather see a family use a plain free account consistently than bounce between three premium apps they forget to fund. Consistency teaches more than features. Kids notice whether money arrives when work is done. They notice whether a parent actually looks at the feed.
The best kids money system is the one both sides will still use in February, not the one that looked complete in a January comparison chart.
A Practical Way To Test Greenlight Without Overcommitting
Start with a written list of jobs you want the product to do in the next 90 days. Not a fantasy list. A short one. Examples: pay Saturday chores automatically, block online game stores, send a transfer the same night a babysitting job ends, let a teen request one index fund purchase with your approval.
If that list is three items and none of them involve GPS or identity monitoring, Core or a free bank kids account may be enough. If the list includes investing practice and cash back, Max is the honest tier. If the list includes new-driver peace of mind, Infinity starts to justify itself. Family Shield only wins if older relatives are part of the protection story you actually want to manage in one place.
Watch the first month like a hawk. Are alerts useful or noisy? Does the child open savings goals without being nagged? Did anyone request a trade? Did an ATM fee surprise you? Those answers beat any marketing page.
Small Details That Change The Experience
No minimum deposit sounds minor until you are funding a first card with twenty dollars and a pep talk. No overdraft fee means a kid cannot silently dig a hole. Those two design choices reduce shame, which is underrated in money education. Shame makes kids hide receipts. Visibility makes them talk.
Financial lessons inside the higher plans try to make saving, credit, and investing feel like a game with quizzes. Some kids love badges. Some roll their eyes. I would not pick a plan only for the lessons. I would treat them as a bonus if the card already earns its keep.
The 2026 household hub device is the wild card. Calendars and chores on a kitchen screen can reduce the “I forgot” wars. It is also another object to power, update, and pay for. If your family already lives inside a shared calendar, pause before you add hardware to a software bill.
My Take After Sitting With The Full Feature Map
Greenlight is good at being a control panel. That is the compliment and the warning. Parents who want visibility will feel relief. Parents who wanted a cheap card will feel nickel-and-dimed once they notice investing and cash back sitting behind a higher price.
Would I use it for a household with three kids and a messy chore chart? Probably, at least on Core or Max. Would I push a family with one child and an existing free teen checking option to switch? Only if the current setup creates weekly friction. Convenience is worth money. Duplicate convenience is not.
Money habits form in ordinary weeks. A card that works at the snack bar. A goal bar that moves. A parent who does not have to dig through texts for a payment screenshot. If Greenlight gives you that calm, the subscription can be rational. If it mostly gives you features you admire and never tap, keep the cash in your actual emergency fund instead.
One last thought, because this is where families get stuck. You do not owe any app a forever plan. Teach the habit. Keep the receipts of what worked. Switch if the fee starts to outrun the value. Kids will remember whether money felt understandable. They will not remember which tier you picked in 2026.