
Have you ever watched a month like September and felt that odd mix of relief and irritation? Relief that you did not panic-sell. Irritation that cash just sat there while yields jumped and equities wobbled. I have been there. A portfolio can look diversified on paper and still feel strangely quiet when you want extra income without blowing up the plan.
Why Options Belong Beside Income Assets, Not Instead Of Them
An options overlay is not a substitute for bonds or dividend-paying stocks. Treat it as a complement. That distinction matters more than any fancy ticker. When markets get choppy, people hunt for yield in all the wrong places. They stretch credit quality. They chase the last hot sector. Or they freeze in money markets and call it a strategy.
I have found that the better path is quieter. Keep the core holdings. Then use a couple of well-understood contracts to harvest a little extra cash flow, enter positions on purpose, and put modest guardrails around risk. Nothing heroic. Just mechanics with rules.
We are taking the current portfolio and trying to use options to generate additional cash flow, establish positions more deliberately, and put some guardrails around risk.
– Wealth planning professionals discussing client unease
Last month offered a textbook backdrop. Broad equities slipped a fraction as oil firmed, longer-term yields climbed, and rate-cut hopes faded in and out. The ten-year note pushed to levels not seen in nearly two decades. The thirty-year printed yields that would have looked exotic a few years ago. That kind of tape makes people uneasy. Uneasiness is not a reason to invent a new personality as an investor. It is a reason to get paid for patience.
What Volatility Actually Hands You
Volatility is not only a threat. It is also the raw material of option premiums. When implied volatility rises, the market is charging more for insurance. Sellers of that insurance can collect more, provided they size positions like adults and pick underlyings they already understand.
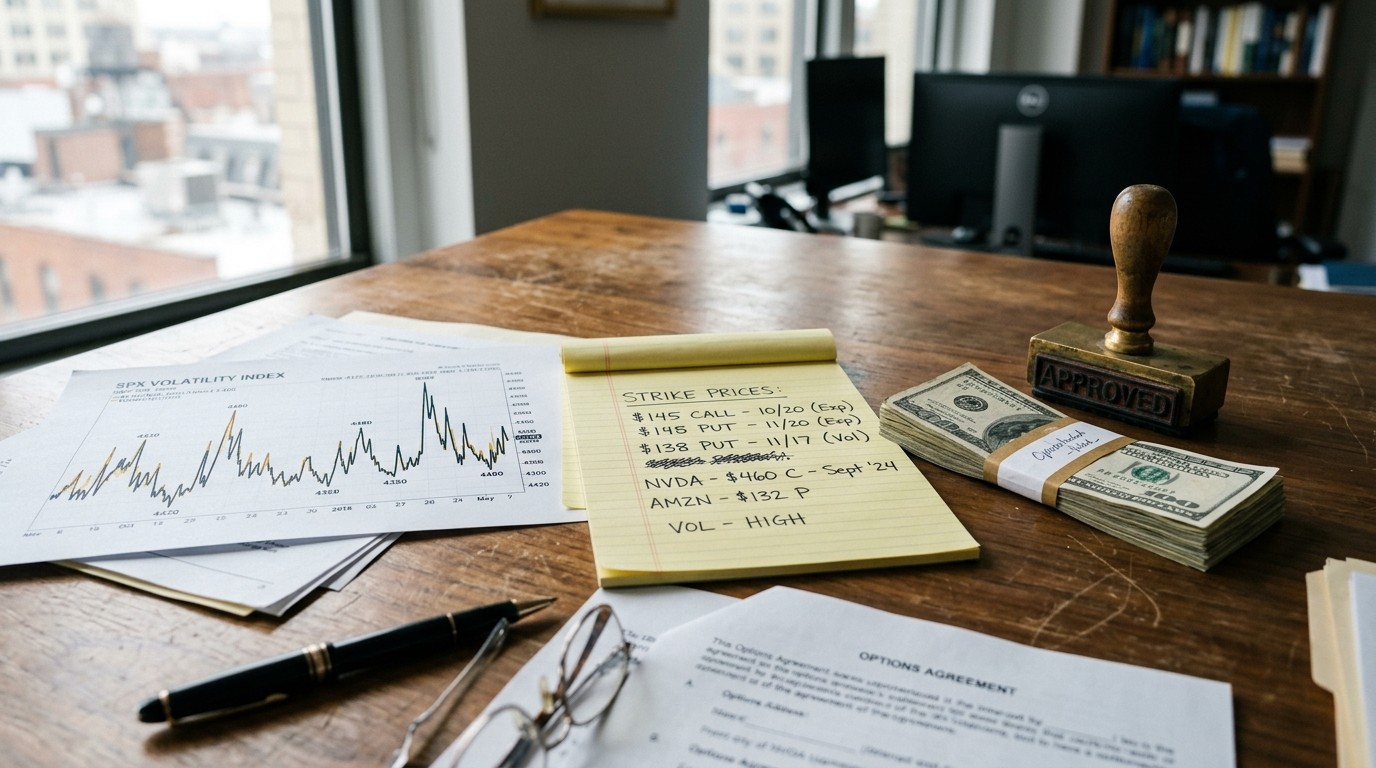
Perhaps the most interesting aspect is how ordinary this can look in a brokerage account. You already own a stock. You sell a call against it. Or you already have cash. You sell a put against a name you wanted anyway. The contract is short-dated. The strike is chosen with intent. The premium hits the account. Then you wait.
Sounds simple. It is simple until assignment shows up on a Friday afternoon and your plan was only half written. That is why the rest of this piece stays practical.
Covered Calls When You Already Own The Shares
A call gives the buyer the right to purchase shares at a set price by a set date. A covered call means you already hold the stock and you sell that right. If the shares stay below the strike through expiration, the option expires. You keep the premium. If the shares rally through the strike, you may have to deliver the stock. That is the deal. You sold upside for cash today.
In my experience, this works best on names that have already had a strong multi-year run and now trade in a range. Think quality companies tied to long themes, including those adjacent to artificial intelligence, where the first explosive move is behind them. You are not trying to call the next breakout. You are clipping a coupon while the market argues with itself.
- Own the shares first. No naked call selling for income seekers who sleep at night.
- Sell out-of-the-money strikes so you keep some room for a bounce.
- Prefer expirations you can actually watch, often a few weeks to a couple of months.
- Accept that a melt-up can take the stock away from you.
The catch is real. If the stock rips higher, you miss the extra surge above the strike. Some investors treat that as a failure. I treat it as the cost of the income. You cannot collect a premium and keep unlimited upside. Markets are not that generous.
Still, covered calls can feel almost too tidy when they work. Premium in. Dividend still arriving if the stock pays one. Shares still yours if the call dies unused. The account looks slightly more productive without a new thesis.
A Small Mental Model For Strike Selection
I like to ask one blunt question before selling the call. If I am assigned, will I be annoyed or relieved? If assignment would ruin a long-term compounder I refuse to sell, I do not write the call. If assignment at a higher price would be an acceptable harvest after a big run, the trade has a point.
Out-of-the-money strikes leave a cushion. At-the-money strikes pay more and cap you sooner. There is no free lunch hiding in the Greeks. Higher premium usually means you gave away more optionality.
Covered call checklist:
  Own the stock
  Choose a strike you can live with
  Size so one assignment is not a tax or concentration surprise
  Write down the exit if implied volatility collapses
Cash-Secured Puts When You Want To Buy Lower
Plenty of people are sitting on cash and money-market balances. Not because they found a perfect timing model. Because they feel uneasy. A cash-secured put is one way to get paid while you wait for a price you already like.
A put gives the buyer the right to sell shares to you at the strike. When you sell that put, you collect a premium. You also set aside enough cash to buy the shares if assigned. If the stock never trades down to your strike, the put expires. You keep the cash. You still do not own the stock. If it does trade down, congratulations and condolences in the same breath. You bought the name you wanted, just with a better effective cost after the premium.
The key with the cash-secured put is to make sure this is a stock you want to own at that price. You might get tested at that expiration cycle.
That last sentence is the whole strategy. Do not sell puts on a company you would not gladly hold through a messy quarter. Premium income is not compensation for owning junk you secretly dislike.
The ugly risk is a gap lower. The stock does not politely tag your strike. It opens far beneath it. You still buy at the strike. Your paper loss appears immediately. That is why cash must be real cash, not a vague intention, and why position size should respect the rest of the portfolio.
- Pick an underlying you already researched as a long-term holding.
- Set a strike at a price that would make you a willing buyer today.
- Park the full purchase amount in cash or cash-like reserves.
- Collect the premium and treat assignment as a successful entry, not an accident.
- If the stock rips higher and never tags the strike, accept the premium as payment for patience.
How These Two Trades Sit Together
Covered calls and cash-secured puts are cousins. One starts from stock. The other starts from cash. Both sell time. Both demand that you know the business underneath the ticker. Both can look brilliant in a sideways tape and sloppy in a one-way crash or melt-up.
| Strategy | Starting Position | Income Source | Main Trade-Off |
| Covered call | Long shares | Call premium | Capped upside if assigned |
| Cash-secured put | Reserved cash | Put premium | Obligation to buy after a drop |
| Core bonds and dividends | Income assets | Coupons and payouts | Rate and earnings risk without optionality overlays |
Notice what is missing from that table. There is no row that says “replace your bond sleeve with short options.” That would be a different article and, frankly, a worse one.
Guardrails Before You Click Sell
Using contracts adds risk even when the goal is income. You can heat a house with fire. You can also burn the house down. I have watched both versions in client conversations and in my own account years ago when I got sloppy with size.
Know what you own. Know why the strike exists. Know the tax lot you might deliver. Know whether assignment concentrates a single name past your comfort. If you cannot explain the trade in two spoken sentences, you are not ready.
- Limit overlay income to a slice of the portfolio, not the whole plan.
- Avoid stacking short options into one sector just because premiums look rich.
- Watch earnings dates. A cheap-looking premium can be expensive after a report.
- Keep a written rule for rolling, closing, or taking assignment.
Rolling is not magic. Closing is not failure. Assignment is not a moral verdict. They are just outcomes of a contract you sold on purpose.
When The Tape Gets Bumpy, Process Beats Prediction
Higher oil, firmer long yields, and mixed signals from policy makers can make any month feel like a referendum on your entire net worth. It is not. It is a sequence of prices. Income strategies work when they are boring. They fail when they become a way to express a market call you would not take with cash equity.
I’ve found that the investors who last with these overlays treat premium as a modest raise, not a new identity. They still hold quality dividend payers. They still own ballast. They still rebalance. The option just sits on top like a small extra lease payment on assets they already understand.
Is that exciting? Rarely. Does it help when cash feels sterile and stocks feel expensive at the same time? Often enough to be worth the paperwork.
Practical Scenarios Without The Heroics
Imagine a long-held industrial or technology name that has gone nowhere for two quarters after a huge prior advance. Selling a modestly out-of-the-money call can turn dead time into a little cash. If the stock finally breaks out, you sell at a price you pre-approved. If it does not, you keep collecting.
Now imagine an exchange-traded fund you have wanted on a pullback. Cash is already sitting there earning something. Selling a put below the market turns the wait into a paid stand. If you are assigned, the fund enters at a net price you liked. If you are not, the premium is the consolation prize.
Neither story requires a crystal ball. Both require homework on the underlying and enough liquidity to handle assignment without a fire drill.
Taxes, Friction, And The Unromantic Details
Premiums can be short-term in character. Assignment can trigger gains on shares you have held for years. Commissions are smaller than they used to be, yet they still exist in the background. Bid-ask spreads on quieter names can eat the edge. These details will not trend on social media. They will decide whether the strategy is worth the effort in a taxable account.
If you work with an advisor, ask how overlays sit inside the broader plan. If you do this yourself, keep a simple journal. Date, ticker, strike, premium, thesis, max pain. Review it quarterly. Patterns appear faster than opinions do.
What This Is Not
This is not a license to sell options on anything with a fat premium. It is not a replacement for emergency cash. It is not a hedge that removes drawdowns. Short calls and puts still leave you exposed to the direction of the underlying. They just change the payoff shape and add a cash credit up front.
If someone promises “steady yield with no risk,” walk away. Markets do not sell that product. They sell trade-offs with better and worse packaging.
A Calm Way To Use A Nervous Month
Volatile stretches tempt people to do something dramatic. Sometimes the useful move is smaller. Keep the income assets. Write a covered call on a winner that has stalled. Sell a cash-secured put on a name you already wanted cheaper. Collect a premium. Live with the rules you wrote before the order ticket.
Will that solve every restless night? Of course not. It can, however, turn uneasiness into a defined process. And in months when stocks slip, yields jump, and cash piles up out of habit, a defined process is worth more than another prediction.
Start with one position. Keep it small. Read the contract like you mean it. If the first expiration feels clean, consider a second. If it feels sloppy, stop. Income that requires you to abandon common sense is not income. It is a story you will regret telling later.