
Have you noticed how energy conversations shift the moment the first cold night hits a city that spent all summer running fans? I have. One week people talk about cheaper oil and ships moving more freely. The next week they stare at gas storage charts and start doing mental math about heating bills. That swing is already happening across much of Europe, and it is arriving earlier than a lot of casual observers expected.
Why This Winter Feels Different Before It Even Starts
Oil headlines have been less frightening lately. More cargoes are moving through a vital Gulf waterway, and some desks now talk about prices cooling toward the mid-eighties by year-end. That is useful for drivers and for manufacturers that still live and die by crude. It is not the whole story. Natural gas is the fuel that keeps European homes warm and a surprising share of industry online. Storage, not just oil, is the number that matters when November turns raw.
I keep coming back to a simple observation. Mild winters gave governments breathing room for several seasons. Inventories held up. Panic stayed in the background. This year that cushion looks thinner. A record-hot summer pulled more power for cooling, even in places where air conditioning used to be rare. Gas that might have sat in caverns was burned instead. Now the five-year comparison looks uncomfortable, especially in Germany and France.
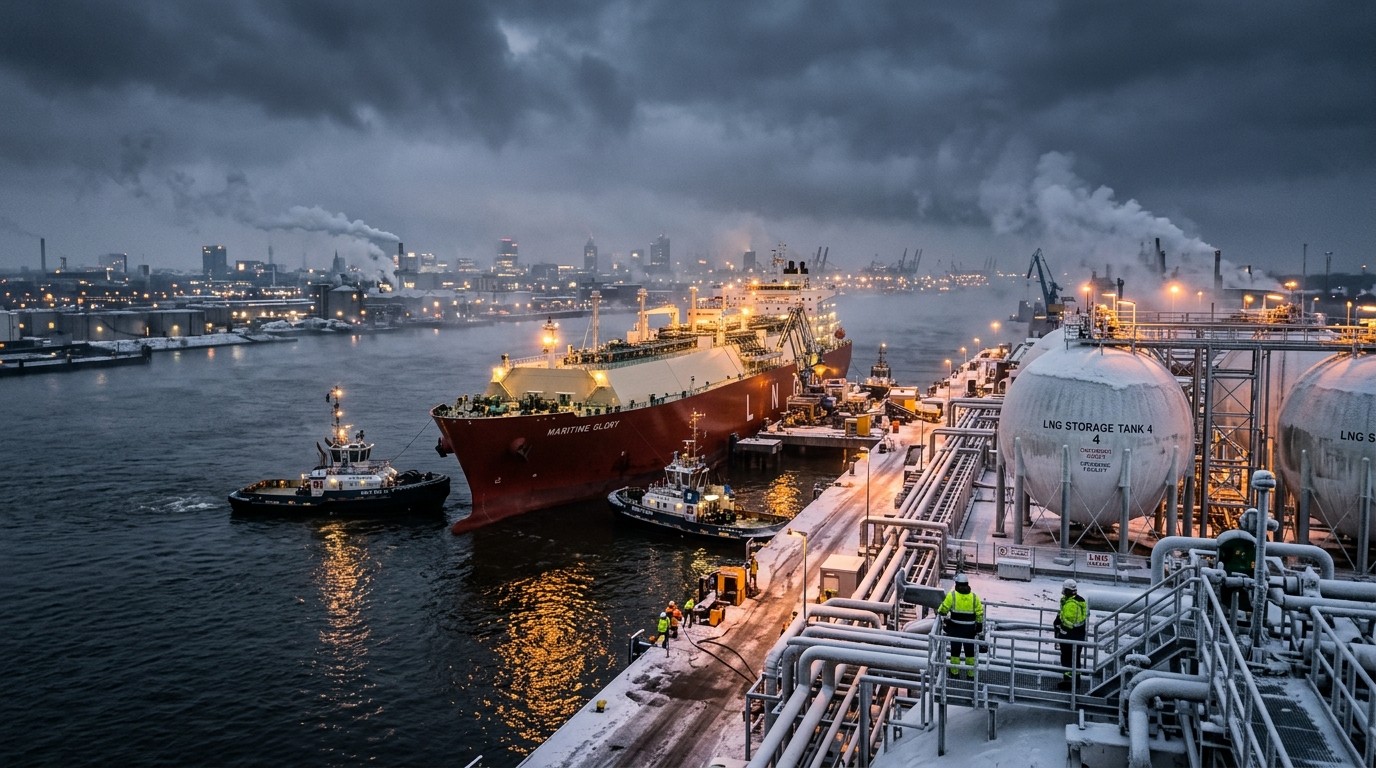
Officials still say supply is stable. In a narrow sense they are right. Lights are on. Factories are running. What they do not always emphasize is how much of that stability now rides on ships leaving the US Gulf Coast. American liquefied natural gas has become the backup generator for a continent that spent years trying to rewrite its energy mix and then discovered winter does not negotiate.
Oil Relief Is Real, But It Is Not A Full Reset
Ship traffic through the Strait has improved after a rough stretch. Exports from the wider Gulf region have climbed back toward earlier averages after a sharp September jump. When tankers pass with fewer delays, crude balances loosen and paper markets often follow. That is the part traders like to celebrate first.
Still, I refuse to treat an international waterway as something one government can lock and unlock like a front door. Threats can raise insurance costs and scare crews. They can slow traffic. They cannot legally convert a public sea lane into private property. The language around “reopening” is sloppy, and sloppy language leads to sloppy forecasts.
Better oil flows can take the edge off inflation and import bills, yet they do not refill European gas caverns on their own.
Fuel products can stay tight even when crude looks healthier. Distillate is a good example. If refiners hesitate or if product tankers face extra friction, diesel markets can stay jumpy while the crude screen looks almost calm. That split matters for Europe, where heating oil and industrial fuel still sit close to the political nerve.
The Storage Gap Europe Cannot Shrug Off
Storage is not a trivia chart. It is a winter insurance policy. When inventories sit below the five-year band, every cold snap becomes a bidding contest. Households do not feel that contest immediately if utilities bought early. Spot buyers do. Power plants that need extra molecules in January feel it too.
Western Europe just lived through a summer that smashed old heat records. Cooling demand is no longer a footnote. Offices, hospitals, and data rooms pull hard when the air turns heavy. Gas-fired generation often fills the gap when wind slacks off. That extra burn shows up months later as a lower starting line for winter.
Germany looks a touch worse than the broader union average. France is not in a comfortable spot either. Leaders can repeat that the system is fine. Markets hear something else when October contracts trade at a premium that would have looked extreme only a few winters ago. On one recent reading, near-term European gas futures sat more than twice as high as a later winter month. That curve is a warning, not a curiosity.
- Lower storage versus the five-year average leaves less room for a harsh January.
- Hot-summer power burn reduced the usual refill cushion.
- Spot LNG cargoes must compete with Asian buyers willing to pay up.
- Shipping costs can stack on top of the molecule price itself.
Perhaps the most interesting aspect is how quickly public language drifts toward comfort while private buyers quietly lock extra supply. I have found that gap between speeches and procurement is where investors should spend more time.
American LNG Is Doing Heavy Lifting
Call it a modern energy Marshall Plan if you want. The label is dramatic, but the physical reality is blunt. Liquefaction plants in Texas, Louisiana, and neighboring Gulf states turn abundant US gas into cargoes that Europe can actually use. Without those ships, the “stable supply” talking point would sound a lot thinner.
Europe still takes Russian molecules by sea even after pipeline drama that once dominated every front page. That fact surprises people who assumed the chapter was closed. It is not. Political calendars talk about cutting remaining volumes on a tidy schedule. Weather and voter patience rarely follow tidy schedules. If homes go cold, contracts have a way of stretching.
Qatari disruptions, when they happen, only raise the premium on US flexibility. The United States has more gas than it can currently export. That surplus is a strategic asset. It is also a listed-market story. Companies that own trains, offtake, and shipping optionality sit closest to European scarcity.
Two Direct US Names And Two Quieter Giants
If you want the cleanest expression of the theme, start with dedicated exporters. Cheniere Energy is the established US liquefaction name most investors already know. Venture Global is the newer, more concentrated bet on additional export capacity coming to market. Both live and die by utilization, contract quality, and the spread between cheap US feedstock and overseas prices.
Less obvious, at least for US-only screeners, are the European majors that control large slices of American LNG capacity. TotalEnergies and Shell sit in that camp. They are not pure-play exporters, which can frustrate traders who want a single-factor trade. They do bring balance sheets, trading desks, and the ability to steer cargoes toward the highest netback. In a tight winter, that optionality is not decorative.
| Name | Role In The Theme | What To Watch |
| Cheniere Energy | Core US liquefaction platform | Train utilization and long-term offtake |
| Venture Global | Growth-heavy export capacity | Project delivery and contract conversion |
| TotalEnergies | Major holder of US LNG exposure | Gas price realization and cash returns |
| Shell | Integrated trading and LNG portfolio | Cargo steering and margin capture |
I am not handing out a buy button. Capacity owners can still stumble on construction, legal fights, or a sudden warm winter that flattens the curve. What I am saying is the physical bottleneck is clear enough that these names deserve a place on the watchlist while Europe argues with its own inventory.
Why Analysts Are Warming To The Broader Energy Complex
Research desks have started to lift European gas assumptions by large percentages for the rest of this year and next. Some notes also nudge oil and refining-margin views higher. When those revisions land together, cash-flow models for integrated companies jump. Buyback capacity follows. That is the mechanism behind fresh “buy” language on names such as BP and TotalEnergies, with constructive stances kept on Shell, Repsol, and Chevron.
One shop even sketched roughly twenty percent upside across its favored energy book. Take that with the usual grain of salt. Price targets are opinions wearing a spreadsheet. The more useful detail is the admission that shipping risk around the Gulf may keep sputtering. Base cases now include repeated breakdowns and messy uncertainty, even while volumes grind higher. That is a more honest frame than a clean “problem solved” slide.
BP is getting a second look for company-specific reasons as well. After years of strategic zigzags, the firm is leaning back toward the oil and gas engine that actually funds the rest of the brochure. A large offshore find in Brazil’s Bumerangue block is being described as the company’s biggest discovery in a quarter century. New leadership with deep operating and finance experience is part of the pitch. The open question is speed. Can the reset happen fast enough for investors who already waited through several strategy seasons?
Simplification only works if the company keeps its foot on the operational gas pedal. Discovery headlines fade if barrels stay in the ground too long.
In my experience, energy turnarounds look obvious only after the stock has already moved. The boring work is wells, costs, and consistent capital returns. The exciting work is a map with a new yellow blob in deep water. You need both.
Price Versus Supply Is The Real Political Risk
Supply can be “adequate” on a spreadsheet and still feel brutal at the meter. That is the second shock. Even when utilities hedged early, any residual spot need collides with Asia in the same cargo auction. Freight rates pile on. The household does not care which line item did the damage. The bill just looks larger.
European industry has already lived through a stretch where power costs ate competitiveness. Energy poverty is not a slogan in parts of the United Kingdom. Families have had to weigh heat against groceries. That memory does not vanish because one oil benchmark eased for a fortnight.
Would another mild winter help? Of course. It would protect storage and give refill crews a head start for the following year. Hoping for weather is not a policy. It is a coin flip dressed as strategy. Investors should assume mean-reverting cold at least once in the next two seasons and ask which balance sheets survive that path.
A Practical Way To Think About Positioning
You do not need to bet the house on a polar vortex. You do need a framework. I like to separate the theme into three layers and size them differently.
- Direct US liquefaction exposure for the tightest link to European scarcity.
- Integrated majors with LNG trading reach and shareholder-return capacity.
- Quality oil producers that benefit if crude stays firmer than the relief narrative implies.
Layer one is more volatile. Export stories can rip on a cold forecast and sag on a warm weekend. Layer two is slower, but cash returns can cushion the wait. Layer three is a hedge against the idea that oil calm is permanent. None of this replaces risk limits. Energy remains a cyclical neighborhood. Position size is the adult in the room.
Watch the weekly storage prints, the prompt-versus-forward gas spread, and the number of US cargoes pointed at Northwest Europe versus Asia. Those three tell you more than a dozen speeches. If storage keeps lagging while the curve stays backwardated into winter, the exporter thesis stays alive. If a warm December rebuilds inventories fast, take the win and tighten stops.
What Could Break The Story
A durable stretch of easy shipping and a gentle winter would take heat out of European gas. New liquefaction arriving on time anywhere in the Atlantic basin would do the same over a longer horizon. A sharp US production stall would work in the opposite direction, lifting feedstock costs and squeezing exporter margins even if overseas prices stay high.
Policy risk sits in the middle. Export permitting, destination restrictions, and political fights over who “deserves” molecules can all scramble a clean trade. So can a sudden ceasefire premium that collapses freight and insurance in a week. Markets love a peace headline. Physical systems move slower than headlines.
There is also the human factor inside companies. A major project delay, a legal cloud over a new exporter, or a capital-return pause at a major can knock the equity story even if the commodity thesis remains intact. Tickers are not the same thing as molecules. Keep that distinction honest.
The Grid, The Unexpected, And The Noise Around The Edges
Winter energy is never only about one fuel. Grid attacks, delayed nuclear outages, weak wind weeks, and last-minute diesel stock decisions can all pile onto the same cold front. Far-off project debates, including Arctic export ideas that one government loves and another questions, add another layer of politics. None of that should distract from the core: Europe starts this season with less stored gas than recent history and a heavier dependence on seaborne supply.
Even the lighter headlines tell you energy has crawled into everyday culture. A fuel-cell firm slapping its name on a basketball jersey is a small thing. It is also a sign that power reliability is no longer a back-office topic. When sports marketing and generation equipment share a press release, the scarcity conversation has left the specialist corner.
I sat with that thought longer than I expected. Markets sometimes price electrons as if they were a software feature. They are not. They are steel, weather, ships, and politics. Forget that and you will keep being surprised by “sudden” winter crunches that were visible on a storage chart in early autumn.
A Longer View For Patient Capital
US gas abundance is not a one-winter story. Liquefaction capacity is still growing. Europe’s own production is not about to surge. Pipeline politics remain messy. That combination supports a multi-year role for Atlantic LNG even if this particular winter turns out milder than feared.
The investment mistake is treating every cold forecast as a reason to abandon process. The other mistake is treating every warm week as proof the structural shortage is fake. Both are lazy. A better habit is to map contracts, capacity additions, and storage targets on a twelve-to-twenty-four-month calendar and then let weather be a tactical overlay rather than the entire thesis.
BP’s Brazilian find, if it progresses cleanly, is a reminder that oil supply still has surprises on the constructive side. That matters if you worry that energy equities only work when something is on fire. Growth barrels plus disciplined spending is a different pitch from crisis trading. It is also harder to execute. That is why leadership credibility keeps showing up in every serious note on the stock.
TotalEnergies remains, in my view, one of the more important voices in the global gas conversation because the company sits across producing countries, LNG trains, and European demand. When that kind of operator talks about tightness, I listen even if I discount the salesmanship. Operators see cargo slates. Commentators see charts.
How I Would Brief A Cautious Reader
Start with the physical facts. European storage is below the recent average after a punishing summer of power burn. Oil flows look healthier than they did during the worst shipping scares. Those two sentences can be true at the same time. Build the portfolio around that split instead of forcing a single mood onto every ticker.
Give US LNG exporters a defined sleeve, not a blank check. Pair them with integrated names if you want dividends and trading optionality. Keep a written invalidation level: a decisive storage rebuild, a collapse in the winter gas curve, or a project-specific blowup. If none of those hit, let the position work through the first real cold period instead of reacting to every forecast map.
And keep some humility. Energy markets punish certainty. I have been early on tightness before and looked silly for a month, then less silly when the first Arctic blast arrived. I have also watched a “must-own winter” fade into a shrug. The difference is usually preparation versus prediction. Preparation travels better.
Simple winter checklist:
  Storage versus five-year band
  Prompt gas versus later months
  US cargo destinations
  Freight and insurance premia
  Company-specific project risk
If those five stay supportive, the theme is more than a headline. If they roll over together, step aside. No article, including this one, is a substitute for that weekly homework.
The Human Weather Under The Market Weather
It is easy to write about tickers and forget the street-level version of the same story. A factory manager in Bavaria does not care which US terminal loaded the cargo. A renter in Manchester does not care how analysts revised a 2027 gas deck. They care whether the radiator works without wrecking the monthly budget. That pressure is why governments talk about stability even when charts look tired. It is also why exporters with reliable trains hold quiet leverage.
I do not enjoy rooting for expensive winters. Nobody should. The investment angle exists because the physical system is tight, not because tightness is morally convenient. If policy, weather, and new capacity ease the squeeze, households win and some trades lose. That is an acceptable outcome. Markets are not a charity, but they should not require suffering to justify a thesis either.
Until the storage gap closes in a convincing way, though, the map stays simple. Europe needs molecules. The United States can send them. Companies that turn Gulf gas into shippable energy sit in the middle of that exchange. Oil names with fresh barrels and cleaner strategies can ride the same broader bid if crude does not roll over as fast as the relief camp hopes.
So here is where I land after chewing on the same charts for too many evenings. Do not confuse a calmer oil tape with a finished European winter. Do not treat every LNG ticker as a lottery ticket. Do watch storage like a hawk. And if the first hard freeze arrives with inventories still thin, you will not need a complicated model to understand why those US export names start moving first.