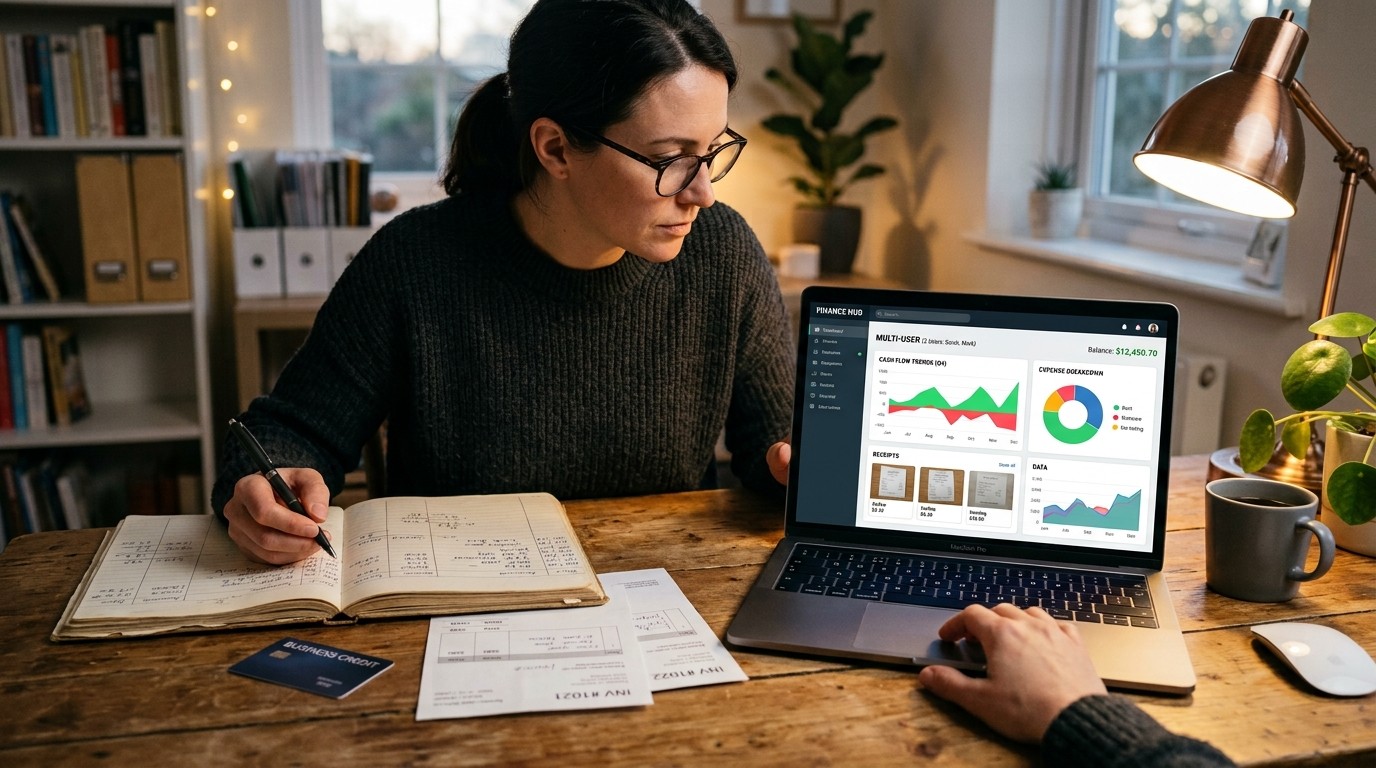

I still remember the week a freelancer friend asked me, almost sheepishly, whether paying for accounting software was a grown-up tax or just another subscription dressed as responsibility. She had three clients, one checking account, and a spreadsheet that looked like it had survived a storm. Free bookkeeping sounded like a gift. Then the fourth invoice bounced off a monthly cap, her accountant could not log in, and the “gift” started looking like a ceiling. That is the real fork most owners miss: QuickBooks Free can keep a simple shop honest, while QuickBooks Online is built for the moment the shop stops being simple.
QuickBooks Free Versus QuickBooks Online For Real Businesses
Let me be direct. Plenty of people treat accounting software like gym memberships. They buy the fancy plan, ignore half the buttons, and feel virtuous. Others cling to free forever and then spend April reconstructing receipts from email threads. Neither path is smart. The better question is not “which brand is best.” It is “what volume, what team, and what level of financial detail do I actually need this month.”
QuickBooks Free sits inside the same family as the paid product. That matters more than marketing copy admits. If you start free and later upgrade, your history, categories, and workflow do not vanish into a CSV graveyard. I have seen owners delay software for years because they feared a messy migration. Here, the migration is the least dramatic part of the story.
Still, free is not “paid with the price tag peeled off.” Caps exist. User seats exist. Report depth exists. Payment tools exist with fees attached. Pretending otherwise is how people get surprised mid-invoice.
What The Free Plan Actually Gives You
Think of the free tier as a clean starter kitchen. You can cook. You cannot run a catering company out of it without bumping into counters.
On the money side, sign-up does not demand a card. That lowers the psychological barrier, which I like. Too many tools bait you with a trial and then hide cancellation under three menus. Here, free means free to start.
Core work is straightforward. You can pull transactions from one bank account. You can send a limited number of estimates and invoices unless you qualify for and turn on the built-in payments option, which can unlock more invoicing. You can accept cards, digital wallets, and bank transfers, with processing fees. You can run a profit and loss view, a balance sheet, and quick transaction snapshots. You can track a small number of receipts and mileage entries each month. You can manage one 1099 contractor.
Security is not the bargain-bin version. Encryption and multi-factor checks sit on the same infrastructure used for heavier plans. That is reassuring if you have ever emailed a spreadsheet of client payments to yourself at 11 p.m.
Free software is only cheap if the limits match the way you actually bill, spend, and file.
Availability is browser plus mobile apps. You will not be locked to a desktop relic from 2009. For a consultant on a laptop in a coffee shop, that is enough.
Who Should Stay On QuickBooks Free
I would keep someone on free if four conditions line up. One person. Low monthly volume. Basic questions about profit and cash. A fierce desire to keep overhead thin while the business is still finding its shape.
You Are Truly A One-Person Shop
The free product is built around a single user. If you are a designer, coach, tutor, or independent contractor who does not need an outside bookkeeper inside the file, that constraint is not a constraint. It is the shape of your week.
Spreadsheets still work, sure. They also hide formulas, break when you sort the wrong column, and turn tax time into archaeology. Automated categorization is not magic, but it beats typing every coffee run by hand.
Your Month Is Quiet Enough For The Caps
Limits feel theoretical until they are not. Two invoices a month is plenty if you bill on retainers. It is a joke if you invoice weekly project slices. Receipt and trip caps are fine if you rarely travel and rarely photograph crumpled paper. They become friction the first time you do a conference week and a supply run in the same billing cycle.
Payments change the math. If you enable the official payment rail and qualify, invoicing can open up. Fees still apply. Dispute protection on card charges can cover a meaningful annual amount, which is not nothing when a client decides the work “did not feel right” after delivery.
- One linked bank account is enough when all money hits the same place.
- Two invoices can work for retainer-heavy freelancers.
- A handful of receipts and trips suits local, low-travel work.
- One contractor seat fits a solo owner who only hires help occasionally.
You Only Need A Clear Picture, Not A Command Center
Some owners want dashboards that would impress a board. Most early businesses need three answers. Did I make money. Do I owe money. What moved in this account last week. Profit and loss, a balance sheet, and a quick account drill-down cover that.
I have found that people upgrade for vanity reports long before they upgrade for necessity. Resist that. A pretty chart that nobody uses is still an expense.
You Are Guarding Cash Like It Matters
Starting costs pile up fast. Tools, ads, insurance, a decent laptop. Free bookkeeping is one less recurring line while you test whether clients actually pay. When growth arrives, the paid path is waiting, and the books can travel with you.
That continuity is the underrated feature. Switching ecosystems later is how people lose six months of messy categories and then pay someone to clean the mess.
Where QuickBooks Online Pulls Ahead
Paid plans are not a personality upgrade. They are capacity. More people in the file. More accounts. More automation. More ways to see which project actually made money after you stop guessing.
Pricing moves with promotions. Limited-time discounts show up often enough that waiting a week for a sale is not a moral failing. Features matter more than the first invoice from the software company.
| Need | Free Fit | Online Fit |
| Users in the books | One person | Team plus accountant access |
| Bank connections | Single account | Banks, cards, and extra apps |
| Invoicing volume | Tight monthly caps unless payments unlock more | Built for regular client billing |
| Reports | Core statements | Custom views, budgets, project profit |
| Team and payroll | One contractor lane | More users and payroll tools |
| Day-to-day capture | Limited receipts and trips | Ongoing expense and mileage tracking |
You Need Your Accountant Inside The File
This is the upgrade trigger I see most often, and it is not glamorous. A tax pro does not want a zip file of screenshots. They want a live set of books with permissions. Free stops at one user. Paid tiers let you collaborate instead of playing email ping-pong with statements.
If you already pay a bookkeeper, forcing them to work around a one-seat wall is false economy. Their hourly rate will eat any subscription you “saved.”
You Keep Hitting The Ceiling
Multiple bank accounts. A business card plus a checking account plus a savings sweep. Invoices that go out like clockwork to a roster of clients. That is not a free-tier lifestyle.
Perhaps the most interesting aspect is how quietly the pain arrives. You do not wake up one morning as a corporation. You just send invoice thirteen and the software shrugs. Or you open a second account for taxes and cannot connect it. That shrug is your signal.
You Want Sharper Financial Questions
Growth changes the questions. Not “did I profit this quarter,” but “which service line paid for the slow one.” Not “what did I spend,” but “what did this project really cost after contractor hours and software.” Paid plans add budgeting, project profitability, inventory tools on higher tiers, and reports you can actually shape.
Inventory is the classic example. If you sell physical goods, guessing stock from memory is how you oversell a size or sit on dead product. Service businesses feel the same pinch with projects that look profitable until you assign real time to them.
You Want Rules, Recurring Work, And App Connections
Free already categorizes, tracks income and spend, and helps reconcile a single account. Paid builds on that with bill management, recurring invoices, bank rules that stop you from tagging the same vendor wrong every week, and connections to commerce and payment tools so you are not exporting CSVs like it is 2014.
In my experience, bank rules are the feature people underestimate. Ten minutes of setup saves an hour of cleanup every month. That is not exciting. It is adult.
You Have Employees, Not Just A Side Hustle
One contractor is a different planet from a staff of five plus payroll. Paid plans stretch to many users and add payroll capability. If people depend on you for wages, you have outgrown the “keep it tiny” phase whether your ego likes that or not.
You Work From The Phone More Than The Desk
Mobile access exists in the broader product family, and paid plans lean into the habit of sending an invoice between meetings, snapping a receipt in a parking lot, or checking month-to-date profit while you wait for a client. If your office is a bag and a calendar, that habit is not a luxury.
A Practical Way To Decide Without Overthinking
I like a blunt checklist more than a personality quiz.
- Count users who must touch the books this month, including your tax person.
- Count invoices you expect to send, not the number you hope to send.
- Count bank and card accounts that hold business money.
- Count employees and regular contractors.
- Ask whether you need project profit, inventory, or budgets to make a decision this quarter.
If the answers are one, few, one, none, and no, stay free and stop apologizing. If two or more answers jump, pay. Waiting for a perfect moment is how people enter tax season with a shoebox and a story.
Simple decision sketch:
  Stay free: solo + low volume + one account + basic reports
  Upgrade: extra users + extra accounts + heavy invoicing + payroll or inventory
  Revisit every quarter, not every mood
Invoicing, Payments, And The Quiet Cost Of Getting Paid
Owners obsess over software price and ignore collection friction. An unpaid invoice is more expensive than most monthly plans. Free can still collect through cards, wallets, and bank pulls. Fees exist. They always exist. The question is whether clients pay faster when the button is in the invoice.
Unlimited invoicing through payments is attractive, but it is not a loophole that deletes math. You are trading a software fee for processing fees and, if you qualify, a smoother billing rhythm. Run the numbers on your average ticket size. A high-ticket consultant feels fees differently than a photographer billing small sessions all month.
Dispute protection on card payments is the unsexy safety net. Most people never need it until they do. I would rather have it sitting there than write a blog post about a chargeback after the fact.
Reports That Help Versus Reports That Decorate
A profit and loss statement answers the dinner-table question: did this work make money. A balance sheet answers the slightly more adult question: what do I own and owe. Quick reports scratch an itch when you need to see one account fast.
Paid reporting is for the next layer. Budgets that you actually compare against. Project views that stop you from underpricing. Custom columns for the way you think, not the way a template thinks. If you are not going to look at those views, do not buy them to feel serious.
Software should answer the next decision you have to make, not the decision you wish you were important enough to make.
Taxes, Contractors, And April Reality
Free can handle a single contractor path. That is useful. It is not a full labor system. Mix-ups around 1099 work are how friendly help turns into a filing headache. If contractors multiply, or if W-2 payroll appears, you are no longer in “keep it cute” territory.
Clean categories all year beat heroic cleanup in March. Both tiers help if you use them weekly. Neither tier saves you if you dump a year of personal charges into the business feed and hope software will know which burrito was a meeting.
According to small-business advisors I trust, the owners who sleep in April are the ones who reconciled monthly, not the ones who bought the most features in January.
Security Without The Scare Tactics
Both lanes sit on serious encryption and access controls. Paid plans add permission levels so a helper does not see everything a founder sees. That is worth money the day you hire help you like but do not want inside payroll details.
Bank-grade language gets thrown around a lot. Translate it into habits. Unique password. Multi-factor on. No shared logins on a sticky note. Software cannot fix sloppy access.
A Week In The Life On Each Plan
Monday on free: bank feed imports, you approve a handful of charges, you send one invoice, you glance at profit. Done. Tuesday you photograph two receipts. Wednesday nothing financial happens because you are doing the actual work. That week is a free-plan week.
Monday on paid: three invoices go out on a recurring template, a bill is scheduled, a bank rule tags ads spend, your bookkeeper leaves a note, you check project profit on the job that felt busy but paid poorly. That week is why people upgrade.
Notice the difference is not morality. It is traffic.
Mistakes I Keep Seeing
First, mixing personal and business money in the one connected account, then blaming the software for messy categories. Open a dedicated account before you debate plans.
Second, staying free to “be frugal” while paying a human to rebuild books from screenshots. Frugal is not the same as cheap.
Third, buying a high tier because a comparison chart looked impressive. If you do not have inventory, do not romanticize inventory modules.
Fourth, never reviewing the feed. Automation without a weekly glance is how subscriptions you forgot keep living in expense reports.
- Separate business banking before you pick a plan.
- Reconcile on a schedule, even if the schedule is Sunday night.
- Upgrade for people and volume, not for status.
- Use payments only after you understand the fee on your average invoice.
When Free Is A Temporary Home
I like free as a runway, not a religion. Use it to learn the rhythm of categories and invoices. Watch your own numbers for two or three months. The moment a second person needs in, or a second account becomes real, move. The product family is designed for that move. Take it.
There is a stubborn pride in doing everything on zero dollars. I get it. I also get the look on someone’s face when they realize they cannot add their accountant two weeks before a deadline. Pride is a poor close date.
How To Think About Growth Without Predicting The Next Five Years
You do not need a five-year forecast to choose software. You need this quarter’s operating reality. Are you hiring. Are you adding a sales channel that dumps transactions. Are you tired of typing the same invoice.
Choose for the business you are running on Thursday, with a bias toward the tools that will not punish you on Friday. That sounds obvious. It is not how people shop. They shop for the company they will describe at dinner parties.
If your work is still a single offer, a single account, and a single human, free is not a compromise. It is a match. If your work is a small team with moving parts, paying is not a betrayal of hustle culture. It is maintenance.
The Bottom Line I Would Give A Friend
Start free if you are solo, quiet, and allergic to extra bills. Learn the habit of reviewing transactions. Send the invoices you are allowed to send. Keep one contractor lane tidy. The day the limits pinch, or the day another professional needs a login, step into QuickBooks Online and take your history with you.
Do not romanticize either tier. Free is not a medal. Paid is not a personality. They are different sizes of the same toolbox. Pick the size that lets you stop thinking about bookkeeping and get back to the work that actually pays.
And if you are still unsure tonight, count last month’s invoices and last month’s bank accounts. The numbers will argue more honestly than a feature list ever will.