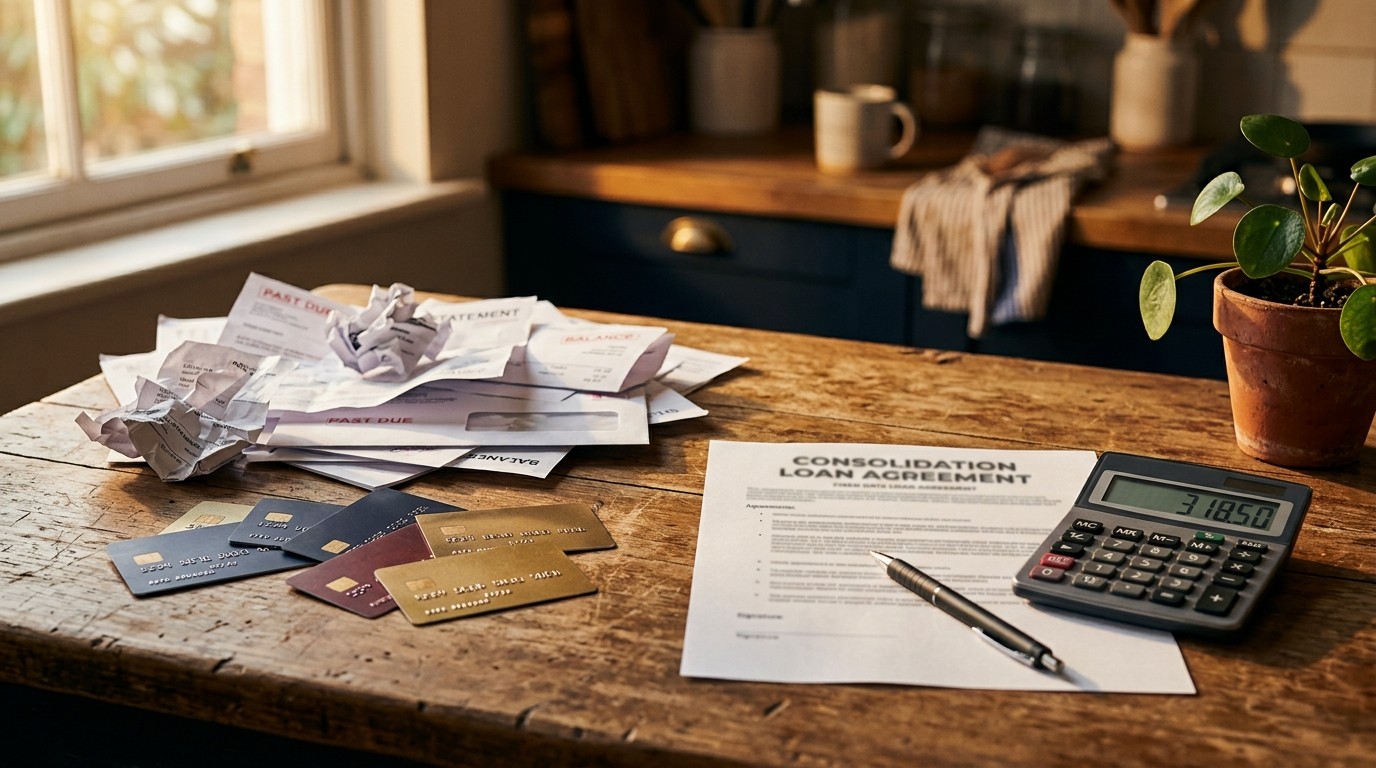

If you are carrying several high-interest balances and a steady paycheck, combining them into a single personal loan can lower what you send out each month and make the calendar less chaotic. If the new rate barely beats the old ones, or the repayment stretches so far that interest piles back up, the tidy payment is mostly cosmetic. Credit, income, and the habits that created the balances all decide which version you get.
When One Payment Is Actually A Better Deal
Consolidation, in plain terms, means taking several debts and replacing them with one new obligation, ideally at a lower interest rate and on a schedule you can actually keep. Most people do this with an unsecured personal loan. Some use a home-equity product. A smaller group moves balances onto a promotional card. The label on the product matters less than the math underneath it.
I have found that the people who walk away satisfied are rarely chasing a miracle rate. They want fewer due dates, a fixed payment, and a finish line they can see. That is a reasonable goal. Chaos has a cost. Missing a card minimum because you lost track of which account drafts on the 12th is how a manageable pile becomes a credit problem.
Who tends to come out ahead
A consolidation loan makes the most sense when a few conditions line up at the same time. Miss one, and the whole idea gets shakier.
- You have several card balances or other unsecured debts and you want them under one payment.
- Those balances sit at high rates, especially revolving credit that compounds when you carry a balance.
- Your income is steady enough that the new payment is realistic, not hopeful.
- Your credit is strong enough to qualify for a rate that is meaningfully lower than what you pay now.
- You can stop adding new debt once the old accounts are paid down or closed in practice, even if the cards stay open.
Notice what is not on that list. A stressful month is not a reason by itself. Neither is a slick preapproval email. The loan has to beat the status quo on total cost, or at least on a payment you will not miss, without quietly inflating what you owe over the life of the debt.
Households with mixed debt sometimes benefit too. A store card at a painful rate, a small medical balance on a payment plan, and a personal loan leftover from a move can all be candidates. Secured debts are a different conversation. Rolling a car note into an unsecured loan just to simplify can raise the rate and remove the asset tie, which is rarely the win people expect.
The trap of a longer runway
Here is the part that gets skipped in the pitch. A lower monthly number can still cost more. Stretch a balance from 24 months to 60, shave a few points off the rate, and the payment drops. The interest total may rise. That is not a trick. It is arithmetic.
Say you owe $12,000 across cards at an average 22 percent, and you are paying enough to clear it in about three years. A new loan at 13 percent over five years might feel like relief on the first statement. Run the totals before you sign. If the new loan does not cut the rate in a real way, a longer term is often an expensive form of breathing room.
A smaller payment is not the same thing as a cheaper debt. Term length is where consolidation quietly gets expensive.
Personal finance planners who review loan offers
Perhaps the most interesting aspect is how often borrowers optimize for the payment they can stomach this month and ignore the payoff date. Cash flow matters. So does the finish line. If you need the lower payment to avoid missed dues, that can still be rational, as long as you name the tradeoff instead of pretending the loan is a discount.
A quick comparison that keeps people honest
You do not need a spreadsheet degree. You need three numbers from your current debts and three from the offer: balance, rate, and months remaining if you keep paying what you pay now. Then compare total interest, not just the new autopay amount.
| Question to ask | Why it matters | Red flag |
| Is the new APR clearly lower? | Rate is the main reason to consolidate unsecured debt | A drop of a point or two on a much longer term |
| What is total interest over the full term? | This is the real price of the loan | You cannot get a payoff quote or amortization |
| Are there origination or late fees? | Fees can erase a modest rate win | A high upfront fee baked into the amount financed |
| Can you pay extra without penalty? | Extra payments are how you beat a long term | Prepayment penalties or fussy payoff rules |
| Will the lender pay creditors directly? | Direct payoff reduces the chance you spend the funds | A lump sum deposited with no plan to clear the cards |
If the offer fails two of those checks, pause. Shopping another lender is cheaper than living with a mediocre contract for five years.
Where people actually find consolidation loans
The market is crowded, and that is useful if you compare instead of grabbing the first banner. Online lenders, credit unions, banks, and some finance companies all originate personal loans aimed at paying off existing debt. The product is usually unsecured, fixed-rate, and installment-based, which means the payment stays put if you do not refinance later.
Speed is a selling point for a reason. Some lenders can approve and fund the same day if you complete signing early enough in the business day, and a few let you pick the funding date. That matters if a card payment is about to hit and you do not want another late mark. Speed is not a substitute for reading the promissory note. I would rather wait a day than miss an origination fee buried in the disclosure.
Credit unions deserve a longer look than they usually get. Membership rules can be broader than people assume, and pricing is often competitive for borrowers with solid histories. Banks you already use may not advertise the loudest rates, yet an existing relationship sometimes smooths underwriting. Online lenders win on convenience and on ranges that stretch from modest sums to six figures for well-qualified applicants.
What strong-credit borrowers should demand
If your credit sits in the good-to-excellent range, you are the customer these products were built for. Use that. Look for no origination fee, no late fee, and a clear right to pay extra or finish early without a penalty. Those terms are available. Settling for less because the application took four minutes is how good credit gets average pricing.
- Loan amounts often start around a few thousand and can reach well into five figures, sometimes up to $100,000 for qualified borrowers.
- Terms commonly run from two years to seven. A few lenders stretch much longer for specific purposes, which is flexibility and temptation in the same package.
- Autopay discounts of a fraction of a point show up often. Take them if the draft date matches your pay cycle.
- Co-borrowers are accepted by some lenders and refused by others. A stronger co-applicant can change the rate. It also ties another person to the debt.
Prequalification is worth using wherever it is offered, because a soft check lets you see a rate range before a hard inquiry. Not every lender allows it. If a company will not show you a rate without a full application, treat that as a preference, not a moral failing, and decide whether the possible pricing is worth the inquiry.
One practical snag: minimum loan sizes. A $5,000 floor is common. If you only need $2,200 to clear two small cards, forcing yourself up to the minimum means borrowing money you do not need. That is the opposite of consolidation. Either find a lender with a lower floor or pay the small balances directly and consolidate only what is large enough to justify a new contract.
When credit is thin, bruised, or nonexistent
Bad credit does not automatically close the door. It does change the price. Some lenders consider applicants with scores in the mid-500s. Others use models that look past the score at education, work history, income stability, and how cash has moved through your accounts. A few will consider a co-signer or co-borrower, which can improve approval odds and the rate you are offered.
Read the annual percentage rate carefully when an origination fee is involved. A quoted range that looks friendly can include a fee of several percent rolled into the amount you repay. You might receive less than the figure on the approval screen because the fee comes off the top, or you might repay a larger balance than the cash that reached your creditors. Either way, the fee is part of the cost. Compare APR, not the teaser interest rate alone.
In my experience, borrowers with weaker files get hurt less by a slightly higher rate than by a loan they cannot finish. A 60-month term at a steep APR, plus a fee, plus the same spending pattern, is how consolidation becomes a second chapter of the same story. If the only offers you see sit near the top of typical personal-loan ranges, run the total against a harder but shorter payoff on the cards. Sometimes the unglamorous path is cheaper.
Availability is another quiet limiter. Not every lender operates in every state, and some products exclude certain uses. If a rate discount is tied to the lender paying your creditors directly, that is often a feature worth taking. Direct payoff is one of the few structural guards against spending the proceeds.
Fees, discounts, and the fine print that moves the number
Origination fees, when they exist, commonly land somewhere between about 1 percent and 10 percent depending on credit and lender. Zero is better. A small fee can still be acceptable if the rate drop is large and you plan to keep the loan for most of the term. A large fee on a short payoff is harder to justify, because you do not have years of interest savings to amortize it.
Late fees sound minor until a rough month hits. Lenders that skip them are easier to live with. That is not a reason to pay a worse rate, but it belongs on the comparison list next to autopay discounts and rate cuts tied to a checking relationship or a membership perk. Those discounts often require you to keep meeting a condition, such as a direct deposit, or they disappear and the payment changes when the loan is re-amortized.
Before you accept:
  Rate with and without autopay
  Origination fee in dollars, not just percent
  Amount that actually reaches creditors
  Monthly payment
  Total of all payments
  Payoff date
  Penalty for paying early, if any
Rates move. A range you saw last season may not be the range you are offered today. Your actual rate will sit inside the lender’s band based on credit, income, debt load, and the purpose you select. Lowest advertised figures are reserved for the strongest files. If your offer is nowhere near the floor, that is normal, not a personal insult. It is also a signal to get a second and third quote.
Prep work that matters more than the lender logo
A certified financial planner I trust puts it bluntly: do not consolidate until you can see your real monthly spending, and do not take the loan without fixing the habits that built the balances. That sounds stern. It is also the difference between a tool and a delay.
Pull three months of transactions before you apply. Not the budget you wish you had. The one that already happened. Rent or mortgage, groceries, childcare, fuel, subscriptions you forgot, the takeout that became a line item. If the proposed payment only works on the wish version, you are setting up a missed draft.
Budgeting tools help here, especially if you are new to tracking. A free tier that categorizes transactions, shows income against spending, and flags subscriptions is enough for most people. Premium versions add bill negotiation, net-worth views, or cancellation help, usually for a monthly fee in the rough range of single to low double digits, sometimes with an annual option that lowers the monthly equivalent. Bill-negotiation services often take a large cut of first-year savings, sometimes more than half, and that fee may be nonrefundable if they succeed. Know that before you opt in.
If overspending is the pattern, look for an app that tells you what is left after bills and goals, and that warns you when a category is about to blow past its limit. Custom rules for specific merchants can be oddly effective. The coffee shop is rarely the whole problem. It is a visible stand-in for a dozen small leaks.
- List every debt: balance, rate, minimum, and due date.
- Add up what you actually pay, not just the minimums.
- Map fixed costs and a realistic variable budget for 30 days.
- Decide the maximum payment you can keep in a bad month, not a perfect one.
- Only then compare loan offers against that ceiling and against total interest.
Security is part of prep, too. Connecting accounts through a reputable aggregator means your bank login should not sit in the budgeting app itself. Look for encryption, tokenized access, and basic device locks. None of that makes a bad loan good. It does keep the research from creating a new problem.
The habit problem nobody underwrites
Lenders check income and credit. They do not move into your kitchen. After the loan funds and the cards drop to zero, the available credit is still there. That open limit is a gift to your utilization ratio and a trap if the spending pattern has not changed. Utilization falling can help your score. New balances climbing back up can erase the consolidation within a season.
Some people freeze cards in a literal block of ice, which is theatrical and occasionally effective. Others remove stored card numbers from shopping sites, lower limits, or keep one card for planned expenses and pay it in full. Closing every account can ding your score by shrinking available credit and, if the cards are old, by shortening average age. You do not have to close them. You do have to stop treating cleared balances as fresh spending money.
Consolidation rearranges the debt. It does not rearrange the calendar that created it.
Build a small cash buffer at the same time, even a few hundred dollars. The irony of consolidation is that people do it because money is tight, then a flat tire sends them back to a card. An emergency fund is not a luxury add-on. It is what keeps the new loan from becoming one more account in a pile. Start ugly and small if you must. Consistency beats a perfect target you never fund.
How the new loan can affect your credit
Expect a hard inquiry when you formally apply. A handful of rate shops in a short window for the same kind of loan are often treated more gently than scattered applications over months, but inquiries still exist. A new account can dip your score at first. Paying down revolving balances can lift it, because utilization is a heavy factor. On-time installment payments help over time.
The mix of credit types may shift, which is usually a minor effect. What hurts is a missed payment on the new loan after you used it to clean up the old ones. That is a fresh negative on a debt you chose. Autopay, aligned with payday, is the boring protection. So is a calendar reminder two days before the draft, in case the account is light.
If you are about to apply for a mortgage, timing matters more. A new personal loan changes your debt-to-income ratio. Paying off cards can help that ratio and your score, yet the inquiry and the new account are visible. Talk to the mortgage side before you consolidate if a home purchase is inside the next several months. Simplifying consumer debt right before underwriting is sometimes smart and sometimes a surprise nobody wants.
Alternatives that deserve a real look
A personal loan is not the only way to combine or attack high-rate debt. A balance-transfer card with a promotional zero-interest window can be cheaper if you can clear the balance before the promo ends and if the transfer fee, often a few percent, is smaller than the interest you would have paid. The risk is the cliff. Whatever remains when the promo expires can jump to a high ongoing rate, and the required payment during the promo may not retire the debt.
Home equity loans and lines can carry lower rates because your house secures them. That lower rate is not free. You are putting the roof in the deal. For credit-card debt, that trade is one I am slow to recommend unless the numbers are overwhelming and the repayment plan is short. Unsecured consumer debt should not casually become a threat to housing.
Nonprofit credit counseling can set up a debt management plan that lowers rates with participating creditors and rolls payments into one draft. You are not taking a new loan so much as entering a structured payoff. Fees exist, and not every creditor joins. For some households it beats a high-APR personal loan.
Then there is the unfashionable option: a self-managed avalanche or snowball. Avalanche puts extra money on the highest rate. Snowball puts it on the smallest balance for quicker wins. Neither requires a new creditor. Both require a surplus, which is exactly what many people do not have. If you do have even a modest surplus, compare that path before you pay an origination fee for the privilege of a single due date.
A worked example, rounded and imperfect
Imagine $18,000 spread across four cards, blended rate around 21 percent. Paying $700 a month gets you out in roughly three years, with interest in the mid four figures, give or take, depending on how the balances are split. A consolidation offer at 12 percent over five years might land near $400 a month. Relief, yes. Total interest can still land in a similar neighborhood, or higher, because the clock is longer.
Now change one variable. Same 12 percent loan, but you keep paying $700. You finish far sooner than 60 months, interest drops, and the single payment still simplifies the month. That is the version of consolidation I like. Use the lower required payment as a floor, not a target, if your budget can stretch. The contract allows the floor. Your plan can aim higher.
Change another variable. The only offer is 19 percent over six years with a 6 percent fee. The payment falls. The total cost does not cooperate. At that point the loan is a cash-flow tool, not a savings tool. Sometimes cash flow is the emergency. Name it that way, and keep the term as short as the budget allows.
Useful comparison: current total interest vs. new total interest vs. new total if you pay extra each monthRough figures are fine for a first pass. Before you sign, use the lender’s own amortization or a calculator you trust, with the fee included. Rounding errors should not decide a five-year contract, but they also should not scare you off a clearly better rate.
Red flags that should slow you down
Pressure is the first one. A legitimate installment loan does not need you to decide in the next nine minutes. Anyone asking for upfront fees paid to a person, rather than a disclosed origination fee inside a loan, is a different and worse category. So is any pitch that guarantees approval or tells you to ignore your budget.
- You cannot see the APR, term, fees, and payment on one disclosure before you agree.
- The lender will not explain whether creditors are paid directly.
- The term is so long that you will still be paying for purchases you cannot remember.
- You are borrowing extra “just in case” and have no separate savings plan.
- Your income is irregular and the payment assumes every month looks like your best month.
- You already consolidated once and the cards filled back up.
That last point stings, and it is common. A second consolidation is not forbidden. It is a sign to change the spending system, not just the creditor. Otherwise you are refinancing a habit.
Joint debt, partners, and the awkward conversation
Money stress leaks into relationships even when nobody meant it to. If the balances are shared, or one partner is about to co-sign, the loan is not a solo administrative task. Sit down with the same numbers you would show a skeptical friend. Who pays, what happens if someone loses hours at work, and whether the cards stay open are relationship questions wearing a finance costume.
Co-signing is a full obligation, not a character reference. If the primary borrower misses payments, the co-signer is on the hook and the credit damage is shared. I have seen helpful parents and partners walk into that role because the application felt like a formality. Read the note. Decide what “help” actually costs if the plan slips.
For couples who keep finances partly separate, consolidation can clarify or confuse. A loan in one name that pays off joint cards needs a written, boring agreement about reimbursement. Handshake plans dissolve during busy seasons. A shared calendar reminder and a shared view of the remaining balance do more for trust than a speech about responsibility.
Seasonal spending and the months that break plans
Holidays, back-to-school, annual insurance premiums, and summer travel are when consolidated borrowers relapse. The payment is automated, the cards look empty, and a “temporary” charge feels harmless. Build those months into the budget before you choose a term. If December always runs $600 hot, the loan payment has to survive December, not just March.
Irregular income needs a different buffer. Freelancers and commission workers often qualify based on average deposits, then struggle in a thin month. A payment sized to your average can still bounce in a slow one. Size it to a lower month and send extra when the good invoices land. That approach is less sleek and much more likely to stay current.
What to do in the first 30 days after funding
The dangerous window is right after the money moves. Confirm every creditor received the payoff. Snapshot the zero balances. Turn off stored payments that might still charge a card you think is clear. Set the new loan to autopay. Then schedule a 15-minute check on day 30 to verify nothing reappeared as a residual interest charge. Cards sometimes generate a last cycle of interest after you pay the statement balance. Pay that residual immediately so the account actually rests at zero.
Update your budget with the new single payment and delete the old minimums so you are not mentally spending money that is no longer free. If the payment dropped, assign the difference on purpose: extra to the loan, or a starter emergency fund, or both. Unassigned surplus has a way of becoming delivery orders.
Tell anyone who shares the household bills what changed. Confusion about which account is “the one we pay” causes missed drafts more often than bad intentions do. One named account, one date, one owner of the reminder. Simple systems survive busy weeks.
Refinancing later, without turning it into a hobby
Credit can improve after a year of on-time payments and lower card utilization. At that point a refinance of the consolidation loan itself may cut the rate again. Worth a look. Not worth chasing every quarter. Each new loan can add a fee, an inquiry, and a reset of the term if you are not careful. Refinance when the savings clearly beat the friction, then go back to paying the thing down.
If rates in the broader market fall and your credit has held, you may see offers. Compare them the same way you compared the first loan. A teaser payment means nothing if the term restarts at 72 months and you had 30 months left. Remaining interest versus new total interest is still the right duel.
A decision you can finish this weekend
You do not need a perfect financial life to answer the question. You need a page with your balances, a realistic payment ceiling, and two or three offers you can compare on APR, fees, term, and total cost. If a quote beats your current path and you have a plan for the cards, consolidation is a good idea. If it mostly rearranges due dates, it is optional at best.
Start with the spending picture, not the application. The loan cannot see the subscriptions, the gaps between paychecks, or the reason the cards grew. You can. That unglamorous hour of sorting transactions is the part that makes the rest of the math trustworthy.
And if the numbers say wait, waiting is a strategy. A few months of lower spending and a higher score can turn a mediocre offer into a useful one. Debt does not have to be solved in a single afternoon to be solved. It has to be cheaper, or at least survivable, on purpose.
One last filter I use when friends ask. If you would still want the loan after writing the total interest on a sticky note and putting it on the fridge, take it. If that note makes you wince, shop again or attack the balances directly. Either path can work. Only one of them should be yours.
]]>