

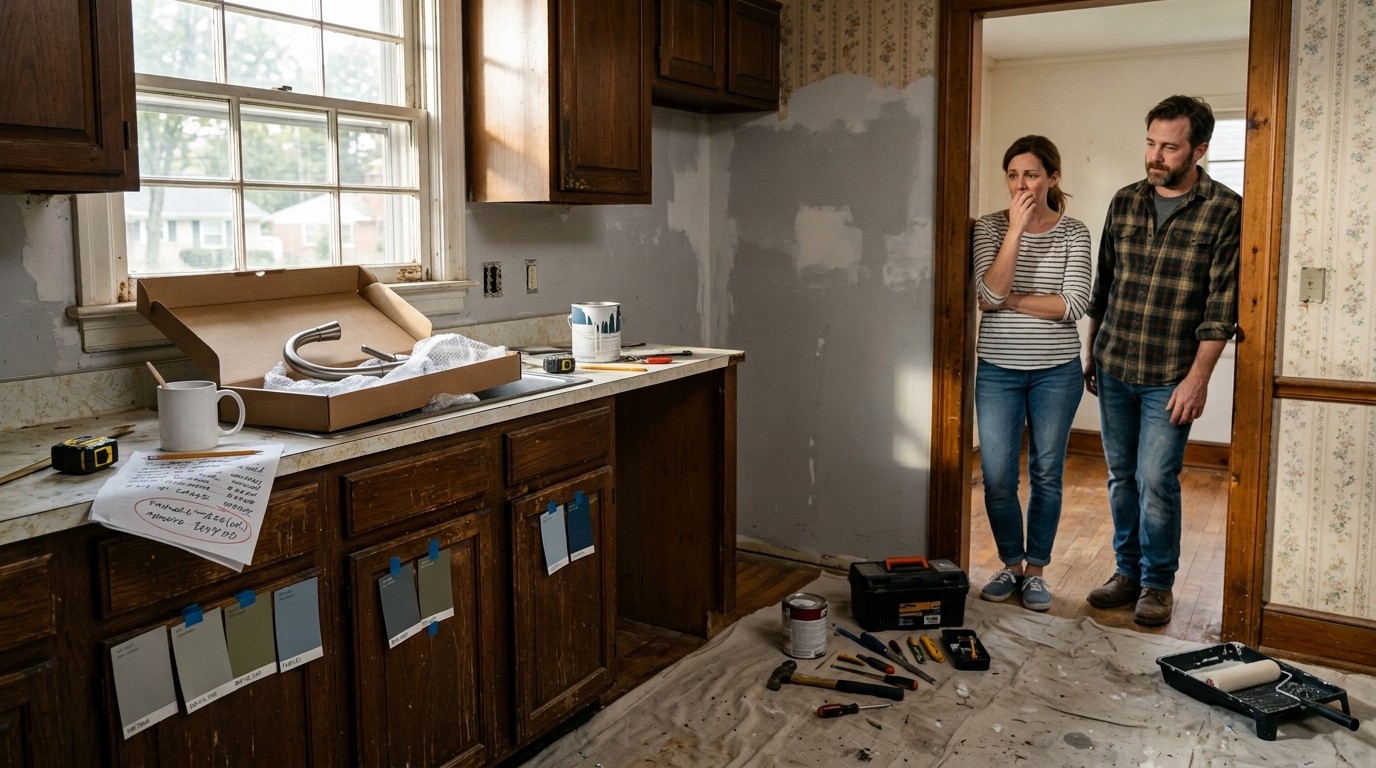
High Interest Rates Stall The Home Remodeling Dream

Homeowners are sitting on record equity and still cannot afford the kitchen they promised themselves. The rate that once felt like a gift is now the lock on the door, and the wait may last longer than anyone planned.
Financial market analysis from 03/10/2026. Market conditions may have changed since publication.
I keep hearing the same sentence from people who swore, three years ago, that the kitchen was next. Not next spring. Next. The cabinets were already chosen in a folder on the phone. Then the math changed, and the folder stayed closed. That is the strange position a lot of American households are in right now: they own the house, they have equity on paper, and they still cannot pay for the upgrade that would make staying feel like a choice instead of a stall. High interest rates did not just cool the market for buyers. They quietly foreclosed on the remodeling dream of people who never planned to move.
If you locked a mortgage somewhere between two and three percent, you already know the trap. Selling means giving that rate away. Borrowing against the house means paying something that feels, next to the old loan, almost insulting. So the deck waits. The walk-in closet stays a sketch. The shower that leaks a little on cold mornings gets a towel on the floor and a promise.
The Rate That Kept People Home Also Kept The Tools In The Garage
Staying put was supposed to be the smart move. In a lot of ways it still is. A cheap primary mortgage is one of the best financial assets a household can hold, and nobody sensible refinances out of it just to chase a newer floor plan. The trouble starts when the house itself needs money. Roofs do not care about your rate. Furnaces fail on the coldest morning of the year. Kitchens age whether or not you can finance a refresh.
Traditionally, the first tool for that gap was a home equity loan or a home equity line of credit. You borrowed against value you had already built, kept the cheap first mortgage, and paid for the project. That path is still open on paper. In practice, the price of using it has climbed high enough that plenty of owners run the numbers once and close the calculator.
Mortgage rates pushed above 7.5 percent this week, the highest reading in three years. Second-lien products do not live in a separate universe. When the cost of borrowing sits in that neighborhood, a discretionary remodel stops looking like an investment in daily life and starts looking like a luxury you explain to yourself later. I have watched friends do exactly that math at a kitchen table and land on the same shrug: not this year.
Locked In, And Not In The Flattering Sense
Economists have a tidy name for owners who will not sell because the old rate is too good. The lived version is messier. You are not frozen because you love every room. You are frozen because leaving would reprice your entire housing cost. A home-services marketplace that matches owners with contractors has been tracking the consequence: people are remaining in the same house about five years longer than they originally planned.
Five years is not a pause. It is a different life. Children age out of bedrooms. Remote work corners become permanent. The “right now” house turns, by default, into the forever home. That shift should have been a gift to remodelers. If you are not moving, you improve what you have. Instead, the same rate environment that blocks the move also blocks the upgrade.
People are holding the two-to-three percent mortgage as long as they can. Six to seven percent is closer to a normal range, and it is not coming back in a hurry. So the house they meant to leave becomes the house they have to live in.
Home-services industry observer
There is a quiet emotional cost in that. A house you chose for a chapter starts carrying chapters it was never built for. You feel it in the cramped office, the single bathroom, the deck that was fine when weekends were short. Wanting to fix those things is not vanity. It is how people make a long stay bearable. When the financing for that fix gets expensive, the frustration does not disappear. It just moves into the group chat.
Equity On Paper, Cash Nowhere Near The Project
Americans are sitting on a record pile of home equity. That sentence gets repeated because it sounds like wealth, and in a balance-sheet sense it is. Untapped equity does not pay a roofer. It does not order cabinets. It sits there, impressive and slightly useless, until someone is willing to borrow against it at a rate they can stand.
Originations of second mortgages and equity lines did rise nearly 20 percent in the second quarter compared with the first. That sounds like a thaw. Talk to people who watch how the money is actually used and the story changes. A fair share of those draws are not funding granite and tile. They are covering credit-card balances, bridging a thin month, keeping the household afloat. Survival borrowing and renovation borrowing are not the same behavior, even when they show up in the same product category.
A business-school professor who studies how consumers think about home equity put it bluntly, and I think he is right. If the cost of borrowing is that high, a lot of people simply will not do the project. He needs a kitchen himself. He has looked at the price and the rate and decided to wait. That wait, multiplied across neighborhoods, is the housing market in miniature.
What The Store Aisles Are Already Showing
You can argue with surveys. Point-of-sale data is harder to sweet-talk. A retail analytics firm that tracks what actually leaves the shelves at the two dominant home-improvement chains found a clear retreat in big-ticket renovation categories from September 2025 through August 2026. Declines ran from about 10 percent to 28 percent versus the prior year.
Shower stalls, kits, and enclosures were among the hardest hit. Sales dollars fell 21 percent. Unit sales fell even harder, about 28 percent. Bathtubs dropped a smaller but still real 10 percent in dollars and 12 percent in units. Pull-down kitchen faucets, averaging roughly $147, were down only about 3 percent. The pattern is almost rude in its clarity. The cheaper the item, the milder the pullback. Cross into the $300 to $700 range and the decline steepens.
Shower kits sit near a $700 average ticket. Bathtubs near $309. That is not a mansion renovation. That is the kind of project a middle household used to finance without a family meeting. When those tickets slide, you are not looking at a single chain having a bad season. Both major retailers moved the same way. That is consumer behavior, not a merchandising fluke.
| Project type | Rough average ticket | What the past year showed |
| Pull-down kitchen faucet | About $147 | Sales down roughly 3 percent |
| Bathtub | About $309 | Dollars down 10 percent, units down 12 percent |
| Shower stall, kit, or enclosure | About $700 | Dollars down 21 percent, units down 28 percent |
| Full kitchen or bath remodel | Several thousand and up | Widely deferred; handles and paint instead of cabinets |
Even the surface numbers understate the shift. Once you adjust for assortment changes, productivity per location has weakened across nearly every renovation-related category. Lower-ticket maintenance items have held up better, which props up the top line and makes the quarter look calmer than the aisle feels. Retailers can add products and distribution. That masks an absence. The customer who used to walk in with a renovation project is increasingly not there.
On a recent earnings call, the finance chief of one of those chains said affordability remains a major concern, and that concern is showing up as a preference for repair and maintenance over big discretionary projects. Caution around large tickets is not a one-quarter mood. It is the ongoing trend.
Maintenance Is Not The Same As A Remodel, Even If The Receipt Looks Busy
About 60 percent of consumers tracked by that home-services marketplace are now postponing projects and switching to upkeep. Kitchens and bathrooms are still the rooms people care about most. Caring is not the same as spending. New cabinetry is the cost center of a kitchen. Swap the handles, paint the boxes, live with the layout. It is a respectable compromise. It is also a compromise.
I have found that households under rate pressure get very good at a particular kind of triage. The furnace tune-up happens. The water heater gets replaced when it fails, not when it looks dated. Landscaping gets done in phases because phases can be paid from savings. A deck, which is pure pleasure, slides to the bottom of the list and stays there.
- Urgent systems come first: heat, water, roof, anything that fails in bad weather.
- Small cosmetic fixes fill the gap: hardware, paint, lighting, a single fixture.
- Phased outdoor work survives because it can stop after one weekend.
- Full kitchen and bath rebuilds are the first to be named and the last to be booked.
- Financed projects lose to cash projects, even when cash only covers a fraction of the wish list.
This is familiar behavior from other anxious stretches. When inflation bites or a shock hits, people do not stop spending on the house. They reprioritize. A water heater beats a new deck. A service call beats a gut job. The house still gets money. It just stops getting the money that changes how it feels to live there.
Why The Policy Is Working, And Why That Is The Uncomfortable Part
A chief investment officer at a planning firm described the mechanism without romance. Higher rates are meant to lean on inflation, and one way they do that is by making large financed purchases harder. The struggle to fund a renovation is not an accident beside the policy. It is one of the channels. Big-ticket household spending is supposed to cool. Home remodeling is about as big-ticket as ordinary life gets.
That design has a side effect in an economy that still depends heavily on the consumer. Spending by households is already a weaker driver of growth than it used to be. The cushion is thin: a soft jobs market, wage growth that has been easing, expensive gasoline and diesel, and net negative immigration. The thing holding a lot of the growth together right now is spending on data centers. If that slowed even mildly, the same observer argued, a recession would not be a stretch.
Perhaps the most interesting aspect is how uneven the restraint is. A server hall can still get financed. A household that wants a second bathroom often cannot, at least not at a rate that feels sane next to a 3 percent first mortgage. Both are “investment.” Only one shows up in the gross domestic product figures as a bright spot. The other shows up as a deferred shower kit.
As rates keep rising, tapping home equity gets more expensive. That holds back spending in general, and it hits renovations particularly hard. The difficulty financing large purchases is, in part, the point of the hiking cycle.
Wealth-management chief investment officer
The Fixer-Upper Math Broke First
Five or ten years ago, a certain kind of buyer treated a tired house as inventory. Buy it, fix it, sell it, keep the spread. That trade needed two things: tolerable borrowing costs and a resale market that paid for the work. Both have gotten less friendly. The professor who is waiting on his own kitchen says people are simply not buying fixer-uppers the way they used to. The cost of the money and the cost of the upgrades have risen together, which is a nasty combination if your profit lived in the gap between them.
You can feel the absence in neighborhoods that used to turn over every other spring. Fewer dumpsters. Fewer crews on ladders for three weeks and gone. The houses that would have been flipped are either staying with owners who patch what they must, or sitting longer because the next buyer cannot pencil the same renovation. Less turnover, less renovation spend. The loop feeds itself.
I am not mourning the flipper era as a golden age. A lot of that work was cosmetic and a lot of it was priced for the exit, not for the person who would live there. Still, it was a real channel of capital into the existing housing stock. When that channel narrows, the stock ages in place. Aging in place sounds pleasant until the roof is the thing aging.
Unavoidable Jobs Do Not Wait For A Friendlier Rate
A roofing-company owner described the old pattern as almost routine. Customers used equity lines and home equity loans to pay for replacements. Roofs, windows, heating and cooling systems: expensive, and eventually not optional. When the part of the house reaches the end of its life, the invoice arrives whether or not the household has cash stacked for it. Equity was the bridge.
If that bridge is too expensive, two things happen. Some projects get delayed past the point of prudence. Others get financed in worse ways, on cards or short-term credit, which is how a roof becomes a balance that outlives the shingles. The owner expects a decline in major renovations if liquidity stays this tight. That is not a forecast about taste. It is a forecast about forced choices.
Weather makes the delay less abstract. High wind, heavy rain, and temperature swings are not theoretical for a lot of regions. A roof or a window system that should have been replaced, and was not, because the equity line looked ugly, is a bet against the next storm. Sometimes the bet pays. Sometimes the deductible and the interior damage cost more than the project that was postponed. That is the part of the rate story that does not show up in a same-store sales chart.
- Systems with a hard end of life still fail on schedule.
- Cash reserves cover fewer of those failures than owners hope.
- Equity financing, the historical bridge, is priced out of casual use.
- Delays raise the odds of secondary damage.
- Secondary damage is almost always more expensive than the original job.
What “I’ll Just Wait” Actually Costs
Waiting feels free. It is not. Materials do not reliably get cheaper just because you paused. Labor in the trades remains tight in plenty of markets, which keeps bids firm even when demand for discretionary work softens. A project quoted this fall may not be the project you can buy in two years at the same number, especially if you are also paying to patch the thing you refused to replace.
There is a household version of deferred maintenance that anyone who has rented a tired apartment already understands. Small failures stack. The drip becomes a stain. The stain becomes a subfloor conversation. Cosmetic skipping is one thing. Structural skipping is another, and the line between them is blurrier than a mood board suggests.
Owners managing a portfolio face the same instinct, according to a capital-markets adviser who works with real estate investors. When tapping equity gets expensive, discretionary capital projects are often the first cut, for a family and for a landlord. If that equity stays locked for years, the broader housing economy gets less turnover, less renovation spend, and a market where existing owners hold rather than transact or improve. Holding can be rational. A whole market of holders is a quiet market, and quiet markets are not always healthy ones.
A rough household filter I keep hearing:
  Must fix now        → heat, water, roof, safety
  Fix if cash allows  → single fixtures, paint, hardware
  Finance only if the rate feels survivable
  Otherwise           → name the project, then wait
The Forever Home Nobody Quite Chose
There is a sales phrase the industry likes: turn the right-now house into the forever home. It sounds empowering. In this rate regime it is often a rebrand of being stuck. People are not discovering a sudden love of their floor plan. They are discovering that the alternative is a new loan they do not want.
That does change what they ask contractors. Fewer gut renovations, more “what can we do for a few thousand.” Fresh look, not new bones. A home-services lead described owners prioritizing the furnace visit over the kitchen dream, and spending on the tune-up because nobody wants the coldest morning to be the morning the heat dies. Sensible. Also a little sad if the kitchen folder has been open on the phone since 2022.
Couples feel this as a shared negotiation, even when nobody calls it that. One person wants the bathroom that works. The other wants to protect the payment. Neither is wrong. The argument is really about time horizon. If rates ease in a year, waiting is discipline. If they do not, waiting is how a temporary house becomes the house your knees learn.
Where The Money Goes When It Does Not Go Into Cabinets
Equity that is tapped and not spent on the house has to go somewhere. Credit-card balances are the unglamorous answer. Higher everyday prices, uneven wage gains, and a jobs market that no longer feels padded have pushed some households to use the house as a pressure valve. That can be the least-bad option in a bad month. It is not a remodel, and it leaves less equity for the day the roof actually fails.
I would rather see an equity line used on a twenty-year roof than on a revolving balance. The incentives of the moment push the other way for some families. The rate is high either way, so the draw goes to the pain that is due this month, not the project that can be ugly for another season. Renovation demand does not vanish in that world. It gets outbid by shorter-term stress.
Retail stocks in the home-improvement space have reflected the caution without collapsing into a single story. A year of share performance can look orderly while the mix inside the store shifts from projects to parts. Investors who only watch the top line miss the customer who used to buy a stall kit and now buys a cartridge for the existing valve. Both visits count as traffic. Only one rebuilds a room.
A Practical Way To Think About The Next Twelve Months
None of this is advice in the licensed sense, and rates can move. Still, the households I talk to are converging on a few habits that are less dramatic than a remodel and more useful than refreshing a mood board.
- Separate failure risk from taste. A roof with curled shingles is not the same decision as a backsplash.
- Price the project in cash first. If the only path is a second lien, write down the full interest cost, not just the monthly draw.
- Ask what a phased version looks like. Landscaping taught people this. Bathrooms can sometimes learn it.
- Do not assume the bid will be waiting unchanged. Get a fresh number when you are actually ready.
- Treat record equity as optionality, not as spent money. Untapped is not the same as available at a fair price.
Smaller interventions still change daily life. Better lighting, a working exhaust fan, a door that seals, a water heater that is not negotiating with you. None of those photographs like a new kitchen. All of them matter more on a Tuesday in January. The data on faucets versus shower kits is really a portrait of that hierarchy. People have not abandoned the house. They have narrowed what they will finance.
The Trades Feel The Absence Before The Headlines Do
Contractors live on the jobs that get booked, not on the jobs that get discussed. When big projects slip, the pain shows up as thinner pipelines, longer gaps between calls, and crews that stay busy on service work instead of multi-week rebuilds. Service work is real work. It does not staff a company the same way a run of kitchen jobs does.
Do-it-yourself demand shifts too. The person who would have hired a bath remodel might still buy paint and hardware. That supports part of the store and starves another. Manufacturers of higher-ticket renovation goods feel the gradient the analytics firm described: a few percent off on small items, a fifth or more off once the ticket climbs. If that lasts, product lines get trimmed, and the next upturn starts from a thinner shelf.
There is a labor angle nobody puts on the estimate. Tradespeople who cannot see a year of project work ahead do not hire apprentices at the same pace. A long pause in remodeling is not only a pause in spending. It can be a pause in the next cohort of people who know how to do the work when spending returns. That lag does not reverse the quarter rates fall.
What Would Actually Unstick The Projects
Owners are not waiting for a lecture on gratitude. They are waiting for a payment they can defend. A meaningful drop in second-lien rates would reopen projects that are already designed in people’s heads. A drop in first-mortgage rates would reopen moves, which pulls a different set of renovations behind it: the seller’s prep, the buyer’s first-year fixes, the things you do when a house changes hands.
Either path needs the cost of money to ease, or incomes to rise enough that the current cost feels smaller. Wage growth has been cooling, not accelerating, so the income route is the slower one. That leaves rates. Until they move, the rational household keeps the cheap mortgage, spends on what breaks, and tells itself the kitchen can wait. The telling is the easy part. The waiting is what the sales data already recorded.
Simple project test: if it fails, fix it. If it only disappoints, price the rate before you fall in love with the sample.A Market That Holds Can Still Decay At The Edges
Low turnover is often described as stability. Sometimes it is. Sometimes it is a stock of houses that are occupied, leveraged at old rates, and slowly drifting past the maintenance cycle their owners can comfortably fund. Stability and neglect can share an address for a while. The difference shows up later, in insurance claims, in inspection reports, in the gap between what a listing photo promises and what a buyer finds in the attic.
Discretionary projects deferred for a season are a mood. The same projects deferred because equity is too expensive to touch, year after year, become a condition of the housing stock. Portfolio owners know this. Households are learning it in slower motion, one postponed quote at a time.
I do not think the remodeling dream is dead. It is gated. The gate is the spread between the mortgage people already have and the price of new money. As long as that spread feels absurd, big rooms stay as they are, small fixes carry the spending, and record equity remains a number on a statement instead of a shower that does not leak. The folder on the phone can wait. The house, less patiently, cannot.
When I was a child, the poor collected old money not knowing the rich collect new, digital money.


Brazil Election: What Lula Or Bolsonaro Means For Markets

Stocks To Buy Now Ahead Of Earnings Season
Related Articles

New Home Sales Rebound as Prices Near 5 Year Lows
Have you ever watched the housing market like a tense tennis match, where every bounce seems to defy expectations? Just when it looked like new home sales were stuck in a slump, the latest figures show a modest rebound. Yet the story isn’t as simple as a single uptick. Prices are easing in ways we […]
China’s Property Market: Delayed Recovery Insights
China's property market faces delays in recovery until 2026 due to weak sales and stimulus fatigue. What does this mean for investors and the economy? Click to find out!
Why Triple Net Leases Attract Savvy Landlords
Ever wondered why landlords love triple net leases? They minimize risk and maximize income, but how? Dive into the details and find out the secret behind their appeal...