
I kept staring at the same headline number and could not make the arithmetic sit still. A claim of more than $20 trillion in outside money pouring into the country, with a further climb toward $25 trillion still waved as possible, sits next to a much smaller official tally of new foreign direct investment. The gap is not a rounding error. It is the whole argument. If you invest, hire, or simply try to read the economy without getting spun, that gap is where the useful question lives: where is the onshoring, really?
Perhaps the most interesting aspect is how easily a pledge can be mistaken for a plant. Announcements travel fast. Concrete, permits, and payrolls do not. I have found that markets reward the press release long before the loading dock exists, and then act surprised when the loading dock never quite arrives.
The Boom Narrative Meets A Much Smaller Number
The public case is simple and loud. Foreign governments and companies, the story goes, are committing sums no previous administration has matched. Trackers tied to the policy message list commitments from the Gulf, Japan, India, South Korea, and others that, added together, clear several trillion dollars. Manufacturing is described as higher than ever. The country is cast as the unmatched destination for outside capital.
Bank economists looking at the official new-investment series see something else. New foreign direct investment in 2025 came in around $232 billion. That is roughly $30 billion under the ten-year average. Adjusted for inflation, the year sits below every pre-pandemic year in the comparison. There was a modest lift versus the soft patch of 2022 through 2024. It was not a broad surge.
Short version: the speech and the ledger are not describing the same event.
One way to assess whether manufacturing is being brought home is to look at foreign direct investment itself, not at the stack of announcements.
Bank economist note on capital inflows
That framing is almost boring, which is why it works. Foreign direct investment is not a vibe. It is a measured flow of outside capital into a controlling stake, a new operation, or an expansion of an operation already owned from abroad. It is not a memorandum of understanding. It is not a summit photo. It is not a multi-year aspiration that can be revised when the cycle turns.
What The Official Series Actually Counts
People mix up three different things and then argue as if they were one thing. I do it too, until I force the categories apart.
- Announced commitments, which can be multi-year, conditional, and partly domestic money relabeled as a foreign win.
- Portfolio flows, meaning stocks and bonds that can leave on a Tuesday without building a single factory.
- New foreign direct investment, the narrower series that tries to capture control, greenfield starts, and expansions.
Only the third item speaks directly to onshoring. Even then it speaks with a lag, and it speaks in dollars that are not all equal. Buying a company that already makes steel is not the same economic event as breaking ground on a mill that did not exist last spring.
In my experience, the confusion is rarely accidental in a political setting. A big number is useful. A precise number is less useful if it is small. Readers who want a clean story should treat the two figures as answers to different questions. One asks, what has been promised in public. The other asks, what showed up in the investment accounts.
A Modest Pickup, Not A Renaissance
The 2025 figure was not a collapse. Relative to the prior three years it improved. The improvement clustered in media and telecoms, and in primary metals sitting inside a broader manufacturing bucket. That is a clue, not a victory lap.
Media and telecom deals often reshuffle spectrum, content libraries, and subscriber bases. They can be large. They rarely look like a machining hall in the Midwest. Primary metals are closer to the industrial story, and a real pickup there would matter for supply chains. A single sector moving does not equal a nationwide factory revival.
Below every pre-pandemic year in real terms is the line I keep coming back to. If the country were in the early innings of a durable manufacturing rebuild financed from abroad, you would expect the inflation-adjusted series to clear the old bar, not sit under it. Maybe next year. Maybe the lag is longer than the note allows. Right now the data refuse the parade.
Almost All Of It Was A Change Of Owner
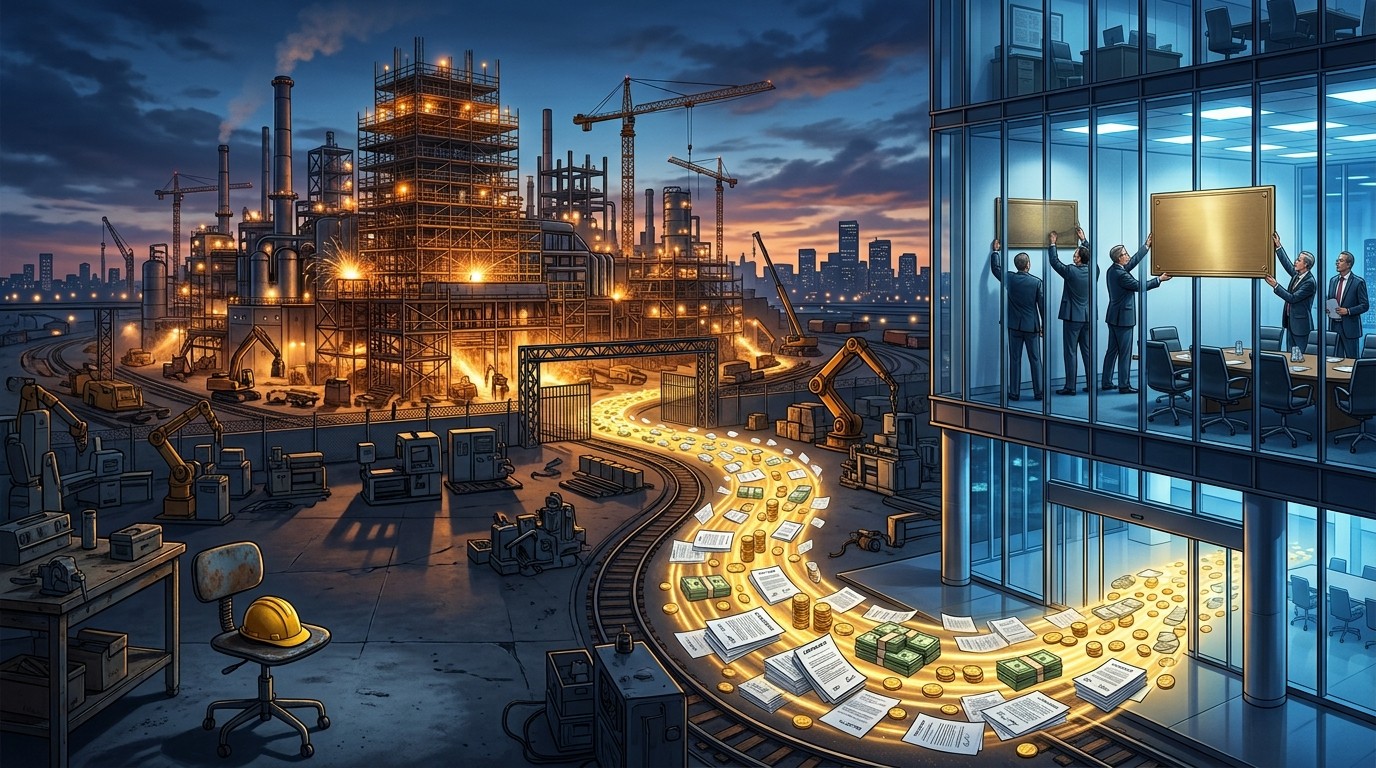
Here is the detail that should reset the conversation. About 94 percent of the new foreign investment took the form of acquisitions of firms that already existed. Roughly 2 percent reflected the creation of new businesses. About 4 percent was expansion of operations already owned from abroad.
Read that again, slowly. Foreign capital mostly changed the name on the door. It did not, in the main, add new productive capacity.
| Form of new foreign investment | Approximate share | What it usually means |
| Acquisition of an existing firm | 94 percent | Ownership changes, capacity often does not |
| Expansion of an existing foreign-owned operation | 4 percent | Some added plant, line, or headcount |
| Creation of a new business | 2 percent | Closest thing to a fresh greenfield start |
Acquisitions are not fake. A foreign buyer can bring cheaper capital, different technology, or a longer investment horizon. Workers can keep their jobs. Sometimes output rises after the deal because the new owner spends. Sometimes it does not, because the point of the deal was market share, patents, or a multiple.
The policy claim, though, is not “foreigners bought American companies.” The claim is that outside money is rebuilding production at a historic scale. Those are different sentences. Treating them as interchangeable is how a takeover wave gets dressed up as an industrial strategy.
Why Takeovers Dominate The Series
Deals are faster than dirt. A cross-border acquisition can close in months if financing and regulators cooperate. A new plant needs land, power, water, permits, labor, and a customer who will still be there when the line starts. In a high-rate, high-uncertainty stretch, boards prefer the thing they can model.
There is also a statistical habit. Large acquisitions land in a single year and dwarf a hundred small expansions. One telecom combination can outweigh a dozen machine shops. The series then looks “active” while the map of new square footage barely moves.
I do not think that makes the statisticians wrong. It makes the headline reader responsible for asking a second question. Was this money additive? Or was it a reshuffle of claims on assets that were already producing?
Greenfield Is The Word Everyone Skips
Greenfield investment is the unfashionable cousin. It means a new operation built from scratch, or close to it. Brownfield usually means buying or upgrading what is already there. Policy speeches love the first word. Balance sheets prefer the second.
When only a sliver of new foreign investment is new businesses plus expansions, the greenfield share is thin by construction. You can still have domestic firms building plants with their own cash or with subsidized credit. That would be onshoring of a sort. It would not be the foreign-money story being told. Separating those channels matters, because each one fails for different reasons.
- Check whether the dollar is a pledge, a financing commitment, or spent capital.
- Check whether the project is new capacity or a purchase of old capacity.
- Check the sector. A data hall is not a forge, even if both get called infrastructure.
- Check the timeline. Multi-year totals should not be booked as if they arrived this quarter.
- Check the domestic share. A joint venture can be mostly local money wearing a foreign flag.
Run a claimed project through that list and a surprising number of trillion-dollar lines get smaller in a hurry. That is not cynicism. It is bookkeeping.
The Lag Defense, And Where It Stops Working
The charitable reading is lag. Pledges come first. Spending comes later. A note written against 2025 data cannot fully judge commitments signed in the same year, let alone ones aimed at the back half of the decade. Fair enough. Construction spending, equipment orders, and employment in the relevant plants should be the follow-up, not another speech.
The lag defense has a shelf life. If year after year the announcement stack grows and the new-investment series, the construction series, and the manufacturing employment series do not, the lag stops being an explanation and starts being a hope. Investors who treat hope as a position tend to meet it again at earnings season.
There is a second problem inside the lag. Some commitments are explicitly spread over ten years or more. Dividing a huge number by ten already shrinks the annual claim. Then apply a historical conversion rate. Not every memorandum becomes a wire transfer. Diplomacy produces round numbers. Finance produces cancellations.
How Announcement Math Gets So Large
I have watched these totals get built, and the method is generous. A sovereign fund says it will look at opportunities up to a ceiling. The ceiling enters the tracker. A company repeats an existing capital plan at a summit and the plan is counted again. A joint project is booked at the full project cost even when the foreign check is a fraction. Domestic tax credits get narrated as foreign confidence.
None of that requires a lie in the narrow sense. It requires a loose definition. Loose definitions are how you get from a few hundred billion of measured new investment to a story measured in tens of trillions. The distance between those units is the distance between a factory and a press conference.
The open question is how much of the pledged money will finance new production, rather than purchases of businesses that already operate.
That question is the whole article, really. Everything else is context.
What Onshoring Would Look Like If It Were Happening
Suppose the revival were real and foreign-financed. You would not need a speech to find it. You would see it in a handful of places that are hard to fake for long.
- A rising share of new foreign investment going to establishments and expansions, not acquisitions.
- Manufacturing construction spending that stays elevated after the initial subsidy rush, not just a spike and a fade.
- Equipment imports and domestic machinery orders tied to new lines, not only maintenance.
- Industrial power demand in specific corridors, with interconnect queues that actually clear.
- Hiring plans that survive the first profit warning.
Some of those signals have flickered. Chip-related construction had a visible run. A few metals projects moved. Battery announcements were thick on the ground for a while, then thinner when demand and policy wobbled. Flickers are not a base. A base is boring repetition across years.
Perhaps I am too attached to repetition. Markets love a breakout. Industrial capacity loves a decade of not being cancelled. Those tastes do not match, which is why the equity story and the factory story keep divorcing.
Sectors That Carried The Modest Lift
Media and telecoms deserve a plain description. Foreign buyers and partners have long liked American content, networks, and distribution. A large deal in that space can dominate an annual FDI print. It can also be strategically important for data routes and advertising markets. It does not staff a stamping plant.
Primary metals are different. Steel, aluminum, and related processing sit closer to defense, autos, construction, and energy hardware. A real expansion there changes the cost and reliability of downstream goods. If the modest manufacturing pickup is concentrated in that pocket, watch permits and furnace restarts, not the aggregate dollar. Concentration is information. It tells you the boom, such as it is, is narrow.
Other manufacturing, in the residual sense, did not show a broad surge in the note. That absence is the finding. Autos, machinery, chemicals, electronics assembly: if onshoring were general, those lines would not be quiet at the same time the speeches are loud.
Domestic Money Versus Foreign Money
A plant financed by an American firm with retained earnings is still a plant. National accounts care about capital formation. Voters are often told a foreign story because foreign story sounds like tribute. The economics do not require the check to clear from overseas.
There is a political reason the foreign label gets stretched. It converts ordinary capex into evidence of diplomatic success. It also lets disappointing domestic investment hide inside a larger announced total. If you are trying to judge whether industry is returning, strip the label and look at square footage, megawatts, and headcount. The passport of the shareholder is secondary.
Foreign ownership still matters for other reasons. Control of critical processes, data, and mineral processing is a security question, not only a growth question. A takeover wave can raise that question even when it fails to raise capacity. Both issues can be true in the same year. More owners from abroad, not many more machines.
Subsidies, Tariffs, And The Cost Of Looking Open
The policy mix of the period pulls in two directions, and firms notice. Incentives invite projects. Tariffs and tighter screens raise the cost of cross-border structures. A company can announce a site to harvest a credit and still route the sensitive steps elsewhere. Screening regimes can slow the very acquisitions that dominate the FDI print, or they can push buyers toward structures that are harder to read.
I am not arguing that screens are a mistake. I am arguing that you cannot sell unrestricted welcome and selective closure with the same statistic. If deals are blocked, delayed, or redesigned, the new-investment series will show it. If projects are announced to match a tariff narrative and then paused, construction data will show that too. The narrative cannot audit itself.
Energy cost sits underneath both. A metals expansion without reliable power is a press release with a substation problem. Several industrial corridors are already rationing interconnects. Foreign capital does not repeal queue times. Until power and permitting move, the greenfield share is likely to stay the small number in the table.
What Investors Should Actually Watch
If you allocate capital, the speech is a sentiment input, not a model input. Sentiment can move multiples for a quarter. It does not pour a foundation. The practical dashboard is shorter than the tracker.
- The split of new foreign investment between acquisitions and expansions, updated when the annual series lands.
- Manufacturing construction put in place, especially private, and whether it holds after incentive cliffs.
- Industrial production in primary metals, machinery, and electrical equipment, not the headline index alone.
- Corporate guidance that distinguishes growth capex from maintenance and from deal consideration.
- Cancellation and delay rates on announced sites. Silence after the groundbreaking photo is a data point.
A portfolio does not need to “believe” or “disbelieve” the boom. It needs to know which stocks are priced for capacity that has not been ordered. Multiples on equipment suppliers, regional banks in project corridors, and industrial REITs can embed the announcement. Earnings embed the invoice. The spread between those two is where disappointment usually hides.
On the other side, a takeover-heavy FDI year can still be a bid for listed targets. If foreign buyers are active, strategic premiums in telecom, media, and selected industrials can be real even while greenfield stays scarce. That is a trading fact. It is not an industrial renaissance. Confusing the two is how people buy the wrong exposure.
A Simple Scoreboard You Can Keep
Onshoring scoreboard, informal:
  Announced totals        = narrative
  New FDI dollars         = measured inflow
  Share that is M&A       = ownership, not capacity
  Share that is expansion = closer to real plant
  Construction and jobs   = the audit
I keep a version of that on a notepad because the public debate refuses to. Once the categories are separate, the $20 trillion claim and the $232 billion print can coexist without one of them being called a hallucination. They answer different questions. The error is using one as proof of the other.
Could the measured number rise sharply next year if pledged projects start to fund? Yes. Should anyone mark that rise to market today? Only with a discount that would embarrass a summit brochure. Historical conversion from headline commitment to spent greenfield capital is not one-for-one. Anyone who models it as one-for-one is selling something.
The Employment Claim Needs The Same Treatment
Manufacturing employment and manufacturing output are not the same series, and neither is the same as investment. Output can rise with productivity while headcount stalls. Headcount can rise in assembly while the high-value steps stay offshore. A claim that manufacturing is “higher than ever” needs a unit. Higher than when, in jobs, in real output, in nominal sales, in square feet?
Nominal sales are the easiest series to celebrate, because prices did a lot of the work after the pandemic. Real output is stricter. Employment is stricter still in sectors that automated. If the political line does not specify the unit, it is not yet an empirical claim. It is a mood.
Foreign investment does not automatically hire. An acquisition can be followed by synergies, which is the polite word for overlapping roles. An expansion hires, eventually, if the expansion is real. The 4 percent expansion share is why jobs should not be inferred from the gross FDI number. Inference is how local officials get surprised.
Regional Politics And The Empty Site
States compete for these announcements with land, tax abatements, and training grants. The photo is local even when the capital is not. When a project slips, the abatement often remains on the books as a success story until a reporter or a bond analyst asks about the payroll covenant.
This is where the national tally becomes personal. A county that cleared a site for a promised metals line cannot spend a Gulf framework agreement. It can spend wages. If the wages do not arrive, the onshoring debate is no longer abstract. It is a graded pad and a stalled substation.
I have a bias here, and I will own it. I trust the site visit more than the tracker. If the fence is up and the steel is arriving, fine. If the fence is a rendering, the trillion can wait outside.
Currency, Rates, And Why Buyers Prefer Paper
Cross-border buyers do not ignore the price of money. Higher funding costs punish long-dated greenfield projects more than they punish acquisitions that can be levered against existing cash flow. A target with customers is a credit story. A field with a zoning letter is a hope story. In tight credit, hope loses.
The dollar’s path matters too. A strong dollar makes American assets pricey for foreign buyers and can still attract them if they want the jurisdiction. A weaker dollar makes the entry ticket cheaper and can coincide with worries about the very stability buyers wanted. Neither path guarantees a mill. Both paths show up in deal committees before they show up in ribbon cuttings.
Portfolio inflows can swell at the same time direct investment stays ordinary. Reserve managers and private funds buy Treasuries and listed equity. That is foreign money. It is not onshoring. Anyone adding those flows to a factory total is mixing a savings account with a construction budget.
How To Read The Next Official Release
When the next new-investment tables arrive, ignore the first headline if it is only a dollar total. Go to the composition. If acquisitions are still near nine-tenths of the print, the ownership story continues. If expansions and new establishments jump and stay jumped, the capacity story earns a revision. One year will not settle it. Direction across two or three releases might.
Also watch revisions. These series move after the first print as late transactions are classified. A modest year can be revised up. A splashy year can be revised toward deals that were refinancings of older stakes. Classification is not trivia. It is the difference between “they built” and “they bought.”
Compare the nominal figure with an inflation-adjusted one before you celebrate a rebound. A nominal bounce that fails to clear the pre-pandemic real level is a bounce inside a smaller room. The note’s point was exactly that. Real terms are less flattering, which is why they are the right terms for a claim about historic scale.
What Would Change My Mind
I am not married to the skeptical read. Evidence could move it. A sustained rise in the expansion share, a manufacturing construction plateau that does not depend on a single subsidy program, and foreign-owned establishments adding workers in tradable goods would do it. So would import substitution that shows up in the trade data for intermediate goods, not only in slogans.
What would not change it is another summit total. Round numbers from framework agreements have a perfect record of needing a footnote. Until the footnote includes spent capital and physical capacity, the footnote is the story.
There is room for a middle outcome, and it may be the likely one. Some projects in metals, energy equipment, and selected electronics get built. Most of the announced trillions never become annual FDI. Acquisitions continue to dominate the measured flow. Politicians claim the projects. Economists point at the composition. Both can cite a real fact. Only one fact answers the capacity question.
The Market’s Quiet Verdict So Far
Equity markets have not behaved like a country receiving an unmatched industrial endowment. Industrial multiples move with rates, oil, and the cycle, not with the tracker. Regional beneficiaries spike on groundbreaking headlines and give the spike back when the timeline slips. That pattern is the market admitting, in prices, that announcements are options.
Credit markets are stricter. Project finance lenders want offtake, power, and covenants. If the foreign boom were bankable at the advertised scale, you would see a thicker pipeline of closed greenfield financings, not only press notes. Closed financings are boring documents. They are also closer to truth than a podium.
None of this means foreign capital is absent. $232 billion is a large sum in ordinary language. It is small only relative to the claim placed beside it. Scale is a comparison. Without the comparison, both the boast and the rebuttal are theater.
A Practical Reading For Operators
If you run a supplier, the useful question is narrower than the national debate. Is your customer ordering tooling, or touring a site with officials? Tooling orders pay. Tours do not. Export controls and domestic-content rules can still shift your order book even if aggregate FDI is ordinary. Policy can rewire a niche without rewriting the national accounts.
If you hire skilled trades, watch apprenticeship slots tied to named projects with financing closed, not to named projects with a letter of intent. The trades shortage is real in several regions. It will not be solved by a statistic that is 94 percent acquisitions. Acquisitions do not pour footings.
If you underwrite municipal risk, ask what happens to the incentive package if employment thresholds are missed. The onshoring story has a public balance sheet attached at the local level. That balance sheet does not appear in the national speech.
Putting The Two Numbers In One Frame
Let me set them side by side without theatrics. On one side, a political total above $20 trillion, with a suggestion it could reach $25 trillion over a term, built from foreign and domestic announcements and described as unprecedented. On the other side, new foreign direct investment near $232 billion in 2025, a bit under the ten-year average, weaker than pre-pandemic years after inflation, and overwhelmingly acquisitions.
The reconciliation is not mysterious. Definitions differ. Timing differs. A large share of the political total may never be foreign, never be direct, and never be investment in new capacity. A slice may arrive later and deserve a revised view. The slice is the part worth tracking. The rest is atmosphere.
Atmosphere moves polls and, for a while, prices. It does not staff a second shift. Until the composition of foreign investment tilts away from takeovers and toward establishments that did not exist, the honest sentence is the shorter one. Outside money is mostly buying what is already here. The onshoring people were promised is still, in the data, mostly a promise.
Foreign capital is largely changing ownership rather than adding new productive capacity.
Reading of the latest new-investment composition
That line is uncomfortable because it is specific. Specific lines are what remain after the round numbers leave the room. I would rather underwrite the uncomfortable line than the comfortable total. Plants are uncomfortable. They require power, people, and time. Takeovers require a banker and a board. The 2025 mix tells you which one the money preferred.
Watch the next composition table. If it still looks like a deal list, the boom is a change of shareholders. If it starts to look like a building list, then, and only then, the speeches will have caught up with the ground.