
If you have a child between roughly seven and fourteen, there is a decent chance they already have money you have not fully tracked. A large parent-and-child survey published earlier this year found that about 86 percent of kids in that age band have their own money, and nearly all of them, 97 percent, say they make at least some spending decisions without an adult signing off. The sample was just over a thousand kids and a similar number of parents, so this is not a quirky anecdote from one neighborhood. It is a pattern.
I have found that the surprise is rarely the earning. It is the silence around it. Kids resell clothes, flip small lots online, take odd jobs, collect allowance, and park the result in an app their parents barely open. Spending is fluent. Saving is optional. Investing, for a lot of families, still feels like a conversation you have after college. That timing is late. Not morally late. Mathematically late.
Why This Generation Already Has Cash, and Why That Changes the Parent Job
Call them entrepreneurial if you want. The label is a little shiny, but the behavior is real. They buy and sell. They watch resale markets the way an earlier generation watched Saturday cartoons. Platforms that allow younger sellers usually set a floor around thirteen, and under eighteen a parent often has to sit on the payment side. The point is not the app. The point is the habit. Money moves through their hands before they can drive.
Even the kids who are not flipping sneakers still get paid. Chores. Odd jobs. Birthday envelopes. A grandparent who would rather send cash than another plastic toy. Put those streams together and you get a child who feels, correctly, that some of the money is theirs. Nearly all of them exercise that feeling. They choose the snack, the skin cream, the game pass, the thrift-store jacket. Independence shows up first as a purchase.
Parents, understandably, want the next chapter to look different. Spend less on impulse, park more for later, and maybe, if the family is ready, let a slice of that money sit in a market that can grow. The tools exist. Education accounts. Newer investment accounts built for minors. Custodial brokerage accounts. Retirement accounts tied to a child’s actual earned income. Kid-facing apps that sit on top of an adult-controlled account. None of them open themselves. A child cannot walk into this alone, and that is the part worth sitting with.
Good money management is a string of trade-offs. Spend more now and you save less. Save only in cash and you may grow less than you could. The earlier a kid practices that fork in the road, the less abstract it feels at eighteen.
A view echoed by founders who build kid investing tools
Perhaps the most interesting aspect of this moment is how ordinary the earning has become, and how unfinished the teaching still is. A child who can price a cup of lemonade can also learn what happens if half of Saturday’s take never gets spent. That is not a lecture. It is a repeated, slightly boring, extremely powerful habit.
What the Numbers Actually Say About Young Earners
Surveys of this age group are easy to overread. Kids exaggerate. Parents underestimate. Still, the shape of the data is hard to shrug off. Most children in the seven-to-fourteen range report having money of their own. Almost all of them report choosing how at least some of it leaves their hands. Parents in the same study often discover balances they did not expect, especially when the child sells things rather than only receiving allowance.
Resale is the detail that keeps coming up in conversations with consumer researchers. Online auctions, peer marketplaces, neighborhood sales. A minimum seller age of thirteen is common, with extra permission and payment help required under eighteen. That legal speed bump does not stop the activity. It just pulls a parent into the checkout, which is an opportunity if you use it and a missed conversation if you only tap approve.
I would not treat every kid with a digital balance as a future founder. Some of them are simply good at asking relatives for cash and bad at spending it. Both types need a container. The entrepreneurial ones need a place that is not a wallet they can drain between school and dinner. The savers-by-accident need a reason to keep going once a friend starts talking about a trend.
The Coffee Counter Paradox
The lemonade-stand daughter is a useful picture because she holds two truths at once. She can produce income. She still behaves like a kid who wants a drink she does not feel like funding. That is not hypocrisy. It is development. Earning and stewardship are different skills, and the second one does not arrive because the first one did.
If your child asks you for money they technically have, resist the quick speech. Ask where the stand money went, or the resale money, or the birthday money. Not as a cross-examination. As a map. You are trying to see whether the cash is visible to them or whether it already dissolved into small purchases they cannot name. Visibility is the first adult skill. Everything else, including investing, sits on top of it.
Kids Learn Money by Watching You First
A certified planner who works with everyday banking customers put it in plain language. Children absorb the words you use around bills, the sigh you make at the card reader, the way you treat a windfall. They do not need a curriculum to pick up a mood. Take care of your own accounts, and watch the sentences that leak out at the table. That is the quiet curriculum.
I have watched families undo a decent allowance system with one repeated line. “We can’t afford that” said about everything, including things they can afford and have simply chosen not to buy. Kids hear scarcity even when the household is fine. The cleaner version is a trade-off. We are not buying that because the trip, or the emergency fund, or the school payment comes first. Same no. Different lesson.
There is a girl, now fifteen, who started earning as a child model around age six. She wanted to give some of it away and spend some on toys, which is exactly the split you would hope for and rarely get without help. Money felt enormous to her then. Her parents and older brothers made it smaller by example, not by speeches. She later built a small art brand as an eight-year-old, saw products land on big-store shelves, wrote children’s books, and now sits on a youth board that talks about saving. She is also saving toward a car after sixteen, and further out, school.
Her mother says they never centered money in the house. They centered gifts, school, and the projects the kids actually cared about. Piggy banks came first. A debit card on a joint account arrived around eight or nine. Overspending was not the family problem, so correction stayed light. The interesting part, to me, is that access showed up early and drama did not. Access without a story is just a card. Access with a story about goals is practice.
She also has a required personal finance class. Stock-market ideas felt intimidating until she had sat with them. That is a useful reminder for parents who assume the topic is too heavy. Intimidation usually means missing vocabulary, not missing ability. A short explanation, repeated, beats one heroic lecture in the car.
Peers, Trends, and the Pull to Spend
Plenty of kids this age are deep in skincare, makeup, and whatever the group chat has decided is normal this month. Thrifting can be a counterweight, and mall trips with friends are not a moral failure. The fifteen-year-old who runs the art brand still shops for clothes and still goes to movies. She just ranks those purchases under the car and under school. Ranking is the skill. Deprivation is a brittle substitute.
If your child is trend-led, do not open with a ban. Open with a number. How much of this month’s money is for the trend, and how much has a name that is not a product? A named goal beats a vague “save more.” Cars, a trip with a friend, a first computer that is not a hand-me-down, a slice of future school costs. Names make the trade-off visible.
A Simple Split You Can Actually Keep
Families love complicated jars until week three. Three buckets are enough for most kids under fifteen.
- Spend: the part they can use without a meeting
- Save: a near goal they can see inside a year or two
- Grow: a smaller slice aimed at an account that can earn or compound
Percentages are a family choice. Some parents like 50, 30, 20. Some flip it when a big goal is close. The ratio matters less than the fact that spend is not 100. I have found that kids accept a split faster when they helped pick the save target. A parent-invented goal feels like a tax. A kid-named goal feels like a plan.
Joint Savings, and Why Cash Still Has a Job
Before anyone talks about markets, most kids need a plain place for money that should not be spent this month. Many banks will open a joint savings account with a child as long as the parent is the primary holder. That structure matters. The adult stays on the account. The child can see the balance, sometimes move money, and learn what a statement looks like.
High-yield savings accounts generally pay more than the old passbook-style accounts that barely moved. Rates change, and a rate that looked generous last year can look ordinary now, so the lesson is not “chase the headline number.” The lesson is that idle cash can earn something while it waits. For a ten-year-old, watching a few dollars appear because they did nothing is a small magic trick. Use it.
Cash is the right home for money they might need soon. A bike fund. A school trip. Emergency money if a teen job falls through. It is the wrong only-home for money that has a decade to sit. That distinction, soon versus later, is the bridge into investing. Skip it and the stock conversation feels like a gamble. Include it and investing looks like a different shelf in the same closet.
Education Accounts, When School Is Actually the Plan
Families who expect college, a trade program, or another qualifying path often look at 529 savings plans. An adult opens and runs the account. A child can still put their own earnings or gifts into it. Growth used for qualifying education costs is tax-free at the federal level, and some states offer a deduction or credit for contributions. That is the appeal, and it is a real one.
Qualifying costs are broader than people remember. Tuition at colleges and trade schools can count. Certain apprenticeship expenses can count. The rules are specific, so a parent should read the current list rather than rely on a memory from a cousin’s wedding. The emotional risk is different from the tax risk. If a child is unsure about school, a 529 can feel like a locked door. There are ways to redirect unused funds, including, in recent years, limited paths toward retirement accounts, but those paths have caps and conditions. Do not promise a child the money is “only for you, forever, for anything.” That promise is not how these accounts work.
I like 529s when the family already has a school intention and the child understands that this pile is not the mall fund. I like them less as a default dumping ground for every gift from every relative. Label the account out loud. This one is for learning after high school. The other one is for the life they are living now.
The Newer Minor Investment Accounts
A second path has arrived in the form of 530A accounts, often discussed in public as Trump Accounts. They are built to hold investments for a child and they rhyme with retirement accounts more than with a checking account. For 2026 and 2027, contributions are generally capped at 5,000 dollars a year. Withdrawals are generally off the table before the calendar year the beneficiary turns eighteen.
After that year, the tax treatment generally resembles an individual retirement account. Withdrawals are taxable. A 10 percent penalty can apply if the money comes out before age 59 and a half. Exceptions exist, including certain education costs and a first-home purchase. Read that twice before you sell the idea as “free money at eighteen.” It is not a high-school graduation purse. It is a long container with a few early doors.
That long horizon is the feature, if you are honest about it. A child who puts a slice of stand money or chore money into a market account and cannot yank it out for a video game has just met delayed gratification with a calendar attached. The risk talk still belongs in the room. Markets fall. A balance in middle school will not move in a straight line. Saying that early is kinder than discovering it during the first ugly year.
Custodial Brokerage Accounts, the Flexible Middle
Parents who want investing without the withdrawal rules of a 529 or a 530A often use custodial brokerage accounts, commonly called UTMA or UGMA accounts. An adult opens the account for a minor. The child, with the adult’s help, can hold stocks, mutual funds, and bonds. Control passes to the child at a state-set age, often somewhere between 18 and 25.
Flexibility is the gift and the hazard. Money in these accounts can be used for the child, not as a secret parental piggy bank, and once the child reaches the age of majority in that state, the account is theirs. Truly theirs. A parent who funded it hoping for college may watch it leave for a car, a move, or a decision they dislike. If that possibility keeps you up, this may be the wrong wrapper, or it may be the right wrapper with a smaller balance.
Tax treatment is another adult detail kids do not need on day one, but parents do. Unearned income in a child’s name can be taxed under so-called kiddie tax rules once it crosses modest thresholds. A small starter portfolio rarely triggers drama. A large gift from a grandparent might. This is a conversation with a tax preparer, not a group chat.
A practical order many families use:
  1. Named cash goal in joint savings
  2. Small automatic transfer the child can see
  3. One investing account with a job the child understands
  4. Extra wrappers only after the first one is boring and stable
When a Child Actually Earns, Retirement Accounts Enter the Picture
If a child has real earned income, a parent can open a custodial traditional or Roth individual retirement account. The contribution limit is the lesser of the standard annual cap, 7,500 dollars in 2026, or the child’s earned income for the year. Allowance for making a bed usually does not count. Pay for a real job, a documented stand, or modeled work with proper records can.
The Roth version is the one parents tend to prefer for kids, and for a simple reason. Contributions are made with money that has already been taxed, which for a child in a very low bracket is often a small price, and qualified withdrawals much later can come out tax-free. Decades of compounding inside that wrapper is the whole argument. A few hundred dollars at age twelve is not life-changing on the day it is deposited. It can be surprisingly loud by the time that child is sixty, if it is left alone.
Paperwork is the unglamorous half. Earned income should be real and recorded. A parent who “pays” a child for vague household help and then funds a retirement account is asking for a problem. Keep it clean. If the lemonade stand is a business, treat it like one at the scale it actually is.
Apps and Brokerages Built With a Child in the Loop
Several firms now sit between a parent and a kid who wants to press the buttons. One well-known micro-investing company offers an early custodial account paired with a child-friendly app. Another debit-card company aimed at families offers an investment feature held in the parent or guardian’s name. The child can request a trade. The adult approves it. That approval step is the product, in a way. It slows the impulse without pretending the child has no opinion.
Large brokerages have their own versions. One lets parents open a teen account that the teenager then manages inside guardrails. Crypto and foreign currency are examples of what those teens cannot touch. Another offers a joint brokerage account shared by a teen and a parent. The branding differs. The pattern does not. An adult is on the account. A young person gets a narrower set of choices than a full brokerage login.
Kids cannot open these on their own. That restriction is easy to resent and worth defending. A thirteen-year-old does not yet have the legal capacity, or usually the emotional distance, to sit through a bad year in the market without a steady voice nearby. The app can teach the clicks. It cannot teach the stomach. That part is still yours.
| Account type | Best suited for | Main limit to explain |
| Joint savings | Near-term goals and first habits | Low growth, easy to spend |
| 529 education plan | School and qualifying training | Best tax break is for education use |
| 530A style account | Very long investing horizon | Early withdrawal rules are strict |
| UTMA or UGMA | Flexible investing for a minor | Child takes full control later |
| Custodial Roth IRA | Kids with real earned income | Cannot exceed actual earnings |
| Teen brokerage | Practice with guardrails | Parent still anchors the account |
The right row depends on the child in front of you, not on the row a podcast liked. A planner who works with family banking customers makes the same point. Match the tool to the goal. A car at sixteen and a retirement balance at sixty should not share one unlabeled pot.
How to Talk About Risk Without Scaring Them Off
Investing has a benefit and a bruise. The benefit is compounding, the quiet math in which returns can earn returns. The bruise is that prices move, sometimes down, for reasons a child did not cause and cannot fix. If you only teach the benefit, the first drop feels like betrayal. If you only teach the bruise, they will keep everything in a wallet.
A metaphor that tends to land: the savings account is a shelf. The market account is a garden. Shelves do not die in a frost. Gardens sometimes look terrible in February and fine in June, if you did not dig everything up in a panic. You do not need them to love the metaphor. You need them to expect February.
Start with a broad fund rather than a single company they saw in a video. A single stock is a story. A broad fund is a habit. Stories are fun and habits are how balances survive middle school. If they insist on picking one company, cap it. A small slice for the story, most of the grow-bucket in the boring fund. You can say that out loud. Boring is a compliment in this room.
- Name the goal before you name the ticker.
- Decide the amount that can stay untouched for years.
- Show a chart that includes a bad year, not only a rising one.
- Agree on what you will not do when the line falls.
- Review on a schedule, not every evening.
That last step is where a lot of well-meaning parents slip. Checking an app nightly teaches the child that the scoreboard is the point. A monthly or quarterly look teaches that the plan is the point. I would rather a kid forget the password for three weeks than refresh a quote between classes.
Compound Interest, Shown Instead of Preached
You can explain compounding in a sentence. Money earns money, and then that new money earns money too. The sentence rarely sticks. A table does.
Imagine a child puts 20 dollars a month into an account earning a steady 7 percent a year, which is an illustration, not a promise. After ten years of that small transfer, they have contributed 2,400 dollars. The balance, if the rate held, would sit noticeably above that, because early dollars had time to work. Stretch the same habit to thirty years and the gap between what they put in and what is there becomes the lesson. Markets will not deliver a smooth 7 percent. The shape of the lesson still holds. Time is the lever a child actually has, and adults mostly do not.
A planner’s line is worth borrowing here. Even if the contribution is small, the point is the habit. Twenty dollars that happens every month will beat two hundred dollars that happens once, in a burst of New Year energy, and then never again. Kids are good at bursts. Parents have to be good at calendars.
Allowance, Chores, and the Messy Question of Pay
There is a long argument about whether chores should be paid. I do not think there is a single correct house. What I do think is that mixing “being part of the family” with “running a micro business” confuses both. Some tasks can be the cost of living in the house. Some tasks can be optional and paid. A child who only works when money is attached may need the first category. A child who already hustles may need the second, so the hustle has a ledger.
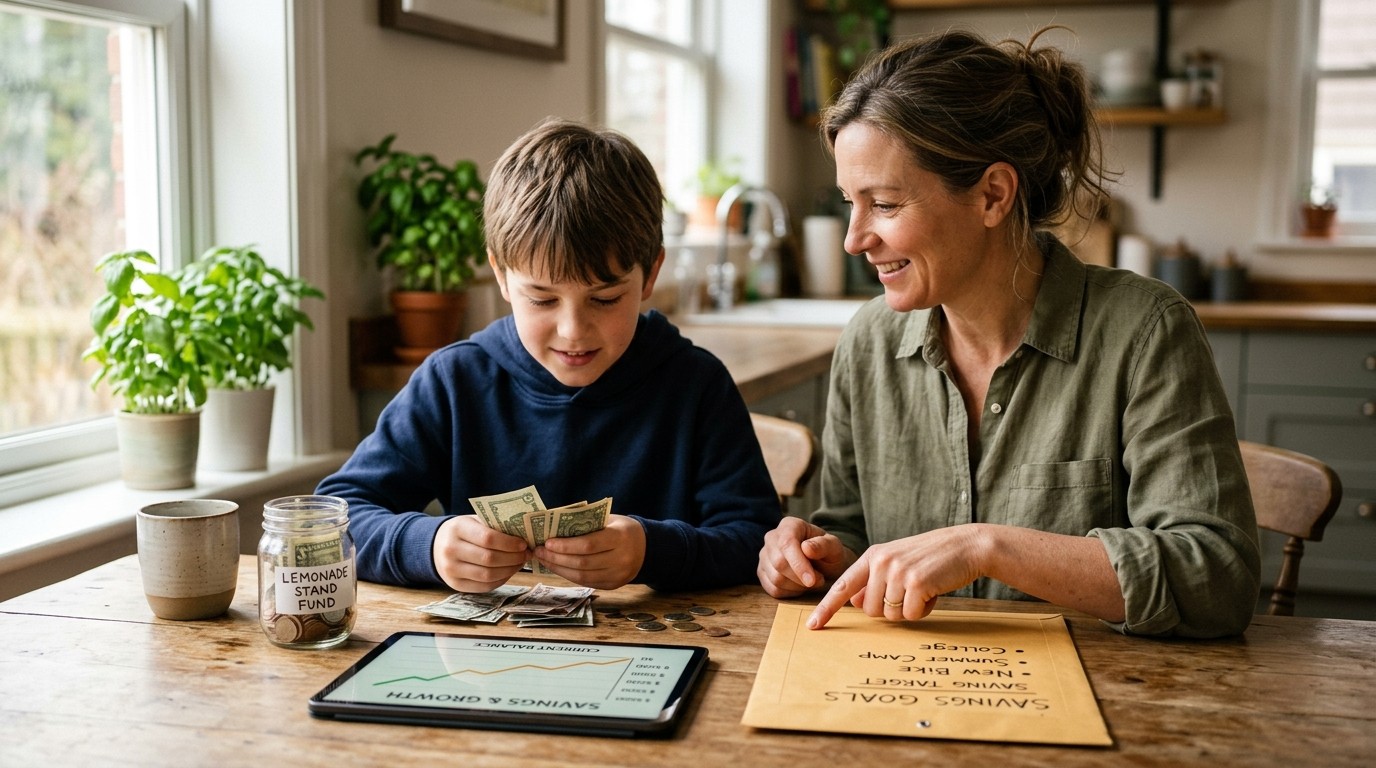
If you pay for extra work, pay on a schedule and write it down. Predictable income is easier to split into spend, save, and grow. Random income becomes random spending. The lemonade stand is a gift for this reason. Saturday has a number. Sunday can have a rule. Half stays visible for a goal. A slice can move to the grow account. The rest is theirs without a speech.
Odd jobs for neighbors raise a different issue. Cash in hand disappears. A note in a phone, or a simple envelope system, keeps the number honest. You are not auditing a corporation. You are stopping the fog.
Gifts From Relatives Without Starting a Family Argument
Grandparents like to give. Sometimes they like to give with instructions. A check “for college” that lands in a spending account will not stay a college check unless someone moves it. Decide the path before the birthday, if you can. A 529 contribution, a custodial deposit, or a savings transfer can be named in the thank-you note so the giver sees where it went.
Large gifts have reporting rules once they cross annual exclusion amounts. Most ordinary birthday checks never get near that line. A five-figure transfer might. Again, this is adult homework. The child needs to hear a simpler sentence. Someone who loves you added to your later pile. It is not weekend money.
What to Do When They Blow the Spend Bucket
They will. A game, a friend, a trend, a bad afternoon. The useful response is not a rescue and not a sermon that lasts the whole drive. Let the spend bucket be empty. That emptiness is the curriculum. If you refill it every time, you have taught them that buckets are decorative.
The grow bucket should be harder to raid. That is the structural point of custodial rules, approval steps, and accounts they cannot drain from a phone in the school cafeteria. Friction is a feature. Use it on purpose, and tell them why, so it does not feel like a trick.
If the miss was honest confusion, fix the system, not the child. Maybe the spend amount was fantasy. Maybe the goal was yours. Adjust, then let the next month be clean. Shame is a terrible teacher of arithmetic.
Ages and Stages, Without a Rigid Script
Around seven to nine, cash and jars still beat dashboards. Counting is the skill. A joint savings account can exist in the background so interest is not theoretical. Investing language can be a story about owning a tiny piece of a company that makes something they know. Keep the story short.
Around ten to twelve, digital wallets show up, and so does comparison. This is a good age for the three-bucket split and for a first look at a custodial account they do not control. Let them suggest a fund or a company, then show them what happened to that idea over a rough year. Curiosity first, keys later.
Around thirteen to fifteen, earned income gets more real, resale gets easier, and peer spending gets louder. Teen brokerage guardrails, a custodial Roth if the income is genuine, and a named near goal like a car all fit. This is also the age when a school personal-finance class may appear. Ask what they heard. Fill the gaps. Do not assume the class covered risk, taxes, or the difference between a need and a very convincing want.
None of these bands are laws. A careful nine-year-old can handle more than a scattered fourteen-year-old. Follow the child you have, not the child in the article.
The Words That Help, and the Words That Backfire
A few phrases do quiet damage. “Money doesn’t grow on trees” is true and useless. “We’re broke” when you are not teaches anxiety. “You’ll understand when you’re older” closes a door they were willing to open. Try plainer lines. We are choosing the trip over the shoes. This account is for later, so it is supposed to be boring. Prices fall sometimes, and we agreed not to yank the money out because of one bad month.
Questions work better than verdicts. What are you hoping this purchase does for you? If we split Saturday’s stand money, what should the later half be called? If the balance drops, what did we say we would do? You are building a script they can use when you are not in the room. That is the actual goal. Not compliance. A script.
When Parents Disagree About the Plan
One parent wants the market. The other wants everything in cash until eighteen. Kids notice the split and shop for the softer answer. Settle the wrapper in private. You can still tell the child that adults weigh risk differently, which is itself a lesson, without letting every deposit become a debate they referee.
If you share custody, account titles and login access need to be explicit. A custodial account has a custodian. Ambiguity there creates problems that have nothing to do with compound interest. Put the practical rules in writing. Who approves trades. Who can see the balance. What happens to contributions if a month is tight.
Scams, Influencers, and the Promise of Easy Returns
A child who already sells online will eventually see a pitch. Double your money. A secret strategy. A creator who treats a brokerage app like a game show. You will not block every video. You can install a family rule. No sending money, codes, or photos of cards to anyone because a stranger, or a classmate, said the return was guaranteed. Guaranteed is the word that should make them pause.
Practice the pause on purpose. When they show you a clip, ask what would have to be true for that return to be real, and who gets paid if it is not. You are not trying to win an argument about a personality. You are trying to make slickness feel slightly suspicious. That suspicion ages well.
A Month-One Setup That Does Not Require a Perfect Family
Perfection is how these projects die. A decent first month looks ordinary.
- Find every place the child already holds money, including app balances
- Name one near goal and one later goal in their words
- Open or tidy a joint savings account and automate a small transfer
- Pick a single investing wrapper and fund it with an amount you can ignore
- Put a twenty-minute review on the calendar, then stop talking about it daily
If the investing wrapper feels like too much this month, do the savings piece only. Sequence beats scope. A child who can see a balance grow for ninety days is ready for a harder conversation. A child who got a lecture and a login on the same afternoon is ready to tune out.
What “Enough” Looks Like Before They Leave Home
You do not need a teenager with a sophisticated portfolio. You need a teenager who can answer a few plain questions. Where is the spend money. Where is the later money. What happens if prices fall. What did they earn, and what did they keep. A young adult who can answer those will outrun a young adult who was handed a large account and no vocabulary.
The father with the lemonade stand does not need his daughter to stop asking for coffee money tomorrow. He needs the stand money to have a name, a home, and a rule she helped write. The asking can continue. The fog does not have to.
The whole point is the habit. Small, repeated, visible. A child who expects money to have a job will keep giving it one after you stop reminding them.
Gen Alpha is not waiting for a class called adulthood to meet money. They already have it, already spend it, and in more houses than parents realize, already earn it. Saving and investing are the missing half of a story they have started without you. You can still write that half with them. Not by taking the wallet away. By giving the wallet a second room, and teaching them why they might want to leave something in it.
Start with what they already did this month. A stand, a chore, a resale, a gift. Split it where they can see the split. Then let time do the part neither of you can rush. That is less glamorous than a stock tip and far more likely to still be there when the coffee money is finally theirs to refuse.
]]>