

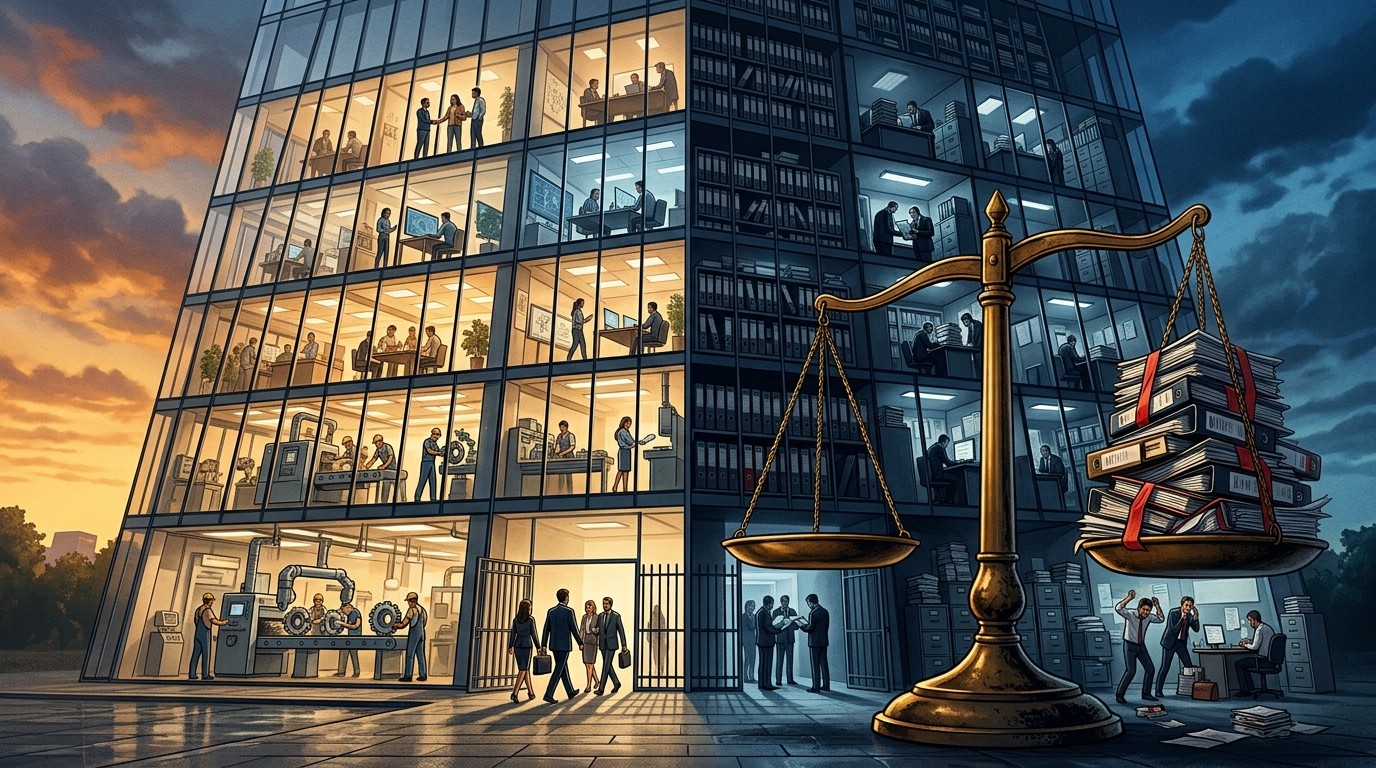

I still remember the afternoon a wealth manager slid a folder across a conference table and said, almost apologetically, that the structure only “penciled out” above a certain size. Not a little above. Comfortably above. The product was clever. The tax logic was clean. The fees, though, sat there like a toll booth. Below the threshold, the cleverness ate the benefit. Above it, the same paperwork became a privilege. That scene has stayed with me longer than any chart of income shares, because it showed something inequality statistics rarely catch: the rules did not ban anyone. They just priced the maze.
Most arguments about who gets rich start in the same place. Who earns how much? Fair question. Incomplete one. A society can reshuffle the people at the top without moving the overall spread of incomes very much. Builders lose relative ground. Interpreters of the rulebook gain it. The headline measure of inequality barely flinches. The texture of success changes anyway.
Income Shares Miss the More Awkward Question
Income distribution and the distribution of income sources are not the same animal. One tells you how wide the gap is. The other tells you what kind of work, judgment, or access produced the money. I have found that second question more useful whenever a new statute lands with a promise to rein in powerful interests. Powerful interests do not evaporate. They adapt. Sometimes they hire.
Picture an economy where the fattest returns still come from making something people choose to buy. Founders hunt for products. Engineers squeeze waste out of a process. Investors try, and often fail, to back the firms that will still matter in a decade. Now drop a thicker regulatory system on top of that economy. The old activities do not vanish. A second skill set simply starts paying better: reading the statute, satisfying disclosure, securing permission, guessing the next political turn, and, when possible, shaping the rule before it hardens.
The live issue is not only whether a rule trims inequality. It is what happens to the return on creating economic value relative to the return on navigating institutions. If intervention dulls one form of advantage and sharpens another, you get what I think of as elite substitution. The elite does not leave the building. The job description on the door changes.
The elite does not disappear when the rules thicken. Its composition changes, and the Gini coefficient is often the last instrument to notice.
That is an uncomfortable claim, so it is worth walking through slowly. None of what follows says every rule is a mistake. Fraud exists. Disclosure can be thin. Some externalities are real. The point is narrower, and in my view more interesting: even a well-meant rule reallocates talent. People with options notice where the marginal hour pays. Economists have said versions of that for a very long time. There is no special exemption once government writes the incentive.
What Talent Does When the Payoff Shifts
Ambitious people are not a fixed caste. They are a flow. A generation that grows up watching compliance partners out-earn product leads will send more of its sharpest graduates toward the partners. A generation that watches founders capture the upside will send them the other way. Neither path is morally pure. Both are responses to prices.
I have sat in rooms where a bright associate could explain a filing schedule better than the operating business underneath it. That person was not lazy. The market was paying for fluency in process. Multiply that choice across law schools, accounting firms, consulting benches, and in-house teams, and you get a quiet reallocation. Less time on the product. More time on the permission.
Perhaps the most interesting aspect is how ordinary this feels from the inside. Nobody announces a career in elite substitution. They take the role that is open, well paid, and legible to their peers. The aggregate effect shows up later, in who can clear a hurdle and who cannot.
Complexity Has a Fixed Cost, and Fixed Costs Pick Winners
Back to that folder on the table. Sophisticated offshore trusts, in the years before the 2008 crisis, often made economic sense only for estates on the order of tens of millions, with a rough working threshold near the mid-to-high tens. The exact line moved with counsel, jurisdiction, and family messiness. The economics did not. Lawyers, accountants, trustees, and administrators charge whether the estate is huge or merely large. Below a certain asset level, the professional bill can swallow the planning gain.
A household with nine figures can justify strategies an ordinary household should not touch. Same statute. Same formal access. Wildly different net benefit. That is the fixed-cost problem in one domestic scene.
Businesses live a larger version of it. A small firm may struggle to employ a single regulatory specialist. A multinational can staff whole floors of attorneys, accountants, lobbyists, and compliance officers, then spread the cost across revenue the smaller rival does not have. Rules can apply “equally” on paper and still land as a competitive moat.
- Formal equality is not the same as equal burden.
- Fixed compliance costs punish scale that is merely modest.
- Specialist labor becomes a barrier, not just a service.
- The firm that can amortize the maze gains relative advantage.
Here is the paradox I keep coming back to. Regulation aimed at constraining powerful actors can increase their relative edge, because they are the ones who can afford the navigation. We have not necessarily retired privilege. We may have changed its technology. Paper, process, and permission replace the older advantages of plant, brand, or sheer commercial nerve.
Reporting Reform and the Price of Being Public
Consider the post-scandal push, in the early 2000s, to harden financial reporting and rebuild investor trust after spectacular accounting failures. The aim was legible. Cleaner books. Tougher internal controls. Auditors with more to lose. What the statute could not do was make compliance scale smoothly with firm size.
A giant corporation and a small public company can both need auditors, counsel, control systems, and people whose job is the control system. The giant spreads those bills across billions. The smaller issuer cannot. Government auditors later noted that compliance costs, higher in absolute dollars at large firms, were proportionately heavier for smaller ones. Companies moving from an exempt status into the full regime saw a median audit-fee jump on the order of a couple of hundred thousand dollars in the transition year, roughly a low-teens percentage increase. That is not a rounding error for a thin-margin issuer.
Did that statute, by itself, create the modern private-equity complex? No. Plenty of other forces were in motion: cheap credit in some years, founder preferences, the lure of patient capital, the simple desire to avoid quarterly theater. Still, raising the fixed cost of public ownership changes the relative charm of public and private forms. Organizational choice is a price. Change the price, and some activity walks.
That walk matters for a reason retail investors feel directly. Public markets let ordinary savers buy a slice of corporate growth with a brokerage account and a tolerance for volatility. Many private-market doors have historically opened first to institutions and to households already labeled accredited. A rule written partly to protect ordinary investors can, without anyone intending the irony, nudge activity toward venues those same investors enter less easily.
A protection that raises the toll on public ownership can push growth into rooms where the protected have a harder time standing.
A pattern visible across successive market-structure debates
I am not arguing that public markets are sacred or that private capital is a villain. Private owners can be patient. Public markets can be myopic. The narrower claim is about access. If the cost of the public form rises, the set of people who can ride the upside narrows, even when the Gini coefficient of household income looks stable. Who holds the equity is a different statistic from who earns a salary.
Who Can Afford the Maze
Spend time around growing companies and you hear a familiar complaint, sometimes grumbled, sometimes precise. The founder wanted another engineer. The calendar filled with outside counsel instead. Not because counsel is useless. Because a missed filing can be more expensive than a missed feature, at least in the short run. Incentives again.
Large incumbents experience the same rules as a department, not an existential bill. They already employ the specialists. They already sit on industry committees. They already know which examiner asks which question. A new entrant buys that knowledge at retail, one invoice at a time. Over a decade, retail adds up.
| Actor | How complexity lands | Typical response |
| Small public firm | Fixed audit and control costs hit a thin base | Stay private, sell, or shrink the listing ambition |
| Large incumbent | Same rules, spread across huge revenue | Staff a department and treat process as a moat |
| Specialist professional | Demand for interpretation rises | Capture fees that used to stay inside operating firms |
| Ordinary investor | Fewer simple public on-ramps | Hold indexes, or miss the private slice entirely |
Look at that last row twice. The household that was supposed to be sheltered can end up holding a narrower menu. Index funds help, and they are a genuine democratizing tool. They do not restore a lost operating company that never listed. They also do not hand the retail saver a seat in a late-stage private round. Menu design is policy, whether anyone calls it that.
Banking Rules and Yesterday’s Crisis
The same pattern showed up in banking after the 2008 crisis. The legislative response thickened the importance of compliance officers, attorneys, risk specialists, consultants, programmers, and regulatory analysts. Community banks, credit unions, and their trade groups later told government reviewers that selected provisions brought more staffing, more training, more employee hours, and more spending on compliance systems. Again, not a surprise. The statute asked for more process. Process employs people.
The obvious defense is the one you should take seriously. If the apparatus prevents another systemic blow-up, the social return could dwarf the departmental budgets. A crisis avoided is worth a great deal. Households remember 2008 in home equity, job loss, and retirement accounts, not in examiner manuals.
The defense also contains a knowledge problem that does not vanish because the intention was sound. Major financial statutes often answer the failure just observed. Reporting reform followed accounting scandals. The post-crisis banking overhaul followed a housing-and-leverage crisis. The next break need not look like the last one. Institutions adapt. Capital moves. Technology rewires the pipes. Products appear at the edge of the old definitions, and risk migrates toward whoever is least watched.
Stability frameworks inside central banks tend to admit this outright. Shocks are hard to forecast, so the practical work tilts toward monitoring vulnerabilities rather than naming the next headline. That humility is healthy. It also means we should be humble about how precisely a backward-looking rulebook buys safety.
- The failure is observed and politically urgent.
- The statute hardens controls around that failure’s shape.
- Firms staff up to satisfy the new shape.
- Activity and risk drift toward less supervised edges.
- The next shock arrives wearing a different coat.
None of those steps proves the statute was worthless. Higher capital, thicker liquidity, and cleaner risk controls can make institutions sturdier. I would rather hold deposits at a bank with a real capital cushion than at one running on optimism. The costs, though, are easy to see: departments, legal invoices, reporting systems, management hours pulled off lending and into documentation. One of the largest claimed benefits, the crisis that did not happen, is much harder to observe. You cannot invoice a counterfactual.
So the economic question stays stubborn. Do the marginal resources poured into regulation make the system safer enough to justify their opportunity cost? Opportunity cost is not a slogan. It is the loan not made, the product not shipped, the analyst who became a control tester instead of a credit officer. Sometimes that trade is wise. Sometimes it is an expensive rehearsal of the last war.
When Political Knowledge Starts Paying Like a Product
Healthcare reform in the United States offered a cleaner window onto a related mechanism. Change subsidies, insurance rules, reimbursement formulas, and the scope of government-financed coverage, and you change expected revenues across a whole industry. Firms do not need a conspiracy to care. Cash flows are enough.
Economists studying a surprise Senate result in early 2010, a vote that suddenly lowered the odds that pending health legislation would survive in its expected form, found sharp and uneven market moves. Managed-care firms saw abnormal returns on the order of 6 percent. Drug companies moved roughly 2.8 percent. Healthcare facilities took abnormal losses near 3.5 percent. One political evening, several business models repriced.
That does not prove the gains and losses were pure political rents. A hospital can become more valuable under broader insurance simply because more patients can pay. A payer can lose if the same expansion squeezes margins. The demonstration is still important. Government rules can move expected private cash flows enough that political events get capitalized into asset prices. Once reimbursement, subsidies, and eligibility sit inside the business model, understanding government becomes part of strategy.
Political knowledge acquires economic value. When a hearing, a waiver, or a formula revision can create or destroy substantial corporate worth, firms will spend real money anticipating, navigating, and influencing those decisions. That spending is rational. It is also a diversion from whatever else those dollars and those people might have done.
A rough mental model:
  Market return = product people want, minus cost to deliver it
  Political return = rules that shift cash flows, minus cost to shape or satisfy them
  Talent follows whichever spread is wider
I do not think this model captures everything. Culture matters. Luck matters. Some founders ignore the spread and build anyway. On average, though, the spread wins. If mastering the rule pays more than mastering the customer, do not be shocked when the conference rooms fill with people who master the rule.
What a Single Inequality Score Cannot See
Imagine two economies with identical income distributions. In the first, high incomes depend mostly on success in markets: a product that sells, a process that cuts cost, a capital allocation that was right more often than wrong. In the second, high incomes depend much more on navigating political and regulatory institutions. The inequality coefficient can match. The economies do not.
That is why inequality statistics tell a partial story. We measure how much income arrives. We ask less often which activities generated it. A lawyer who bills a compliance mandate and an engineer who ships a tool can land in the same income decile. Their effect on the pie is not identical. One may be a necessary cost of trust. The other may be the trust’s underlying reason for existing. Sorting them requires judgment, not just a percentile.
In my experience, public debate collapses those roles too fast. “Top earners” becomes a single moral category. Sometimes that category deserves scrutiny. Concentrated gains can come from barriers, not brilliance. Sometimes the category hides a founder who took a decade of losses before the number printed. Averages are blunt. Sources are the interesting part.
Benefits Are Real, and So Is the Blind Spot
It would be lazy to stop at suspicion. Preventing fraud, improving disclosure, and correcting genuine externalities can create social value. A market full of cooked books is not a free market. It is a casino with a marked deck. Investors who cannot trust the numbers demand a discount, and honest firms pay for the dishonest ones. Some rules earn their keep on that ground alone.
Elite substitution and a smaller economic pie are separate propositions. You can reshuffle who captures surplus without shrinking surplus. You can also do both at once. A compliance industry can be a transfer, a deadweight cost, or a real reduction in fraud losses. The mix is empirical, and it will not be the same in securities law, bank capital, drug approval, or housing permits. Painting every statute with one brush is how arguments go stale.
Still, every society has a limited stock of unusually talented and ambitious people. Institutions decide what those people are paid to do. Do the highest returns come from inventing products, building companies, and allocating capital with a decent hit rate? Or do they come, increasingly, from mastering the rules that govern those activities? The question sounds abstract until you watch a hiring season.
Incentive check: if navigation pays more than creation, expect more navigators.People respond to incentives. That sentence is old enough to be boring, which is usually a sign it is true. There is no clean reason it should stop operating when the public sector writes the price list. Subsidies, bans, mandates, tax credits, and disclosure regimes are prices. Some are posted. Some are hidden in time and legal risk. Talent reads both.
A Closer Look at Small Banks and Thin Margins
Community lenders are a useful stress test of the fixed-cost idea, because their economics are already tight. A regional giant can absorb a new reporting build as a line item. A bank with a handful of branches experiences the same build as a hiring decision: one more specialist, or one less lender. Industry groups have been consistent on the direction, if not always on the exact dollar figure. Selected post-crisis rules coincided with more staff time, more training, and more systems spend.
Does that mean every small bank was harmed, or that every rule should be rolled back? No. Some small institutions were fragile for older reasons: concentrated loan books, weak underwriting, local economies that turned. Sorting those causes is the actual work. What you should not do is pretend a uniform rule has a uniform weight. Proportionality is not a slogan for lobbyists. It is arithmetic.
Borrowers feel the arithmetic indirectly. If compliance crowds out credit officers, the marginal small-business loan gets a slower yes or a quieter no. Credit tightening can be prudent. It can also be an accidental byproduct of a process designed for a balance sheet ten times larger. I would rather see that trade debated in the open than buried inside a claim that “the sector is safer” with no denominator attached.
Private Markets Are Not a Conspiracy, but They Are a Filter
When public ownership gets more expensive, private ownership looks kinder. Founders keep control. Reporting calendars loosen. A single sponsor can replace a scattered shareholder base. Those are real advantages, and some of the best operators prefer them for reasons that have nothing to do with dodging oversight. Long projects do not always fit a ninety-day script.
The filter is the part worth naming. Historically, many of those vehicles have been reserved for institutions and for individuals who already clear income or net-worth tests. The tests exist, in part, to keep unsophisticated savers out of illiquid, opaque deals. That protection has a cost. The same saver is then absent from a growing slice of corporate value creation. Protection and exclusion can share a doorway.
Recent years have nibbled at the doorway, with interval funds, private-market sleeves inside broader products, and arguments about who counts as sophisticated. Nibbling is not the same as opening. Fees inside those wrappers can be heavy. Liquidity can be a brochure word. A household that buys the wrapper is not in the same position as the endowment that negotiated terms a decade earlier. Access is a spectrum, not a switch.
Investors Should Watch the Toll, Not Only the Narrative
If you allocate capital for a living, or simply for a retirement that has to last, the practical read is less ideological than the comment sections suggest. Ask where the toll is rising. A sector that suddenly needs more permission will spend more on permission. Margins can absorb that, or they cannot. Valuation multiples that assume the old cost structure will be wrong.
- Rising fixed compliance cost favors scaled incumbents over thin challengers.
- Rules that reprice cash flows make political calendars part of the investment case.
- Migration from public to private changes who can own the upside.
- Specialist fees are a transfer until they crowd out productive work, and then they are a cost.
- Safety benefits are real when they are real, and invisible when they are only asserted.
None of those bullets tells you to buy or sell a ticker. They tell you which questions are worth an afternoon. I have found that management teams reveal a lot when you ask how many people they added in control functions versus customer-facing roles over five years. The ratio is not destiny. It is a clue.
The Housing of Advantage Inside Process
There is a temptation to treat process as morally neutral, a kind of plumbing. Sometimes it is. A checklist that stops a repeated error is cheap insurance. The trouble starts when process becomes the product. Firms then compete on their ability to file, not on their ability to serve. Customers still matter, but they matter later, after the gate.
Think of a city that requires seventeen permits for a small expansion and three for a large one, because the large developer keeps a permitting team on salary. The code never says “prefer the incumbent.” The calendar does. Financial regulation can work the same way without a single corrupt official. Delay is a cost. Predictable delay is a smaller cost if you can staff for it. Unpredictable delay is a tax on the undercapitalized.
I am wary of romanticizing the undercapitalized. Some small firms are small because the idea is weak. Scale is not a sin. The policy mistake is accidental scale bias dressed up as consumer protection. If the goal is cleaner markets, design the obligation so a capable small firm can meet it without hiring a department. Thresholds, phased rules, and shared utilities for reporting are boring tools. Boring tools are how you avoid the paradox.
A Note on Measurement, Before the Argument Gets Lazy
Critics of this line of thought sometimes hear a demand to scrap measurement. That is not the demand. Income shares, wealth shares, and mobility tables still matter. They describe outcomes. They do not describe mechanisms. Adding a crude look at occupational mix at the top, or at the share of high incomes tied to regulated chokepoints, would tell a fuller story. It would also be contested, which is fine. Contested data beats a single coefficient treated as a moral verdict.
Event studies, like the health-legislation surprise, are another partial window. They show that rules move prices. They do not, by themselves, prove rents. A price can move because a real customer just became able to pay. Reading the move requires industry knowledge, not only a t-statistic. Good analysis is allowed to say “both.”
Cost studies have their own traps. Firms asked about regulatory burden have a reason to talk their book. That does not make the burden fictional. It means you cross-check: audit-fee data, headcount disclosures, exit from public lists, entry rates in a licensed trade. When several imperfect measures point the same way, you can hold the conclusion with a lighter grip and still hold it.
What “Making the Pie Smaller” Actually Means
Redistribution is a transfer. A smaller pie is a loss of output that nobody receives. The distinction sounds tidy and is messy in practice. A fee paid to an auditor is income for the auditor and a cost to the issuer. If the audit stops a fraud that would have destroyed more value than the fee, the pie grew, or at least shrank less. If the audit is a ritual that catches nothing incremental, the pie took a nick and the auditor’s income is the nick’s other side.
Over a whole economy, the nicks compound when talented people spend careers on rituals. They do not compound when those careers stop real harm. The difficulty, and it is a genuine one, is that harm prevented is quiet. Harm invented by a bad rule is also quiet, until a firm never forms. Both silences invite storytelling. I prefer the version that keeps the opportunity cost on the page.
Did the rule move surplus from one pocket to another, or did it also shrink the surplus? Those are different claims, and only one of them shows up cleanly in an income table.
Sarbanes-style reporting reform, the post-crisis banking package, and the health-coverage overhaul addressed different failures and may each have produced important benefits. Lumping them together as “regulation” is too coarse for design and too convenient for rhetoric. What they share is the question conventional inequality talk often skips. When government changes the rules, does it retire economic privilege, or does it change who is best positioned to capture it?
A Practical Reading for Households, Not Only for Firms
Households meet this machinery in smaller rooms. A tax strategy that is rational at one asset level is a toy at another. An insurance design that assumes a navigator in the family punishes the family without one. A retirement menu full of opaque alternatives looks like choice and functions as a filter. The pattern rhymes, even when the statute is different.
The sensible personal response is not cynicism. It is literacy. Know which doors have a fixed toll. Do not buy complexity you cannot monitor. Prefer structures you could explain to a skeptical friend. And when a product’s main charm is that it slips past a rule, ask who is being slipped past, and whether that person is you.
On the public side, the sensible ask is proportionality and sunset. A rule that cannot say what it costs, and what harm it claims to prevent, is a rule living on narrative. Narratives are sticky. Spreadsheets are less so. I would take the spreadsheet.
The Last Question Is the One Worth Keeping
We can argue for a long time about whether a given statute was worth it. Some were. Some aged badly. Some did both, depending on the clause. The durable issue sits underneath the score-settling. Talented people will go where the return is. If navigating the rules pays more than creating value outside them, the economy will grow more navigators. That may be the price of trust. It may also be a habit we stopped noticing.
So the closing question is plain enough to fit on a card. When the rules changed, did we redistribute the pie, or did we also make it smaller? And if the people best positioned to answer are the ones billing by the hour to interpret the change, we should at least hear from someone who still has to sell a product on a Tuesday.



