
I keep a small, slightly dog-eared print of a water garden above my desk, the kind you buy in a museum shop and then forget to frame properly. It is not valuable. It is not even particularly accurate. Still, every time a late canvas by Claude Monet surfaces with a number attached that would buy a street of houses, I catch myself leaning in. Not because I expect to bid. Because the gap between a postcard and a room full of people deciding what beauty is worth has always felt slightly absurd, and slightly revealing. This autumn, that gap is on full display in Paris.
Art market watchers have spent the better part of two years looking for a reason to sound less gloomy. Sales cooled. Guarantees got fussier. Sellers who could wait, waited. Into that cautious mood comes a cluster of Monet pictures timed, almost theatrically, around the hundredth anniversary of the painter’s death in December 1926. He was born in Paris in 1840. The city that shaped him is now being asked to price him again, in public, at the start of the season that usually sets the tone for the rest of the year.
Why A Handful Of Canvases Can Move An Entire Season
One picture does not make a market. I have watched enough sale weeks to know that. A single trophy can, however, change the temperature in the room. If the right buyers show up, if the telephone banks stay busy, if a work that has lived quietly in a private collection finds a new home without a struggle, the story that travels afterwards is simple: demand is not dead. If that same picture stalls, the story travels just as fast, and it is harder to walk back.
That is the awkward power of a marquee lot. It is both an object and a signal. Collectors who would never touch an Impressionist landscape still read the result, because it hints at how freely money is moving at the top. Dealers use it in conversations the following week. Museums watch the underbidders. And journalists, myself included, are a little too ready to treat one hammer as a verdict on an entire category.
A Centenary That Happens To Be Convenient
Anniversaries are useful. They give consignors a narrative, and narratives help estimates feel less naked. Monet’s death a hundred years ago this December is a clean hook. It is also, if I am being honest, a convenient one. The pictures would have been interesting without the date. The date simply makes the interest easier to explain at a dinner.
Paris is the right stage for it. He was born there. The late work that now carries the heaviest expectation was painted far from the capital, in the garden at Giverny, but the sale itself returns the argument to the city. There is a neatness to that which auction houses understand very well. Geography, biography and price, arranged so a newcomer can follow the plot in a single paragraph.
What The Market Has Been Missing
The last few seasons have not been a collapse so much as a narrowing. Fresh, well-provenanced material at the very top still found buyers when the quality was obvious. Everything else had to work harder. Estimates that might have looked polite in 2021 started to look hopeful. Sellers who needed a number, rather than a story, often chose to wait.
Into that setting, a group of Monets is being offered as evidence that the autumn can still be busy. I am not sure a painter, even this painter, can carry a whole season on his back. I am sure he can fill a room. Those are different claims, and it is worth keeping them apart when the headlines start to blur them.
The Picture That Barely Existed In Public
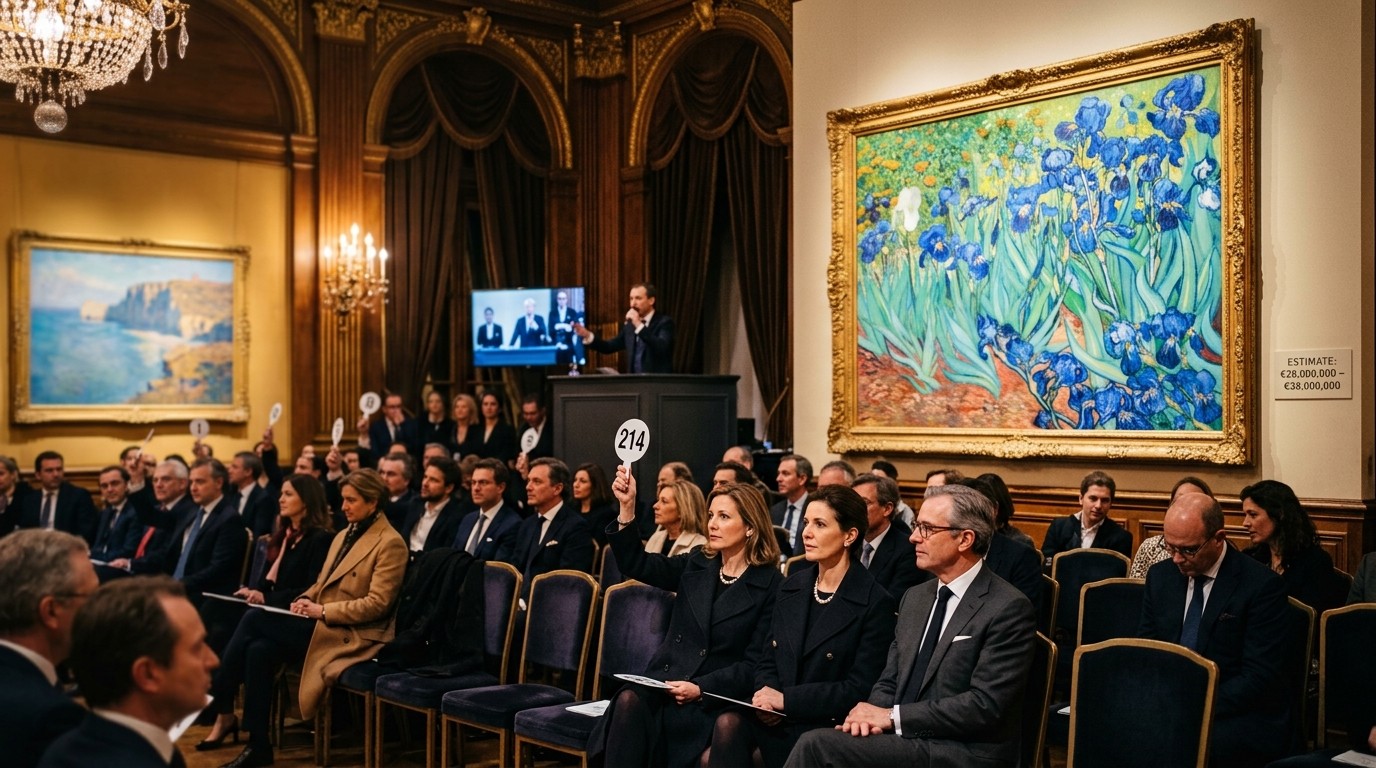
The lead work is Iris, a large late canvas painted in the garden at Giverny only a few months before Monet died. It is one of a small number of pictures from that moment that do not sit in a museum. For years its existence was known mainly through a black-and-white photograph. Colour, scale and surface were rumours. That changes when a canvas comes into a sale room and people can stand in front of it.
There is something slightly uncanny about a painting that has lived, for practical purposes, as a document. Collectors like to talk about “seeing it in the flesh,” and for once the cliché earns its keep. A photograph flattens. It also lies a little about density. Late Monet is often about paint that has been worried, layered, and left to do the work of description. You cannot price that from a grey reproduction, not really.
A picture known mostly from a photograph is not the same object as a picture you can walk up to. The second one can surprise you. The first one can only suggest.
It leads a single-owner sale built around works assembled by Jeanne Schlumberger across roughly four decades from the 1950s. Single-owner evenings have their own weather. The collection has a shape. The estimates talk to each other. A strong result at the top can pull the middle with it, or it can leave the middle looking suddenly expensive. I have seen both.
An Estimate That Rewrites A Local Record
Iris carries an upper pre-sale estimate of €30 million. That figure is being described as the highest ever placed on a painting at auction in France. Estimates are not prices. They are invitations, and sometimes they are warnings. Still, the number matters because it resets what a French sale room is willing to ask in public.
Why so high? Partly rarity outside museums. Partly scale. Partly the story the specialists want the picture to tell. They argue it does not simply close the Impressionist chapter. It opens onto modernism and abstraction, the territory Monet was testing in the mid-1920s as his eyesight failed and his garden became less a view than a field of colour. I find that reading persuasive, up to a point. Late Monet has been recruited for that argument for decades. The recruitment does not make it false. It does make it familiar, and familiar arguments need the object to do some of the persuading.
A second late picture sits in the same sale: Saule pleureur, the weeping willow painted in 1918–1919, estimated at up to €12 million. Willows from those years carry their own weight. They were painted during and just after the war, and they have often been read as mourning pictures, whether or not Monet meant them that narrowly. Pairing a willow with a late iris gives the evening two moods from the same hand. One is elegiac. The other is almost violently alive. That contrast is good theatre. It is also a fair summary of the last decade of the career.
What Specialists Mean By The Turn Toward Abstraction
Talk of abstraction around Monet can get loose. He did not abandon the motif. The garden is still the garden. The bridge, the pond, the irises, the willow: they remain nameable. What changes is how much of the picture is allowed to be paint before it is allowed to be a place. Edges soften. Local colour spreads. The eye stops hunting for a horizon and starts tracking rhythm.
In my experience, buyers who respond to that shift are not always the same buyers who want a crisp Norman beach from the 1880s. One group is collecting a view. The other is collecting a decision about seeing. Both are legitimate. They do not always bid against each other, which is why two Monets in one week can tell two different stories even if both sell.
The Other Monet, On The Same Night
Paris is not offering only the late work. On the same date, 22 October, a rival house is leading a sale of pictures from the collection of Paul Durand-Ruel, the nineteenth-century dealer who backed Monet when that was not the obvious commercial bet. The lead lot there is Bord des falaises à Pourville, an Impressionist coastal picture painted during a stay at Pourville-sur-Mer in 1882.
Specialists rank it among his strongest accounts of the Norman coast. The estimate sits in the region of €11 million to €15 million. That is serious money. It is also a different proposition from a €30 million late garden. One picture asks you to admire a mature Impressionist solving a landscape problem in daylight. The other asks you to follow him to the edge of what the landscape can hold.
I like that they land on the same evening. It stops the week from becoming a single sermon about “the last Monets.” There is a market for the earlier, more descriptive work, and it has its own collectors, its own comparables, its own ceiling. Treating all Monets as one asset class is how people get surprised.
A Dealer’s Collection Has A Different Pulse
Durand-Ruel is not a neutral name in this story. He bought when few others would, showed the work, and waited. A sale drawn from his collection carries a provenance that is almost a short history of how Impressionism became acceptable. Provenance does not guarantee a price. It does remove one of the questions bidders like to ask when a picture appears from nowhere.
Coastal Monets from the early 1880s also have a practical advantage. People can see what they are. Cliffs, sea, weather, a path. The difficulty is in the handling, not in the subject. For a buyer who wants Impressionism to look like Impressionism, that clarity is a comfort. Late gardens ask for more patience, and patience is not evenly distributed in a sale room.
Young Cézanne, Detached From A Wall
The Schlumberger evening is not a one-artist affair. Among the other highlights are three canvases by a very young Paul Cézanne: La Ferme, Arbres au Bord de la Rivière and Ciel Entre les Arbres. They were painted in 1862–1864 as parts of a single large mural at his home in Provence. The mural was later taken off the wall and transferred to canvas. These three fragments carry upper estimates between €600,000 and €800,000.
Early Cézanne is scarce in the way that makes specialists use careful language. The pictures have been designated Trésors nationaux, a French status reserved for works judged important to the country’s cultural heritage. That label is not a price. It is a constraint and a compliment at once. It signals that the state has an interest in where the work ends up, and it tells private buyers that they are not looking at a casual sketch from a student year.
I find the mural story more moving than the estimate. A young painter covering a wall at home, the wall later cut into movable pictures, the pictures now asked to perform as independent works of art. Something is gained, portability, and something is lost, the sense of a room. Auctions are good at pricing what can be moved. They are less good at pricing what a wall used to mean.
| Work | Date | Upper estimate | Why it matters |
| Iris | Months before 1926 | €30 million | Rare late garden picture, long known mainly from a photo |
| Saule pleureur | 1918–1919 | €12 million | Wartime willow, second late Monet in the same evening |
| Bord des falaises à Pourville | 1882 | €15 million | Coastal Impressionist picture from a dealer’s collection |
| Three early Cézanne panels | 1862–1864 | €600,000–€800,000 | Fragments of a Provence mural, heritage status |
Read that table as a map, not a forecast. The spread of dates is the interesting part. A single week in Paris is being asked to hold student Cézanne, mature coastal Monet, and the last garden. If you want a compressed history of how French painting moved across sixty years, you could do worse than walk those rooms in order.
Heritage Status Is Not Just A Plaque
When a work is marked as nationally important, the bidding psychology shifts. Some buyers step forward because the label confirms quality. Others step back because export, matching rights, or a public claim can complicate a purchase. I am not a lawyer, and the fine print differs by case. The practical effect is simpler: the audience changes. A picture with that status is never only a private luxury. It is also a piece of an argument about what a country should be able to keep.
For the Cézanne panels, that argument is easy to sympathise with. They are early, they are local, and they are fragments of something that once belonged to a house. Whether sympathy translates into bids is another matter. Heritage sales can be quiet in a way that has nothing to do with indifference.
How Estimates Get Built, And How They Fail
People outside the trade often treat an estimate as a prediction. It is closer to a negotiated range. Specialists look at comparable sales, condition, size, subject, provenance and the seller’s floor. Then they guess how many real bidders exist for this exact object, not for the artist in general. A Monet is not a Monet. A late, large, fresh-to-market iris is a different animal from a small coastal study that has been offered twice in a decade.
Estimates fail in two directions. They can be timid, and the lot then sells for a multiple that makes the catalogue look naïve. They can be proud, and the lot then stalls, which is worse for the season’s mood than a modest result on a modest estimate. The €30 million upper figure on Iris is proud by French auction standards. Pride can be earned. It can also clear the room of everyone except the two people who were always going to be there. If those two people are real, pride looks like foresight. If they are not, it looks like a press release.
- Freshness to the market, especially after decades in one collection
- Museum scarcity, which shrinks the pool of comparable private pictures
- Scale and condition, both hard to judge from old photographs
- A readable story, centenary, garden, last months, turn toward abstraction
- The number of collectors who can actually write the cheque
That last point is the one catalogues rarely dwell on. At this level the buyer pool is small enough to have names. Some of those names are institutions with committees. Some are private, and private buyers can vanish between the viewing and the sale for reasons that have nothing to do with the picture. A family office rebalances. A currency moves. A competing lot in another city takes the oxygen. I have seen a “certain” picture become suddenly lonely because two of the five plausible bidders were occupied elsewhere that week.
Guarantees, Quiet Floors, And The Story Afterwards
Not every strong result is a spontaneous competition. Third-party guarantees and irrevocable bids can put a floor under a lot before the room opens. There is nothing illicit about that. It is a way of sharing risk. It does change what a hammer price means. A picture that sells on a single bid at the reserve tells you the seller was protected. It does not tell you the market was hungry.
Perhaps the most interesting aspect of this particular week is that the public narrative is already written in outline. Recovery, centenary, Paris, record estimate. The sale has to live up to a sentence that exists before anyone raises a paddle. That is a heavy sentence to carry. If the pictures do well, the sentence will be repeated as if it had been obvious. If they struggle, the same writers will discover, overnight, that the season was always fragile.
What A Bumper Season Would Actually Look Like
A bumper autumn is not one picture selling well. It is depth. It is the second and third lots finding bidders. It is a day sale that does not collapse once the evening glamour leaves. It is sellers in November feeling brave enough to consign, because October did not punish them. One Monet at €30 million, even if achieved, is a headline. A run of solid results across Impressionist, modern and contemporary catalogues is a season.
I would watch the Cézanne panels and the willow almost as closely as the iris. Trophy lots can be won by a single determined buyer. Mid-estimate works need a crowd. Crowds are what have been thinner. If the crowd returns for a young Cézanne fragment and a 1919 willow, that is more informative than a duel at the top.
Headlines are written about the lot that leads. Markets are built by the lots that follow.
– A specialist who prefers not to be quoted before the sale
Giverny, Sight, And The Last Months
It is easy to romanticise the garden. Monet built it, planted it, and then painted it until the planting and the painting were hard to separate. By the mid-1920s his sight was badly compromised. Cataracts change colour. Surgery changes it again. The late canvases have been argued over for a century partly because we cannot be sure how much of the blaze is choice and how much is a visual system under strain.
I do not think the medical story reduces the pictures. If anything, it makes the estimate debate more human. We are pricing decisions made by a man who could not see the way he once saw, in a garden he could still walk. That is not a selling point in the crude sense. It is context. Buyers who ignore it are buying a brand. Buyers who lean on it too hard are buying a biography. The canvas has to survive both.
Iris, painted so close to the end, sits at the extreme of that problem. A few months of life left. A large surface. A motif he had circled for years. If the picture holds together as a structure and not only as a haze, the modernist reading has something to stand on. If it is mainly atmosphere, the price has to be carried by rarity and name. Both outcomes are possible. The viewing will matter more than the essay in the catalogue.
Pourville And The Earlier Confidence
Set that beside Pourville in 1882 and you see a different kind of confidence. Monet was in his early forties, working the Norman coast, repeating motifs the way he liked to repeat them, under changing light. The cliffs are a subject with a clear job. They locate you. The sea does what the sea does. The skill is in the interval between description and weather.
Collectors who prefer this period often say they want Monet before the brand became a water-lily franchise. That is a little unfair to the late work, which is stranger and riskier than the gift-shop version suggests. It is also an understandable taste. A cliff picture does not require you to accept a theory about the birth of abstraction. It requires you to accept that this painter could make a coast feel temporary. For some buyers, that is enough, and €11 million to €15 million is the price of enough.
Private Collections And The Long Hold
Jeanne Schlumberger’s pictures were gathered over about forty years from the 1950s. That is a long hold by any market standard. Long holds do two things. They create freshness, which bidders like. They also create a gap between what the collector paid and what the market is now asked to pay, which can make a family feel either vindicated or suddenly exposed.
Single-owner sales succeed when the collection has a point of view. A scatter of famous names is not a point of view. A taste you can describe in a sentence is. From what has been shown, this one mixes late Monet with very early Cézanne and, presumably, other works that fill the decades in between. The evening will feel coherent if the hanging and the catalogue respect that span instead of shouting only about the iris. I hope they do. The quieter lots are where you learn whether the taste was real.
France As A Sale Room, Not Only A Subject
A record estimate for a painting in France is also a claim about place. For years the biggest Impressionist prices have often been achieved in New York or London, with Paris strong but not always the room where the final duel happens. Putting €30 million on a Monet in Paris is a way of saying the local room can host that conversation. Whether the bidders are local is a separate question. Money travels. The gavel still has an address.
There is civic pride in that, and there is commerce. A successful French evening helps the houses argue that consignors need not automatically ship their best pictures abroad. It helps related businesses, from shippers to insurers to the restaurants near the sale room, but those are side effects. The core bet is that a buyer with €30 million to spend will sit, or phone in, for a Paris catalogue if the picture is right.
I have a soft spot for that bet. Not out of patriotism. Out of a preference for pictures being sold near the culture that made them, at least some of the time. It is sentimental, and sentiment is a poor analyst. It is also not a ridiculous preference.
Risks The Cheerful Preview Skips
None of this is guaranteed, and it would be slippery to pretend otherwise. A few risks are obvious enough to list without pretending to inside knowledge.
- The estimate on the lead picture may sit above the level where more than one bidder is comfortable.
- Two major Monets on the same night can split attention rather than compound it.
- Heritage rules around the Cézanne panels may narrow the private pool.
- A wider market that is still selective may applaud the trophies and ignore the rest.
- Currency and rate nerves can sidelined buyers who were real three months ago.
There is also the risk of over-reading. If Iris sells well, it will not prove that mid-market Impressionism is healed. If it fails, it will not prove that Monet is out of fashion. It will prove something narrower: that this picture, at this number, on this night, did or did not find its person. The temptation to generalise will be strong. I intend to resist it, and I will probably fail a little.
How A Careful Buyer Might Think About It
Most of us are not in this room except as readers. Still, the discipline is transferable. If I were advising someone who actually could bid, I would keep the questions plain.
- Have you stood in front of it, or are you buying the photograph you already knew?
- What did a truly comparable canvas, not merely the same artist, sell for in the last decade?
- Is the estimate a range you can live with, or a number designed to be news?
- What happens to your plan if you are the only bidder at the reserve?
- Do you want the picture, or do you want the story of having bought the picture?
That last question sounds moralising. It is practical. Story-buyers pay the widest spreads and feel the sharpest regret when the next comparable appears. Picture-buyers can overpay too, but they at least know what they overpaid for. At €30 million the difference is not philosophical. It is a house, or several.
Condition, Frames, And The Things Catalogues Soften
Late Monet surfaces can be delicate in ways a headline does not capture. Thick paint moves. Linings age. Transfers, in the Cézanne case, introduce their own history of intervention. A responsible buyer reads the condition report as carefully as the essay, then asks a conservator to translate it out of catalogue dialect. “Stable” is not the same as “untouched.” “Original frame” is pleasant and rarely decisive.
I mention this because centenary excitement is a poor substitute for a torch and a raking light. The picture that looked mythical in a press release can look tired under exhibition lighting, or it can look better than the myth. Either result should be allowed to change the bid. Loyalty to the preview is how people end up defending a purchase they no longer like.
The Wider Autumn, Beyond One Painter
Auction seasons are ecosystems. Impressionist evenings sit beside modern sales, jewellery, design, and the contemporary catalogues that have dominated conversation for fifteen years. A strong Monet week can lift mood. It cannot, by itself, refill a contemporary day sale that has too many similar works at hopeful estimates. The hope attached to these pictures is real. It is also local.
What would spill over? Confidence among consignors. If owners of other blue-chip pictures see Paris clear material at or above estimate, a few of them will call their advisers in November. That pipeline effect is the closest thing the trade has to a bumper season. It is slow, and it is invisible on the night. The night only supplies the excuse.
A simple way to read the week:
  Trophy result = headline
  Mid-lot depth = market
  Later consignments = season
I wrote that on a notepad during a previous October and have not improved it. Trophy, depth, pipeline. If you remember nothing else from the previews, those three words will keep you more honest than the centenary language.
Why Impressionism Still Clears A Room
There is a fashion, in some corners of the trade, to treat Impressionism as settled, almost sleepy, a category for people who want beauty without an argument. The sales do not quite support the sneer. When the picture is right, the category still produces prices that make contemporary dealers go quiet. The audience is broad. It includes museums, long-term private collectors, and newer money that wants an asset people recognise without a briefing.
Recognition is underrated as a financial fact. A Monet does not need to be explained at a dinner in the way a difficult conceptual work does. That ease has a monetary value. It also has a ceiling, because ease attracts supply, and supply is what eventually disciplines prices. The late garden pictures are protected, somewhat, by how many of them museums already hold. Protection is not the same as a guaranteed bid.
Abstraction As A Selling Word
I should be plain about the language around Iris. Calling it the opening of modernism is a way of attaching the picture to a later, often more expensive, history. It invites buyers who collect the twentieth century to see Monet as a precursor rather than a destination. That invitation has been extended before, sometimes successfully. It works when the surface actually behaves like a precursor, when the structure feels exploratory rather than merely soft.
If the invitation is only verbal, sophisticated buyers notice. They have heard “bridge to abstraction” applied to a lot of late Impressionism that is simply late Impressionism. The phrase is not banned. It has to be earned in front of the canvas. My own bias, for what it is worth, is to trust the picture over the paragraph. Paragraphs are cheap. Paint at that scale is not.
A Note On Photographs And Memory
There is a small melancholy in the fact that Iris lived so long as a black-and-white image. Whole arguments about colour, which is the point of the late garden, were being conducted without colour. Scholars can do a great deal with documents. They cannot recover a pigment from a grey plate. The sale, whatever price it produces, returns the picture to colour in public. That is a cultural event even if you find the money faintly ridiculous.
I do find the money faintly ridiculous, some days. Then I remember what people pay for things that are easier to reproduce, and I calm down. Scarcity plus a name plus a century of agreement that this hand mattered: that combination has always attracted large cheques. The cheque is not the meaning. It is the trace the meaning leaves when it passes through a market.
What I Will Be Watching On The Night
Not the opening bid. Opening bids are theatre. I will watch whether a second bidder appears once the estimate range is entered, and whether that bidder is on the telephone or in the room. I will watch the willow, because a second late Monet is the control experiment. I will watch whether the coastal picture, in the other house, feels like a separate market or like an echo. And I will watch the early Cézanne panels for signs of life below the trophy line.
If all of that goes well, the hopeful previews will have been fair. If only the iris sells, and sells to one bidder at a negotiated figure, the previews will have been advertising. Both are normal. The difference is worth keeping, especially if you allocate money, or attention, on the back of seasonal mood.
Mood Is Not A Strategy
Seasonal mood is contagious. A good October makes November phone calls easier. A bad one makes owners clutch. The rational response is to separate the object from the weather. A great late Monet is a great late Monet in a soft week. A stretched estimate is stretched even if the room is cheerful. I have broken this rule often enough to recommend it with a straight face.
For readers who collect nothing more expensive than the print above a desk, the week is still worth following. It is a public argument about value, conducted with paddles instead of essays. You can disagree with the number and still learn something about what a culture is willing to concentrate in a single rectangle of linen. That concentration is old. The euro amount is new. The impulse is not.
After The Centenary Noise Fades
December will come, the anniversary pieces will be published, and the pictures will be either in new houses or back in storage. Anniversaries end. Ownership does not. The buyer of Iris, if there is one at a number near the estimate, will spend years lending it, insuring it, and explaining it. That afterlife is part of the price, though it never appears in the catalogue.
The seller’s afterlife is simpler and harder: life without the picture. Collections assembled over forty years are not inventories. They are rooms people walked through. A sale converts rooms into results. Some families find that clarifying. Some find it bleak. The market records only the clarifying part.
I keep coming back to the black-and-white photograph. For years it was the public stand-in for a painting most people would never see. Soon there will be a price, a buyer, and a new set of photographs in colour. The object will be less mysterious and more definite. That is what auctions do. They end a certain kind of rumour. Whether they start a healthier season is a question the following catalogues will answer, not the night itself.
A Fair Reading, Before Anyone Bids
So here is the reading I would defend today, with the sales still ahead. Paris is offering a genuinely interesting group of pictures, not a manufactured theme with thin material behind it. A late iris with a thin public history, a weeping willow from the war years, a strong coastal Monet from a dealer’s collection, and early Cézanne panels cut from a mural: that is a real week. The €30 million estimate is a statement as much as a valuation. Statements can be backed up by bids. They can also hang in the air.
Hopes for a bumper autumn are understandable. They are not the same as evidence. Evidence will look like depth, not like a single headline. If you care about the market, watch the lots that do not lead. If you care about the painter, go and stand in front of the canvas that a photograph kept half-hidden. The rest, the records, the recovery talk, the seasonal adjectives, can wait until the room has spoken.
I will still glance at the print above my desk when the results come in. It will not have changed. The distance between it and the picture in Paris will have a number attached, for a day or two, and then the number will become just another comparable. That is the unromantic end of every romantic sale. It is also why the next owner, whoever they are, should want the painting more than they want the comparables.