
I still remember the first time someone tried to explain a modern lithography scanner to me over coffee. “Picture a double-decker bus,” they said, “except it weighs about 180 tonnes, costs more than a small fleet of private jets, and its job is to draw lines thinner than a virus.” I laughed. Then I looked up the price. The laugh died. A single extreme ultraviolet machine can run past €180 million, and the newer high-numerical-aperture versions clear €350 million. If that sounds absurd, wait until you see who has no choice but to buy them.
That buyer’s list is short and famous: the foundries and chipmakers that actually manufacture the processors inside phones, data centres and the latest AI accelerators. They can design almost anything. They cannot, at the leading edge, print those designs without one Dutch company. In 2025 that company booked revenue on 48 of those extreme ultraviolet systems and €32.7 billion of sales overall, including €8.2 billion from looking after machines already sitting on factory floors. Gross margin sat at 52.8%. Net income was €9.6 billion. Those are not start-up numbers. They are the numbers of a firm that spent four decades becoming very hard to copy.
From a Cash Drain to the Machine Nobody Else Sells
The origin story is less glamorous than the moat. The business was set up in 1984 as a joint venture between a large electronics group and a specialist in semiconductor tools. One partner already had a lithography system on the bench. The other knew manufacturing equipment. The market they walked into was crowded with American and Japanese incumbents, and customers were scarce. Cash went out faster than orders came in. One parent eventually walked away. The other was cutting costs. Survival was a management decision more than a market verdict.
I’ve found that the companies which later look inevitable often spent their first decade looking optional. This one did. Rather than trying to invent every mirror, laser and stage in-house, management treated itself as an integrator. Specialists handled optics, light sources, metrology and motion. The firm’s job was to make those parts behave as one tool, shift after shift, inside a fab that cannot afford a bad Tuesday.
The commercial break arrived in the 1990s with the PAS 5500 platform. Productivity and resolution finally matched what chipmakers would pay for. Profit followed customers. A stock-market listing in 1995 opened the funding tap for research and for factories. That sequence matters. Capital arrived after a product customers actually wanted, not before.
Why Integration Beat the Old Champions
Lithography was already too tangled for one laboratory to own every discipline. Light, vacuum, vibration, software, thermal drift, wafer handling: each field has its own priesthood. The Dutch approach was to rent the priesthoods and own the architecture. Two large Japanese rivals stayed in the race for years. They did not stay level once the next wavelength became the whole game.
Extreme ultraviolet light had been a conference-slide promise for a long time. Turning it into a tool that could run high-volume production was another matter. Chipmakers helped pay for the attempt, because their own roadmaps depended on it. In 2012 customers committed €1.38 billion of research funding and took minority stakes. One American chipmaker alone pledged €829 million of development money and was prepared to own up to 15% of the supplier. Read that again. The buyers financed the seller.
When your customers write cheques for your research and buy a slice of your equity, you are no longer a vendor in the ordinary sense. You are part of their factory plan.
That funding did not create the monopoly on its own. Decades of supplier relationships, process knowledge and field data did. By the time commercial EUV tools shipped, the hard part was already behind the curtain: a network that knew how to build parts no catalogue sells.
What the Machine Actually Does
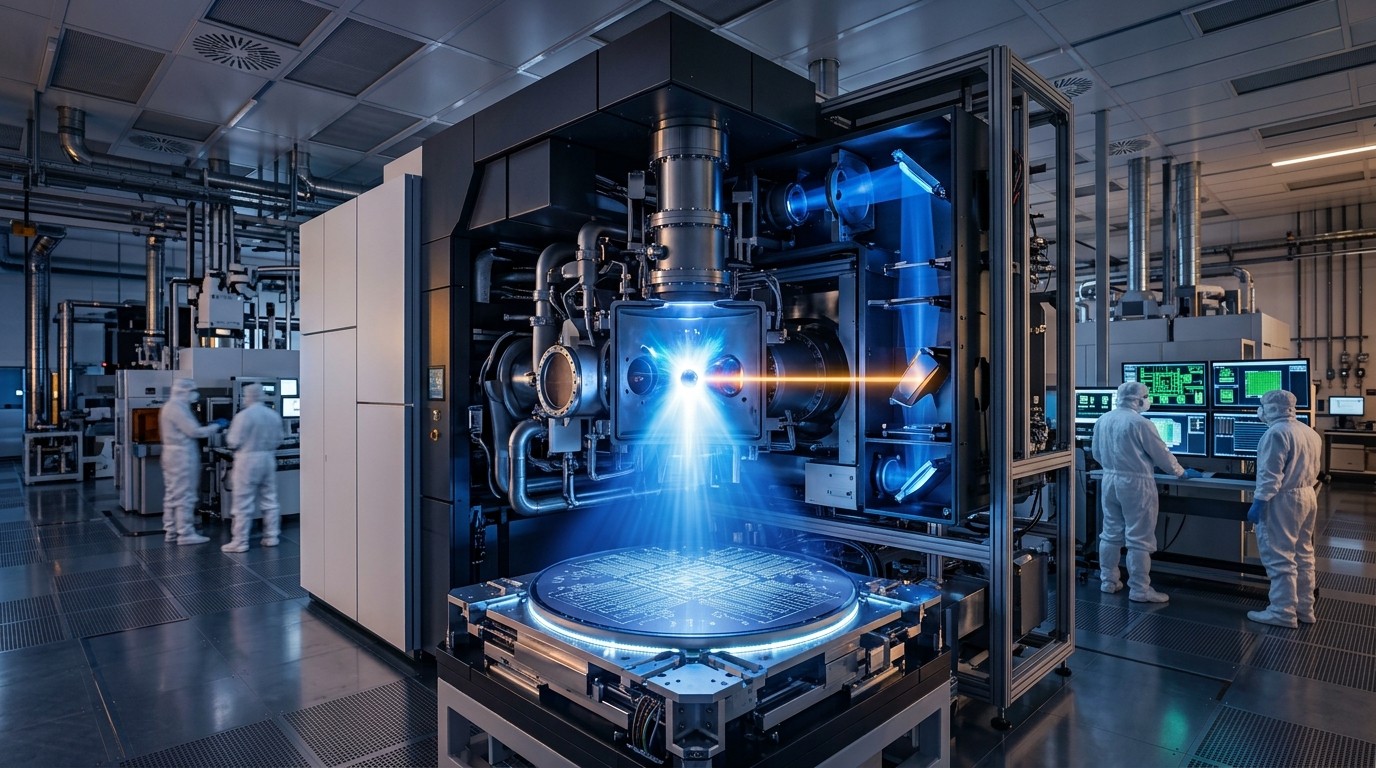
Strip away the brochure language and the physics is still wild. A laser hits tens of thousands of microscopic droplets of molten tin every second. Each hit makes a plasma. That plasma throws light at a wavelength of 13.5 nanometres. Mirrors, not lenses, steer it. The pattern lands on a wafer, a thin disc of silicon, and becomes the transistors and wiring of a chip. German optics specialists cut the mirrors. A laser maker supplies the light engine. Stages, sensors and software come from a scatter of other firms. Roughly 80% of the bill of materials is bought in. The value sits in making the whole stack reliable enough for a €20 billion factory.
An error a human eye would never see can scrap a leading-edge layer. That is why “we could build one in a few years” is usually said by people who have never aligned a wafer stage to the tolerance these tools demand. A drawing is not a production tool. A production tool is a decade of failures that nobody else paid for.
The Economics Inside a €20 Billion Fab
A cutting-edge fabrication plant can cost more than $20 billion to build and fill. Lithography scanners are among the dearest tools in that bill. The return does not come from the sticker price. It comes from how many good chips leave the building, how fast, and at what cost per wafer. Smaller features pack more compute onto each disc. Higher throughput and better yield decide whether the plant earns its keep.
That is the quiet leverage. A more capable scanner can pull more wafers through an already ruinously expensive shell. A small gain in accuracy can lift the share of those wafers that become saleable chips. Buyers therefore judge the tool against the cost of falling a node behind, not against a competing quote that does not exist. Perhaps the most interesting aspect is how calmly customers pre-commit capital years before delivery. They are not impulse-buying buses. They are reserving a place in a queue that sets their process roadmap.
Low-NA EUV systems, where NA means numerical aperture, the optical system’s ability to resolve fine detail, sell for roughly €180 million. High-NA tools, which print still smaller features, clear €350 million. EUV system sales reached €11.6 billion in 2025. Customers keep signing because the alternative is a factory that cannot make the chips the market will pay up for.
| Piece of the story | 2025 snapshot | Why it matters |
| Group sales | €32.7 billion | Scale after four decades of integration |
| EUV systems recognised | 48 | Few units, enormous tickets |
| Installed-base revenue | €8.2 billion | Service and upgrades, up 26% |
| Gross margin | 52.8% | Pricing power in a thin market |
| Net income | €9.6 billion | Cash generation behind the moat |
| Systems recognised, all types | 327 | Down from 418 in 2024 and 449 in 2023 |
Notice the last row. Unit shipments fell even while the franchise looked untouchable. That is the tell. Monopoly and smooth earnings are not the same sentence.
A Moat You Cannot Order from a Catalogue
Why doesn’t a well-funded rival simply assemble an EUV machine? Because the machine is the easy sentence and the hard paragraph. A competitor would need the optics house, the laser house, the stage makers, the sensor firms and the software teams that grew up beside this architecture. Then it would have to integrate thousands of precise parts so the tool survives a production shift. Then it would have to persuade the world’s most cautious manufacturers to park an unproven scanner in their most valuable cleanroom.
There is a second advantage that does not show up on a parts list. Every installed tool teaches the supplier how the technology behaves when a real fab is pushing it. About 10,000 customer-support people work around the world keeping systems up, fitting upgrades and debugging the oddities that only appear at volume. In my experience, that field loop is where equipment companies either compound or stall. A lab prototype can impress a delegation. A tool that holds overlay and throughput for months is a different species.
- System architecture owned in one place, components sourced from specialists built over decades
- Customer money and minority stakes that tied buyers to the development path
- Field data from every running machine, fed back into the next generation
- An installed base that must be serviced, so revenue does not stop at delivery
- No commercial alternative at the extreme-ultraviolet leading edge
Once a fab is laid out around this equipment, maintenance and upgrades become part of the process, not an optional extra. Installed-base management, mostly service and field options, hit €8.2 billion in 2025. That book grows as the fleet grows. It will not cancel a downcycle. It does soften the idea that this is only a lumpy hardware shop.
Where the Money Came From in 2025
Geography is both a strength and a nerve. China accounted for 29.1% of sales in 2025, though much of that was mainstream equipment rather than the EUV systems at the centre of the franchise. Taiwan was 25.5%. South Korea another 25%. The largest single customer was 23.9% of sales. The top two were 38%. That is concentration you can feel.
Export rules have already limited some system sales and some services into China. Losing a slice of that market hurts revenue. It also keeps an alternative EUV source from appearing inside a market the West is trying to constrain. I don’t pretend that trade-off is comfortable. It is simply the one policymakers chose, and the supplier has to live inside it.
Taiwan and the Korean peninsula add a different kind of risk. Customers and suppliers sit on both. A serious disruption would smash semiconductor output far beyond one equipment maker. For shareholders, that is systemic exposure dressed up as a country split on a slide.
The Cycle Still Bites
Nearer term, the familiar threat is timing. Few machines, very high prices, customer capital expenditure that moves in clumps. Recognised systems dropped from 449 in 2023 to 418 in 2024 and 327 in 2025. A big customer sliding a fab by a year can swing the printed year even if the decade still looks intact. Anyone who models this name as a smooth compounder is, frankly, arguing with the order book.
Management has been open that buyers can delay a new technology if the economics do not clear, or drift toward designs that lean less on successive lithography shrinks. High-NA tools cost hundreds of millions. Chiplets, advanced packaging and clever architecture can raise performance without asking every transistor to get smaller. If those routes pay better than the next shrink, the willingness to fund each new scanner generation could cool.
So far, that displacement is a theory, not a shipping product. AI demand for advanced logic and memory helped pull EUV orders in 2025. The company has said growth in both markets supported system demand. Useful. Not the same as a permanent bid under every tool.
A moat tells you the competitor is missing. It does not tell you the customer will spend this quarter.
A line I keep taped above equipment-stock models
What Changed in the 2026 Guidance
The tone firmed after 2025. Second-quarter 2026 sales were €9.3 billion with a 54% gross margin. Full-year revenue guidance moved up to €43 billion–€45 billion, from €34 billion–€39 billion at the start of the year. Management pointed to AI-related investment and customers pulling expansion plans forward. That is a violent revision for a business that ships hundreds of tools, not millions of handsets.
Longer-range modelling puts a 2030 revenue opportunity between €44 billion and €60 billion, with gross margins of 56% to 60%. Treat that as a range of possibility, not a promise. The speed of the 2026 upgrade shows how fast the top line can re-rate when a handful of fabs say yes at once. It also shows the reverse gear. The same concentration that lifts guidance can drop it.
A rough mental model, not a forecast:
  Tool sales = few decisions x very high price
  Service    = fleet size x uptime x upgrades
  Margin     = pricing power minus mix and start-up costs
  Multiple   = how sure the market is about the next two years
AI Is the Accelerant, Not the Foundation
It is tempting to file the whole story under artificial intelligence and move on. I think that is lazy. AI is pulling forward advanced logic and high-bandwidth memory, and those chips need leading-edge lithography. Fine. The durable case is older: computing demand keeps rising, and somebody has to print the patterns. The firm does not need every future chip to be an AI chip. It needs chipmakers to keep caring about resolution, yield and wafers per day.
If packaging and chiplets steal the spotlight, lithography does not vanish. It becomes one lever among several. That is a different growth slope, not an obituary. Investors who price a straight line from today’s AI rush to 2035 are doing more storytelling than the factory engineers.
Threats Worth Actually Pricing
Three buckets cover most of the downside that is real, as opposed to theatrical.
- Export rules that shrink the addressable set of fabs, especially in China, without creating a rival EUV source
- A semiconductor downturn that delays orders, even from customers who still believe in the roadmap
- A technology shift in which chiplets, packaging or new architectures earn better returns than the next lithography generation
A fourth sits underneath: geographic concentration. Taiwan and South Korea are not rounding errors. A shock there hits the whole industry, this supplier included. None of these has, so far, produced a commercial substitute for leading-edge EUV. Absence of a substitute is not absence of a drawdown.
How the Shares Are Priced
Around €1,700 a share, the stock has tended to sit on a premium multiple because the franchise is obvious. Roughly 35 times consensus 2026 earnings and about 25 times projected 2027 earnings is the neighbourhood. Those numbers can look sensible if earnings really do sprint. Management is aiming at €43 billion–€45 billion of 2026 revenue, up from €32.7 billion in 2025, and analysts look for further earnings growth in 2027. The multiple leaves less room for a wobble. A softer cycle, slower high-NA adoption or tighter China rules can compress the rating even if the competitive position is untouched.
The long-term question is blunter. Can future earnings from this position justify the price already in the market? A business can keep compounding while the shares fall, if investors paid up for growth that arrives late or smaller. More comfortable entries have historically shown up when the cycle turns and the conversation shrinks to next quarter’s orders. That is not a timing service. It is a description of how this stock has behaved.
What a Buyer Is Really Underwriting
If I strip the pitch to what has to stay true, I get a short list. Chipmakers must keep spending on new process technology. The supplier network must remain exclusive in practice, not just in theory. High-NA has to earn its keep often enough that the roadmap does not stall. Service revenue must keep scaling with the fleet. Export rules must not bite so hard that the growth math breaks, and a geopolitical shock in East Asia must stay a risk rather than an event.
Miss two of those and the premium multiple does the damage before the factory does. Hit most of them and the 2030 opportunity range stops looking like marketing. I would rather own the debate in those terms than in slogans about “the most important company in the world.” Importance is not a valuation.
A Walk Through the Supplier Web
People fixate on the logo on the scanner. The scanner is a concert. Mirrors from a German optics house sit at the centre of the optical train. Lasers from a specialist light-source maker strike the tin. Other firms handle wafer stages, sensors, vacuum hardware and the software that keeps a 180-tonne instrument from drifting out of spec. The Dutch firm coordinates. It does not smelt every gram.
That split is a strength until a critical supplier stumbles. It is also why a state-backed crash programme struggles. You cannot nationalise a network that took thirty years to learn each other’s tolerances. Governments can fund buildings. They cannot compress apprenticeship. I’ve watched industrial-policy announcements treat lithography as a procurement problem. It is closer to a guild.
Customers know this, which is why they funded development instead of waiting for a second source that never arrived. Dependence is uncomfortable. Falling off the leading edge is worse. So the cheques got written.
Service Is the Quiet Second Business
Hardware headlines dominate. The installed base is where the relationship actually lives. Engineers stay on site. Upgrades land as field options. Performance is nursed across a tool’s working life. Revenue from that work rose 26% in 2025 to €8.2 billion. As more EUV systems enter production, that annuity-like stream should thicken, even though it will never be as smooth as a software subscription. Fabs still pause. Tools still get delayed. But a scanner that is already printing wafers needs care whether or not the next purchase order is signed.
For anyone comparing this name with ordinary capital-goods stocks, that mix is the distinction. You are not only betting on the next wave of fab announcements. You are also betting on a fleet that dislikes being left alone. The margin on service is part of why group gross margin can sit above 50% in a business that ships metal.
High-NA and the Price of the Next Step
Numerical aperture is the dry phrase for a very expensive idea. Raise it, and the optic can resolve finer features. High-NA EUV is the current expression of that idea, with price tags north of €350 million. Customers will not adopt it because the brochure is pretty. They will adopt it if the extra resolution and the process simplification pay for themselves in yield and density.
There is a plausible pause here. Some layers might stay on older tools longer. Some performance gains might come from packaging several chips together rather than shrinking one die forever. The supplier has already flagged that buyers can wait if the economics do not justify the cost. That sentence should sit in any note next to the moat paragraph. Both can be true.
If high-NA ramps cleanly, the 2030 margin ambition of 56% to 60% has a path. If it ramps in fits, revenue still grows on low-NA and service, just more slowly than the bull deck. I would rather see adoption rates than listen to another metaphor about picking shovels.
Customer Power That Isn’t
Textbook procurement says a giant buyer squeezes a supplier. Here the textbook frays. The buyers are among the largest companies on earth. Their options at the leading edge are not. They cannot switch to an equivalent EUV system, because there isn’t one on the commercial market. Bargaining shows up in delivery slots, service terms and the pace of adoption, not in a credible threat to walk to a rival booth.
That imbalance explains the 2012 equity-and-funding deal better than any strategy slide. Intel, Samsung and TSMC were not being generous. They were buying time on a roadmap they did not control. The result locked in commercial EUV and, with it, the integrator that had spent the previous decades assembling the only network able to deliver it.
What Could Actually Displace the Tool
Displacement does not require a copycat scanner. It requires chipmakers to get the performance they need by another route often enough that scanner spending flattens. Advanced packaging, chiplets, new memory architectures, and software that extracts more from existing silicon all nibble at the same budget. None of them, yet, has shown up at commercial scale as a replacement for leading-edge lithography. AI, if anything, has argued the other way: more advanced logic, more advanced memory, more tools.
Still, the price of each shrink is rising. At some point a chief financial officer will ask whether the next €350 million machine beats a packaging line and a redesigned floorplan. That question is the fundamental threat. Export controls are a policy variable. The cycle is a timing variable. Architecture is the one that could change the slope.
A Shareholder’s Checklist Before the Premium
None of this is a recommendation to buy or sell. It is a way to keep the story honest when the share price is doing the talking.
- Is 2026 guidance being met because fabs pulled orders forward, or because the installed plan genuinely grew?
- How fast is high-NA moving from showcase to repetitive production?
- What share of China revenue is mainstream tools that can still ship, versus leading-edge tools that cannot?
- Does installed-base revenue keep growing if new system recognition dips again?
- Are the top two customers still more than a third of sales, and what does a delay at either do to a single year?
Answer those and the multiple either earns its keep or it doesn’t. Around 35 times near-term earnings is a vote that the sprint continues. Around 25 times the year after is a vote that it doesn’t collapse. Votes can be wrong in both directions.
The Human Side of a 180-Tonne Instrument
It is easy to talk about this company as if it were a force of nature. It is a payroll, a supplier argument, a night shift in Veldhoven, a customer engineer in Hsinchu staring at a yield chart. The early years were a cash drain that reasonable parents wanted to abandon. The listing worked because the PAS 5500 had already proved itself. EUV worked because customers were scared enough of the alternative to fund it. None of that was destiny. It was a sequence of expensive bets that happened to land.
That history is why I distrust clean narratives. The same organisation that looks unassailable in a bull market looked optional in 1984. The moat is real. It was built by people who stayed with a technology the market kept postponing. If the next postponement arrives, the people will still be there. The multiple might not.
Putting the Numbers Next to the Story
Let me lay the recent run in plain language. Sales of €32.7 billion in 2025. Gross margin 52.8%. Net income €9.6 billion. Service and upgrades €8.2 billion. Then a second quarter of 2026 at €9.3 billion and 54% gross margin, and a full-year aim of €43 billion to €45 billion. The 2030 opportunity band of €44 billion to €60 billion, margins 56% to 60%, sits just beyond that. If 2026 lands near the top of guidance, the company is already knocking on the bottom of its own 2030 range, four years early. That either means the range was cautious or the cycle is hot. Both can be true. Hot cycles cool.
Unit counts tell the other half. Fewer systems recognised in 2025 than in 2024 or 2023, yet EUV value held up because the mix shifted toward the dearest tools. Mix can flatter a year. It can also reverse. A year heavy on high-NA announcements and light on deliveries is a different animal from a year in which tools actually print wafers and get paid for.
China at 29.1%, Taiwan at 25.5%, South Korea at 25%: three markets, most of the book. The largest customer at 23.9%, the top two at 38%. Diversification is a slide title, not a description. Anyone sizing a position should size the customer, not just the ticker.
Why the Start-Up Years Still Matter
Investors love origin myths when the ending is a monopoly. The useful part of this myth is the method. Do not build every component. Integrate what specialists already do better. Stay alive long enough for the product cycle to turn in your favour. Take outside capital once customers exist, not before. Accept customer money for the next wavelength, even if it means minority stakes and awkward board dynamics. Then spend the following decade turning that wavelength into something a fab will trust at 2 a.m.
Rivals who tried to own the whole stack had breadth and lost the timeline. The integrator had focus and a phone book. When EUV stopped being a paper, the phone book was the barrier. That is the part a new entrant, state-backed or not, still has to recreate. Money shortens some waits. It does not train a mirror polisher.
A Note on Language and Hype
You will hear this firm called the tollbooth of the chip industry. The metaphor is half right. There is a toll, and at the leading edge there is one booth. The half that misleads is permanence. Tollbooths get bypassed when traffic finds another road. Packaging, architecture and older-node chips that are suddenly “good enough” are the side roads. They have not emptied the highway. They are on the map.
I also distrust the claim that any single equipment company “rules the world.” It rules a step. Design still happens elsewhere. Materials, deposition, etch and test are other franchises. A phone still needs a dozen suppliers who are not in this story. Precision about the step is what keeps the investment case from turning into folklore.
Where I Land
Four decades built a position that is genuinely difficult to challenge. The machines are scarce, the physics is unforgiving, the supplier web is old, and the customers helped pay for the lock-in. Service revenue is large and growing. AI has pulled demand forward and pushed 2026 guidance sharply higher. That is the bull case, and it is not imaginary.
The bear case is not “someone clones the scanner next year.” It is valuation, timing and architecture. At roughly 35 times this year’s expected earnings, disappointment has a price. China restrictions can shave the book. A delayed fab can dent a year. High-NA can arrive more slowly than the slides suggest. East Asian concentration is a fact, not a footnote. A business this strong can still be a poor purchase if the entry multiple assumes a decade that shows up in three years.
So the investment question is narrower than the technology question. The technology question has mostly been answered: at the leading edge, there is one commercial EUV supplier, and replacing it is not a procurement exercise. The investment question is whether the earnings still to come justify what the market is asking today. Better prices have a habit of appearing when orders hiccup and the narrative shortens. Until then, anyone buying is paying for a moat they can describe and a cycle they cannot schedule.
If you only remember one image, make it the tin droplet. Tens of thousands of them a second, each one a tiny sun, each sun a line on a wafer, each wafer a reason a factory spent €180 million so it would not fall behind. That is the business. The share price is a separate argument, and it deserves to be had with the order book open.