
I kept coming back to a number that should not exist in a serious industrial economy. A strategic stockpile of tungsten, the metal that hardens armor-piercing rounds and keeps cutting tools from melting, had been drawn down to almost nothing. Not a rounding error. Almost nothing. Then a corporate note landed saying a mine in South Korea had started shipping concentrate. That combination felt less like a routine mining update and more like someone finally plugging a hole the rest of us had agreed to ignore.
If you follow metals only when copper screams or gold makes a headline, tungsten is easy to miss. It is not pretty. It does not trade on every retail app. It sits inside drill bits, turbine blades, semiconductors, and munitions, doing a job almost nothing else can do at the same density and melting point. China has held a quasi-monopoly over mining and, more importantly, refining for years. The West talked about diversification. The mountain in Gangwon Province just started answering.
Why a Quiet Korean Shipment Matters More Than the Headline
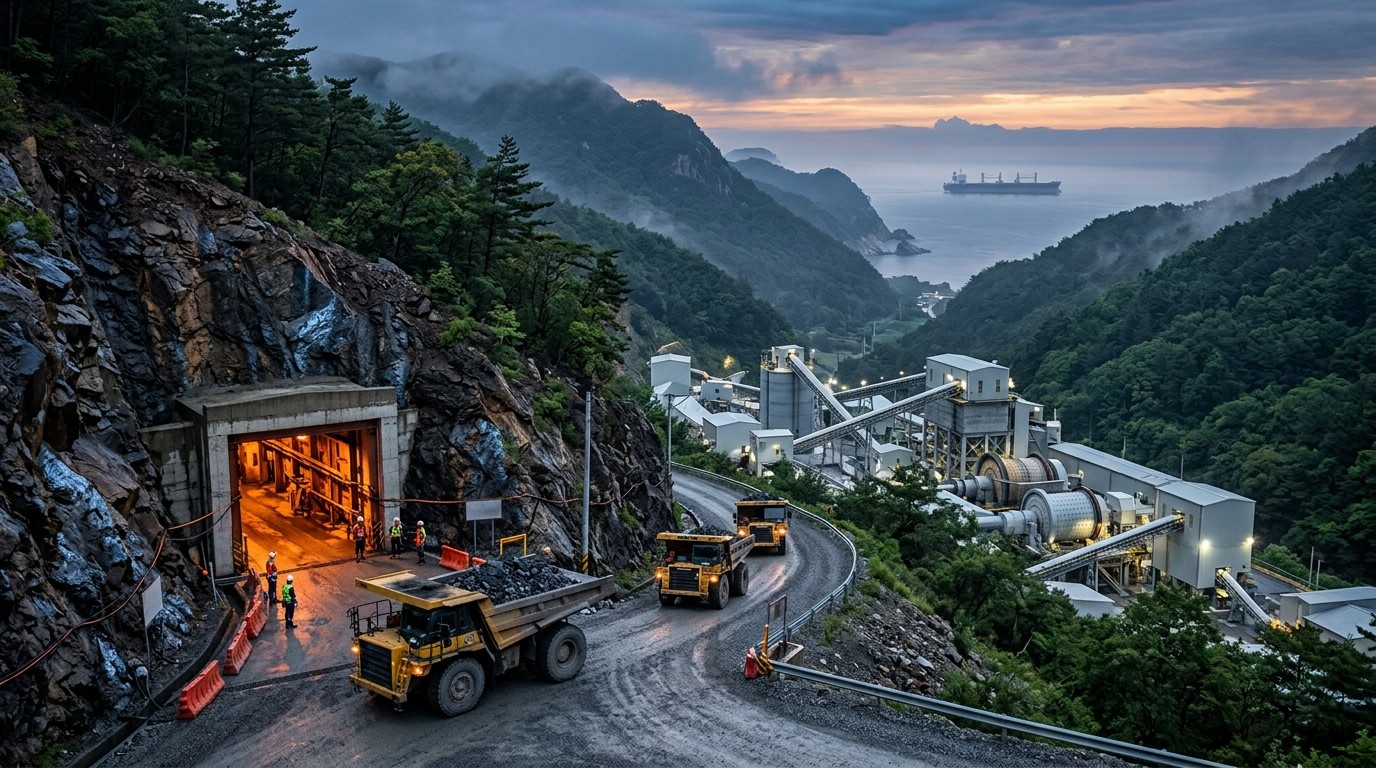
The operator behind Sangdong has told the market that concentrate is moving, that the plant is heading toward round-the-clock running, and that roughly 4.6 months of stockpiled ore sits on the surface to cushion the ramp. Phase two development is already underground, with completion penciled in for 2027. On a spreadsheet that reads like a clean sequence. On a mine site it is a chain of small decisions that either hold or do not.
I have found that the most useful way to read a first shipment is not as a victory lap. It is a proof of plumbing. Ore came out of the ground. It went through a circuit. A saleable product left the gate. That is rarer than pitch decks admit, especially in a metal whose processing know-how spent a generation concentrating in one country.
Leadership at the company put it bluntly in a statement that circulated with the update. Tungsten mined and processed in an allied nation is now a reality, they said, and called the moment defining for both the firm and for Western supply chains. Grand language, sure. The underlying claim is testable. Either the mill keeps running, or it does not.
Tungsten mined and processed in an allied nation is now a reality. That is the line the market has to stress-test, not applaud.
Company leadership, paraphrased from the production update
Perhaps the most interesting aspect is the stockpile. Surface ore is usually treated as inventory, a boring line in working capital. Here it is time. Time to tune the plant without starving it. Time to push development deeper while phase one learns how to behave. Mines fail in the gap between first ore and steady state more often than they fail in the geology. A few months of feed does not guarantee success. It removes one classic excuse.
What Tungsten Actually Does When the Lights Are On
Skip the textbook density figures for a second. Picture a machine shop that cannot get carbide inserts. Cycle times stretch. Scrap rises. A defense line waiting on penetrators does not get a polite delay notice. It gets a hole in the schedule. Tungsten’s melting point sits near 3,422 degrees Celsius. Steel gives up long before that. Substitutes exist in some civilian uses. In high-stress military and industrial jobs, they are compromises, not replacements.
That is why a depleted strategic reserve reads as more than a procurement footnote. Analysts covering aerospace and defense have pointed out that the United States stockpile of the metal has been drawn down to a thin remainder. Rearmament talk in Europe and across allied capitals is already showing up in order books for missiles, drones, vehicles, and aircraft. Every one of those platforms quietly assumes a materials chain that, until recently, ran through a single dominant producer.
Shortages do not announce themselves with a press conference. They show up as a missed delivery, a requalified part, a price spike that procurement cannot pass through. Early movers who can put conflict-free units on a dock get the first call. Everyone else writes a white paper.
The Bottleneck Nobody Wanted to Own
There is a phrase making the rounds among people who actually buy metal rather than tweet about it: own the bottlenecks. Not the whole chain. The narrow points. Tungsten has two. One is the mine. The other is the chemical and powder processing that turns concentrate into something a mill or a munitions plant will accept.
China still controls the bulk of both, and serious equity research on European defense has been clear that this grip does not vanish before the end of the decade. A Korean mine does not repeal that. It punches a hole in it. Phase two, if it lands as designed, would lift throughput toward 1.2 million tonnes a year and could support more than 460,000 metric ton units of tungsten trioxide annually. That would place Sangdong among the largest producing operations outside China, and on current plans the largest one actually producing.
Large is a relative word. Global tungsten demand is not copper-sized. A single credible ex-China source can still move the psychology of buyers who have spent years dual-sourcing on paper and single-sourcing in practice.
How the Ramp Is Actually Being Built
The company has been unusually specific about the sequencing, which I appreciate. Specificity is harder to walk back than slogans. Mining teams, freed by the surface stockpile, have turned toward underground development for the expansion. A global minerals-processing group is on site with the operators, tuning today’s circuit and sketching tomorrow’s. Orders are going in for the mills that would power phase two. Same partner, next machine.
That partner matters more than a logo on a slide. Commissioning a tungsten plant is not a copy-paste of a gold mill. Gravity circuits, flotation, the handling of a dense, abrasive ore, the spec on the concentrate a downstream buyer will take without a fight. Having the equipment supplier’s engineers in the building during ramp-up is the unglamorous version of risk management.
Phase one has to learn its own bad habits before phase two copies the good ones. If recovery disappoints, if the concentrate grade wobbles, if maintenance windows eat the nights they planned to run, the 2027 story slips. I would rather hear a management team admit that than pretend a Gantt chart is geology.
- Surface stockpile of about 4.6 months of ore, buying ramp time without idling the mill
- Shift toward 24-hour operations as the circuit settles
- Underground development for the expansion already advancing
- Processing-equipment orders placed for the larger mills
- Phase two completion targeted for 2027, not a vague later
None of those bullets is a guarantee. Together they describe a project that has left the slide-deck stage. That distinction is worth money, and it is also worth skepticism.
The Numbers Analysts Are Willing to Put on Paper
A detailed sell-side model tied to the update forecasts consolidated output rising from 126,287 metric ton units in 2026 to 444,400 in 2027. All-in sustaining costs in that same model fall from about $905 per metric ton unit to about $319. Read those figures twice. They are not history. They are a path that assumes the ramp works, the expansion arrives, and the cost curve does what operating leverage usually does when a plant fills.
I have watched too many mine models treat year two as a victory lap. The drop in unit cost is mostly math. Fixed costs spread over more units. If the units do not show up, the $319 never arrives and the $905 hangs around like an uninvited guest. Still, the shape of the forecast tells you what the bull case needs. Volume, then cost. Not the other way around.
| Marker | Near-term picture | Expansion case |
| Plant feed | Phase one ramp, stockpile support | Up to 1.2 million tonnes a year |
| Contained output | Model near 126,000 MTU in 2026 | Model near 444,000 MTU in 2027, site potential above 460,000 |
| Unit cost | Model AISC near $905 per MTU | Model AISC near $319 per MTU if volume lands |
| Timing | Concentrate already shipping | Phase two aimed at 2027 |
| Strategic role | Proof of allied processing | One of the largest ex-China producers |
Coverage that published alongside the update kept a buy rating and a 12-month target of $25.50, framed as roughly 93 percent above the prior close cited in the note. Targets are opinions with a spreadsheet attached. The useful part is the gap they imply between today’s price and a world where Sangdong behaves. Markets will close that gap only if shipments keep leaving the gate.
China’s Grip Does Not End Because One Gate Opened
Let’s be plain. A single Korean operation, even a big one, does not dethrone a system built over decades of mining, roasting, APT conversion, and powder metallurgy. Export licensing, domestic stockpiling, and the simple fact of installed capacity still sit with the dominant producer. Research on the defense complex has been consistent on the timeline. Control over critical-materials mining and refining remains a live variable through the end of this decade.
That is not an argument for doing nothing. It is an argument for treating Sangdong as a wedge, not a wall. Buyers who can qualify a second source now will spend the next five years less exposed to a policy decision made somewhere they do not vote. Buyers who wait for a perfect diversified market will meet the next restriction with a empty qualified-vendor list.
Conflict-free is doing a lot of work in this conversation. It means origin that allied procurement can defend, traceability that does not collapse under audit, and processing that does not quietly route back through the same bottleneck. A mine in an allied country helps the first two. The third still needs contracts, labs, and patience.
Rearmament Is Not a Slogan on This Metal
Defense analysts have been describing a rearmament cycle in Europe, and more broadly across Western capitals, as already underway rather than hypothetical. Missiles, bombs, drones, fighter aircraft, armored vehicles. The shopping list is public. The materials list is not, until a program manager cannot get a heat of alloy or a lot of penetrator blanks.
Tungsten shows up in kinetic energy penetrators, in fragmentation designs, in counterweights, in high-temperature alloys, in the tools that machine the other parts. Lose the tool and you lose the part even if the alloy itself is available. That double exposure is why industrial buyers and defense buyers end up bidding on the same scarce units when supply tightens. Civilian demand does not politely step aside.
Policy in Washington has spent the past couple of years talking about conflict-free critical supply in a more concrete way than the previous decade managed. Stockpile draws make the talk less optional. A mine that can deliver this year, not in a permitting fantasy, sits in the path of that push. I do not think every critical-minerals name gets a tailwind. I think the ones with tonnes on a truck do.
- Qualify the concentrate against the specs buyers already use
- Lock offtake that survives a price spike and a price dip
- Keep phase one stable long enough that phase two is a copy, not a rescue
- Build processing options that do not collapse back into one country
- Treat stockpile policy as a customer, not a press release
What the Stockpile on the Surface Is Really Buying
Management’s own color on the ramp is worth sitting with, because it explains the operating logic better than a production table. The stockpile feeds the mill. It also buys calendar. With enough ore on hand to carry phase one through ramp-up and early production, crews can work deeper in the mountain on the expansion. Drills advance below while the plant above gets its habits straight.
That split is how you avoid the classic trap, where development starves the mill or the mill starves development. It is also how you spend money in two places at once. Investors who wanted a single-phase story may find the dual track noisier. Operators who have lived through a stalled ramp will recognize it as the safer mess.
The processing partner on site is not there for a ribbon cutting. Fine-tuning a live plant and laying groundwork for the next set of mills is the same conversation if you do it properly. Recovery, grind size, reagent choice, maintenance access. Get those wrong in phase one and you pour concrete on the mistake in phase two.
Ramp logic, stripped of slogans:
  Stockpile covers feed
  Mill learns its circuit
  Development pushes phase two
  Equipment orders follow the learning
  2027 is a date, not a mood
Costs, Grade, and the Part Models Smooth Over
Tungsten projects live and die on grade and recovery more than on the romance of a historic district. Sangdong is an old camp brought back, not a greenfield drawn on a blank map. That cuts some risk and adds others. Old workings, water, ground conditions, a community that has seen mining come and go. The modern plant is the new variable. Historic resource is the old one.
All-in sustaining cost collapsing toward the low hundreds of dollars per metric ton unit only happens if throughput and recovery cooperate. Power, labor, reagents, and the underground development that phase two still has to finish sit underneath that average. A bad quarter of ground support can erase a good quarter of mill performance. Anyone selling you a straight line from here to 2027 is selling you a drawing.
Still, the direction of travel is what buyers care about. A credible cost curve outside the dominant producer gives procurement a number to put next to a political risk premium. Sometimes that premium is worth more than the metal.
Who Actually Wins If the Tonnes Show Up
Three groups, in my view, and they do not win equally. First, the operator, if execution matches the note. Equity in a mine that moves from developer story to shipper tends to re-rate in steps, not in one print, and it can give the gains back just as fast on a missed quarter. Second, downstream buyers in allied countries who can contract volume before everyone else wakes up. Third, the wider set of critical-minerals names that get dragged into the narrative even when their projects are years from a truck.
I am less interested in the third group. Narrative beta is a trade. Tonnes are a business. The update that matters is the one with a bill of lading, then another, then a quarter where the mill ran the hours it promised.
Employees and local contractors around the site win in a more ordinary way. Round-the-clock operations mean shifts, housing, parts, a reason for a town to treat the mine as a going concern rather than a construction site. That social license is not a footnote in Korea any more than it is in Nevada or the Nordics.
A Practical Way to Read the Next Four Quarters
Forget the target price for a minute. Here is the checklist I would actually keep. Concentrate shipped, not announced. Mill hours versus nameplate. Recovery versus the study. Development meters underground versus the phase-two plan. Cash balance against the equipment orders already placed. Any change in offtake language. Any quiet revision to the 2027 date.
Markets will obsess over the share price. The mine will obsess over the thickener and the filter press. Those are not the same obsession, and only one of them produces tungsten.
The stockpile buys time. Time is only useful if the plant spends it learning, not waiting.
There is also the price of the metal itself. A ramp into a weak tape is a different creature from a ramp into a tight one. Defense demand and industrial tooling do not move in lockstep. If Chinese exports loosen, the ex-China premium can compress even while the strategic argument stays intact. If exports tighten, Sangdong’s tonnes get bid before the plant has finished proving itself. Both paths are plausible. Neither is a reason to skip the operating data.
Allied Processing Is the Sentence That Has to Stay True
Mined in Korea is not the whole claim. Processed in an allied jurisdiction is the part that changes a buyer’s audit. Concentrate that still needs a conversion step in the dominant country is a partial hedge. The update’s language treats processing as part of the reality now in hand, at least for the product leaving Sangdong. Hold them to the spec, not the adjective.
Downstream, carbide plants and defense primes will want consistency across lots. A beautiful first shipment followed by a drifting grade is how qualified-vendor status gets delayed a year. The engineers on site from the mill supplier are there, in part, to stop that drift. Whether they succeed is an operating question, and it will show up in customer comments long before it shows up in a resource update.
I keep thinking about the stockpile figure for that reason. Four and a half months is enough to iron out a circuit if the ore behaves. It is not enough to redesign a flowsheet. The window is real and it is finite.
Where This Sits in a Wider Metals Tape
Critical minerals have spent the last few years as a policy trade and a disappointment trade at the same time. Permitting slipped. Prices slumped. A few projects became mines. Most remained studies. Tungsten never had the retail following of lithium, which spared it some of the worst multiple expansion and some of the worst collapse. It also left it under-owned by anyone except specialists and a handful of defense-minded accounts.
A producing asset with a visible expansion changes the set of people who can underwrite it. Generalist funds can model shipments. They cannot model a preliminary economic assessment with the same straight face. That shift in the audience is part of why a first concentrate shipment gets more attention than another drill intercept in a metal nobody can pronounce.
It also raises the cost of a miss. Developers are allowed to be late. Producers are not, or at least the market stops granting the same grace. Sangdong has stepped over that line. The next updates will be read as operations, not as vision.
Risks That Should Stay on the Same Page as the Upside
Execution risk is the obvious one, and it deserves to stay obvious. Underground development can hit water, structure, or equipment delays. Mills can under-recover. Labor markets in a tight Korean industrial belt are not infinite. Currency moves between the won, the dollar, and customer currencies will nudge margins even if the plant behaves.
Customer concentration is the quieter risk. A strategic metal with few qualified buyers can look like a dream offtake until one program slips and the volume has nowhere to go at the same price. Diversifying the book takes time the ramp may not feel it has.
Policy risk cuts both ways. Support for allied supply can arrive as stockpile purchases, loan guarantees, or procurement preferences. It can also arrive late, small, or tied to conditions a single mine cannot meet. Betting the equity case only on a government buyer is how projects disappoint people who thought politics was a contract.
And China remains the price setter more often than not. A decision to release material, restrict it, or subsidize a domestic producer can move the tape faster than any Korean mill report. Owning the bottleneck includes living with the incumbent’s response.
How a Buyer, Not a Trader, Might Use This
If I were running procurement for a tooling group or a defense subsystem, I would not wait for the 2027 nameplate. I would ask for lot consistency now, a visit, a spec sheet, and a conversation about what phase two does to available volume. Optionality is cheap before the rest of the industry makes the same call. It is expensive after.
If I were underwriting the equity, I would size the position off phase one performance and treat phase two as upside that has already started spending money, not as a free option. The orders for mills are a tell. Capital is moving. So is the burden of proof.
If I were a policymaker staring at an empty stockpile bin, I would care less about the share price and more about whether a second and third allied source can be pulled forward before the decade closes. One mountain is a start. A chain is the actual goal.
The Human Pace Inside an Industrial Story
It is easy to write about metric ton units and forget that a ramp is people on nights. A metallurgist arguing with a cyclone. A development crew waiting on a jumbo. A buyer in another country deciding whether the first bags of concentrate match the sample they signed off. Those arguments are the real critical path.
Corporate language about seamless movement into production is what you say when you want the market calm. Seamless is rarely how plants feel from the inside. Controlled, maybe. Busy. Slightly behind on one circuit and ahead on another. The stockpile is what lets that ordinary chaos stay ordinary instead of becoming a shutdown.
I will take ordinary chaos over a perfect deck. The deck was available for years while the stockpile in the United States quietly thinned. The chaos is new. New is the point.
What Would Change My Mind
A quarter where shipments stall and the explanation is vague. A phase-two date that slides without a ground-condition reason. A cost print that moves the wrong way after the mill has had time to settle. A customer who qualifies the product and then does not reorder. Any of those would pull this back from lifeline toward project.
The opposite set is dull and persuasive. Repeated shipments. Recovery in a band. Development meters that match the plan. A second customer. Equipment arriving for the expansion on something like the schedule implied by a 2027 finish. Dull is how real supply chains get built.
Price targets can wait. The metal cannot. That imbalance is the whole story, and it will stay the story until more than one allied gate can make the same claim Sangdong just made.
A Longer View Than the Next Print
Stand back from the ticker and the shape is familiar. A concentrated industrial input. A dominant processor. A strategic user that let inventories run off because the market looked supplied. A project in an allied country that spent years being early. Then a first shipment, and suddenly the early project is the only one with metal.
We have watched versions of this in other obscure materials. The names change. The regret does not. Buyers who treated diversification as a conference panel discover they needed a contract. Operators who shipped early discover they have leverage they should not waste on sloppy specs. Governments discover that stockpiles are not a metaphor.
Sangdong will not fix the decade by itself. It can make the next shortage less absolute. In a metal this narrow, less absolute is a large change. The Western lifeline framing is dramatic, and drama is cheap. The concentrate on the truck is not.
Useful filter: shipment confirmed, hours run, recovery held, development on plan, date intact. Everything else is commentary.There is a habit, in market write-ups, to end on the upside percentage. Ninety-three percent to a published target makes a fine last line and a poor decision rule. The better close is simpler. A mine outside the dominant producer is shipping. An expansion is already being dug. A stockpile that used to look comfortable in a government warehouse does not. If you care about the bottleneck, you now have something to watch that is not a speech.
I will be watching the unglamorous part. Night shift. Filter cake. The next lot that has to match the first. That is where a lifeline either holds or turns back into a headline.
None of this is a recommendation to buy or sell any security. Mines miss. Models age. Policy shifts. The only thing the first shipment proved is that the gate can open. Keeping it open is the work, and the work is just getting started.